With a 701 credit score, you can likely get approved for rewards credit cards, 0% intro APR cards, personal loans, prime-rate auto loans, and most mortgages.
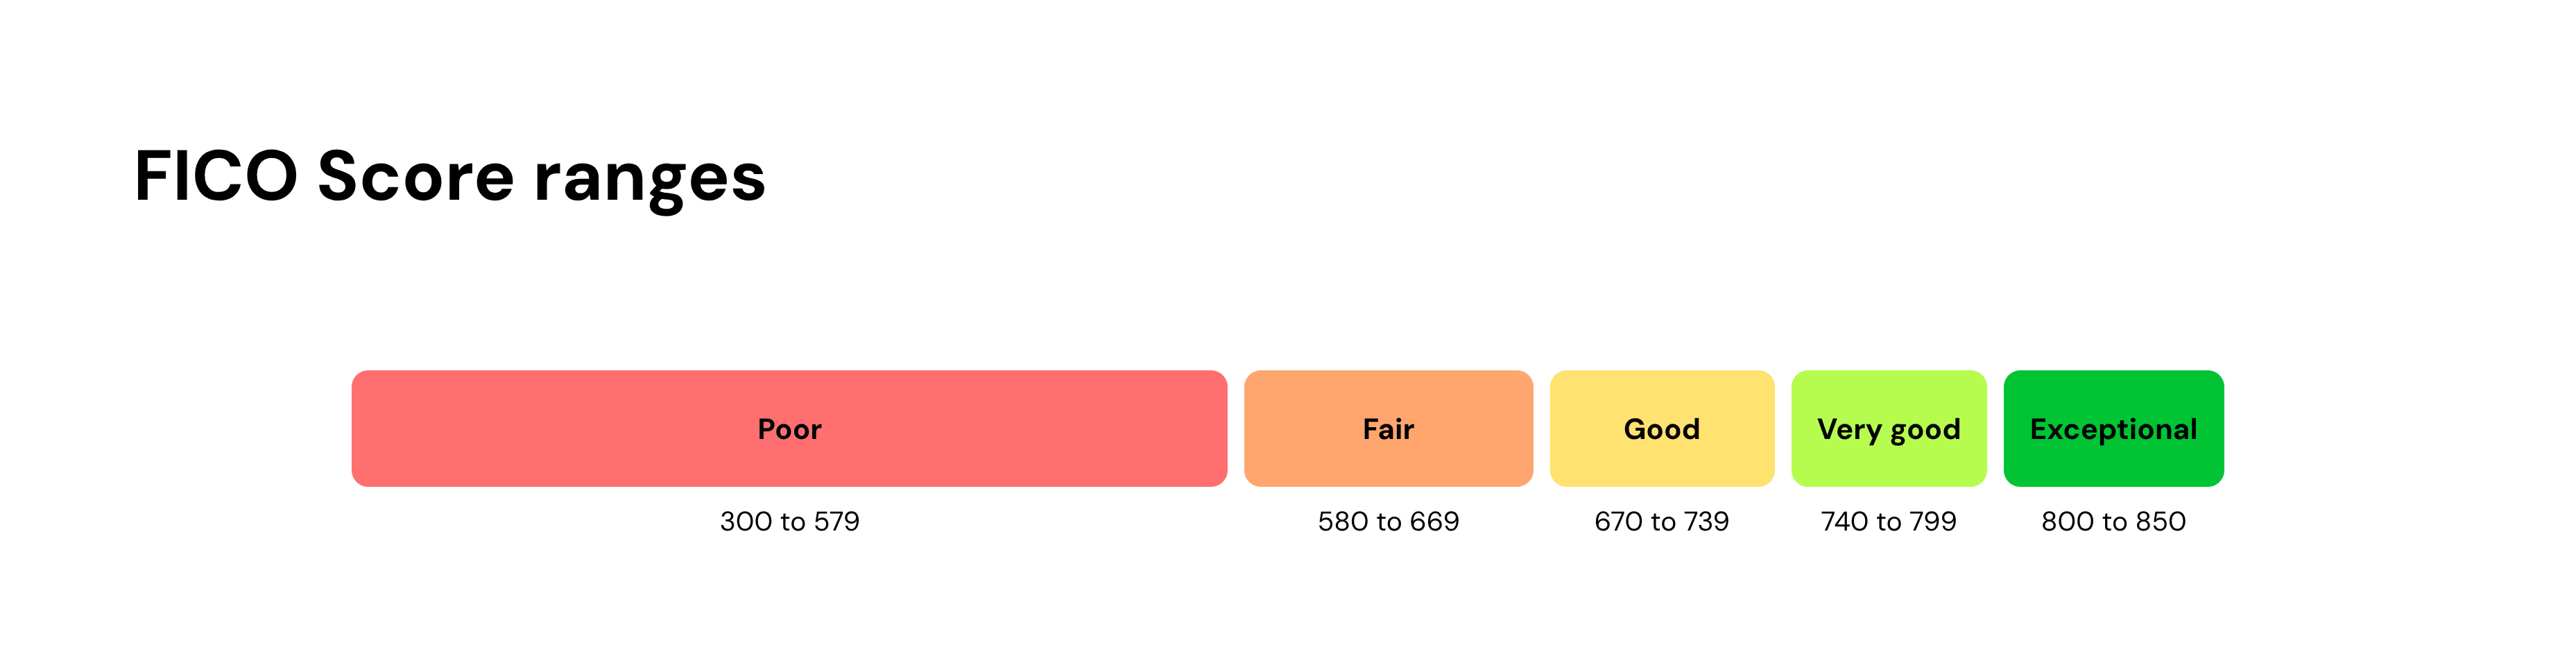
A 701 score is good credit. The lowest rates still go to higher scores, however. Very good credit starts at 740, which is 39 points away.
Is 701 a good credit score?
Yes. FICO's good range runs from 670 to 739, and 701 sits in the lower half of it. At 740, you'd move into very good credit.
What stands between 701 and very good credit is usually one of these factors:
- Card balances. Using a large share of your available credit holds your score down, even if you pay in full each month. Your issuer reports the balance on your statement.
- History length. A few years of accounts gives scoring models less to go on than a decade does. Length of credit history only grows with time.
- An older late payment. A payment 30 days or more late stays on your report for seven years. Its effect fades as on-time payments build behind it.
Read more >> What Can You Get Approved For With a 770 Credit Score?
What can you get approved for with a 701 credit score?
At 701, most lenders will approve you, so what's left is the price you get.
Credit cards
Rewards cards with cash back, points, welcome offers, or introductory 0% APR periods are realistic at 701. Some premium travel cards may look for higher scores. Before applying, check whether the issuer offers prequalification, which uses a soft credit check that doesn't affect your score. Only a full application adds a hard inquiry.
A good score doesn't make card interest cheap. The average rate on card accounts charging interest is 22.15%, according to the Federal Reserve. An intro 0% period helps only if you pay the balance off before it ends.
Personal loans
Most personal lenders will approve a 701 score if your income and debt-to-income ratio (DTI) check out. You'll often see rates near the middle of a lender's advertised range. For comparison, the Federal Reserve's average for a 24-month bank personal loan is 11.86%. Federal credit unions can't charge more than 18% on most loans, so include them when you compare options.
Auto loans
At 701, you're comfortably in Experian's prime tier (661 to 780). Your credit score plays a major role in the interest rate you're offered on a car loan. On a $20,000, 60-month new car loan at average rates, a prime borrower would pay about $1,000 more in interest than a super prime borrower. Super prime starts at 781, 80 points away. Experian sorts these tiers by VantageScore 4.0, so your FICO score may place you a little differently.
Manufacturer promotions like 0% financing may be in reach, so ask the dealer what score a specific promotion requires.
Use an auto loan calculator to check payment amounts before you sign.
Mortgages
At a 701 credit score, most mortgage types are open to you. Your score mainly decides what you pay, depending on the type:
- Conventional loans. Fannie Mae no longer sets a minimum score for loans run through its automated system, though lenders still set their own minimums. It does charge lenders an upfront fee on the loans it buys, based on your score and down payment. With 20% down, the fee is 1.375% of the loan amount for scores of 700 to 719, 1.25% at 720 to 739, 0.875% at 740 to 759, and 0.375% at 780+. At 701, you're just inside the 700 band. On a $200,000 loan, the fee is $2,750 at 701. Reaching 720 would cut it by about $250, and reaching 740 by about $1,000. You pay the fee through a higher rate or more cash at closing.
- FHA loans. Borrowers with scores of 580 or higher can qualify with 3.5% down. On a $250,000 home, that's $8,750 up front. Each lender can set higher minimums. If your down payment is small, get an FHA quote alongside a conventional one.
- Jumbo loans. These are for amounts above conventional loan limits. Each lender sets its own standards, usually stricter on score, income, and down payment, so whether 701 qualifies depends on the lender.
Run the numbers >> Use Kikoff's mortgage calculator to estimate your monthly payment and plan your homebuying budget.
What interest rates can you expect with a 701 credit score?
Expect solid offers, but not necessarily a lender's best. The Federal Reserve's averages across all borrowers were 22.15% for card accounts charging interest and 11.86% for 24-month bank personal loans. At 701, your offers will likely land at or below those averages.
The next FICO range, very good, starts at 740, 39 points up. A smaller mortgage fee step comes sooner, at 720.
5 ways to raise a 701 credit score
- Check your credit reports for errors. You can get all three for free every week at AnnualCreditReport.com. If something is wrong, like an account that isn't yours, dispute it with the bureau. Disputing is free.
- Pay down card balances before the statement closes. Your issuer usually reports the statement balance, so paying early lowers the balance that reaches your report, even if you already pay in full.
- Pay every bill on time. Payment history is the biggest factor in your score, making up 35% of a FICO Score.
- Shop for rates within a tight window. FICO counts multiple auto, mortgage, or student loan inquiries made within a period of 14 to 45 days as one, depending on the FICO version. Credit card and personal loan applications each count separately, and each hard inquiry takes a few points off for about a year.
- Think twice before closing a card. Closing one removes its credit limit, which can raise your credit utilization if you carry balances on other cards.
If your report is thin on accounts, adding one helps. A Kikoff Credit Account reports your payments to all three bureaus.
Read more >> What Is a Good Credit Score in 2026?
Bottom line
A credit score of 701 gets you approved for most cards, loans, and mortgages. From here, your score decides how much you pay. In FICO's ranges, you're 39 points from very good credit at 740. You're also just 1 point inside Fannie Mae's 700 to 719 fee band, so protecting the points you have matters as much as adding new ones.
Kikoff brings credit building, bill and rent reporting, AI-powered disputes, credit monitoring, and debt negotiation into one place. Sign up with no credit check. Plans start at $5 a month.
Frequently Asked Questions
Article Sources
Disclaimer: The information provided in this blog post is meant for informational purposes only and does not constitute financial advice.