If you are building credit for the first time or working toward a stronger credit profile, time matters. Length of credit history is one of the five categories FICO uses to calculate its scores, and it generally accounts for 15% of a FICO Score.
That does not mean you need decades of experience to earn a good score. A short history simply gives a scoring model less information about how you manage credit over time. Payment history, debt, new credit, and credit mix also affect the result.
What does length of credit history mean?
Length of credit history describes how long the accounts on your credit report have been established. It is broader than the age of your oldest account.
According to FICO, this category may consider:
- The age of your oldest account
- The age of your newest account
- The average age of all your accounts
- How long particular types of accounts have been open
- How long it has been since you used certain accounts
People sometimes use “credit age” to mean their oldest account age or their average account age. Because the phrase is not always used consistently, it is better to specify which measurement you mean.
How do the five FICO Score categories compare?
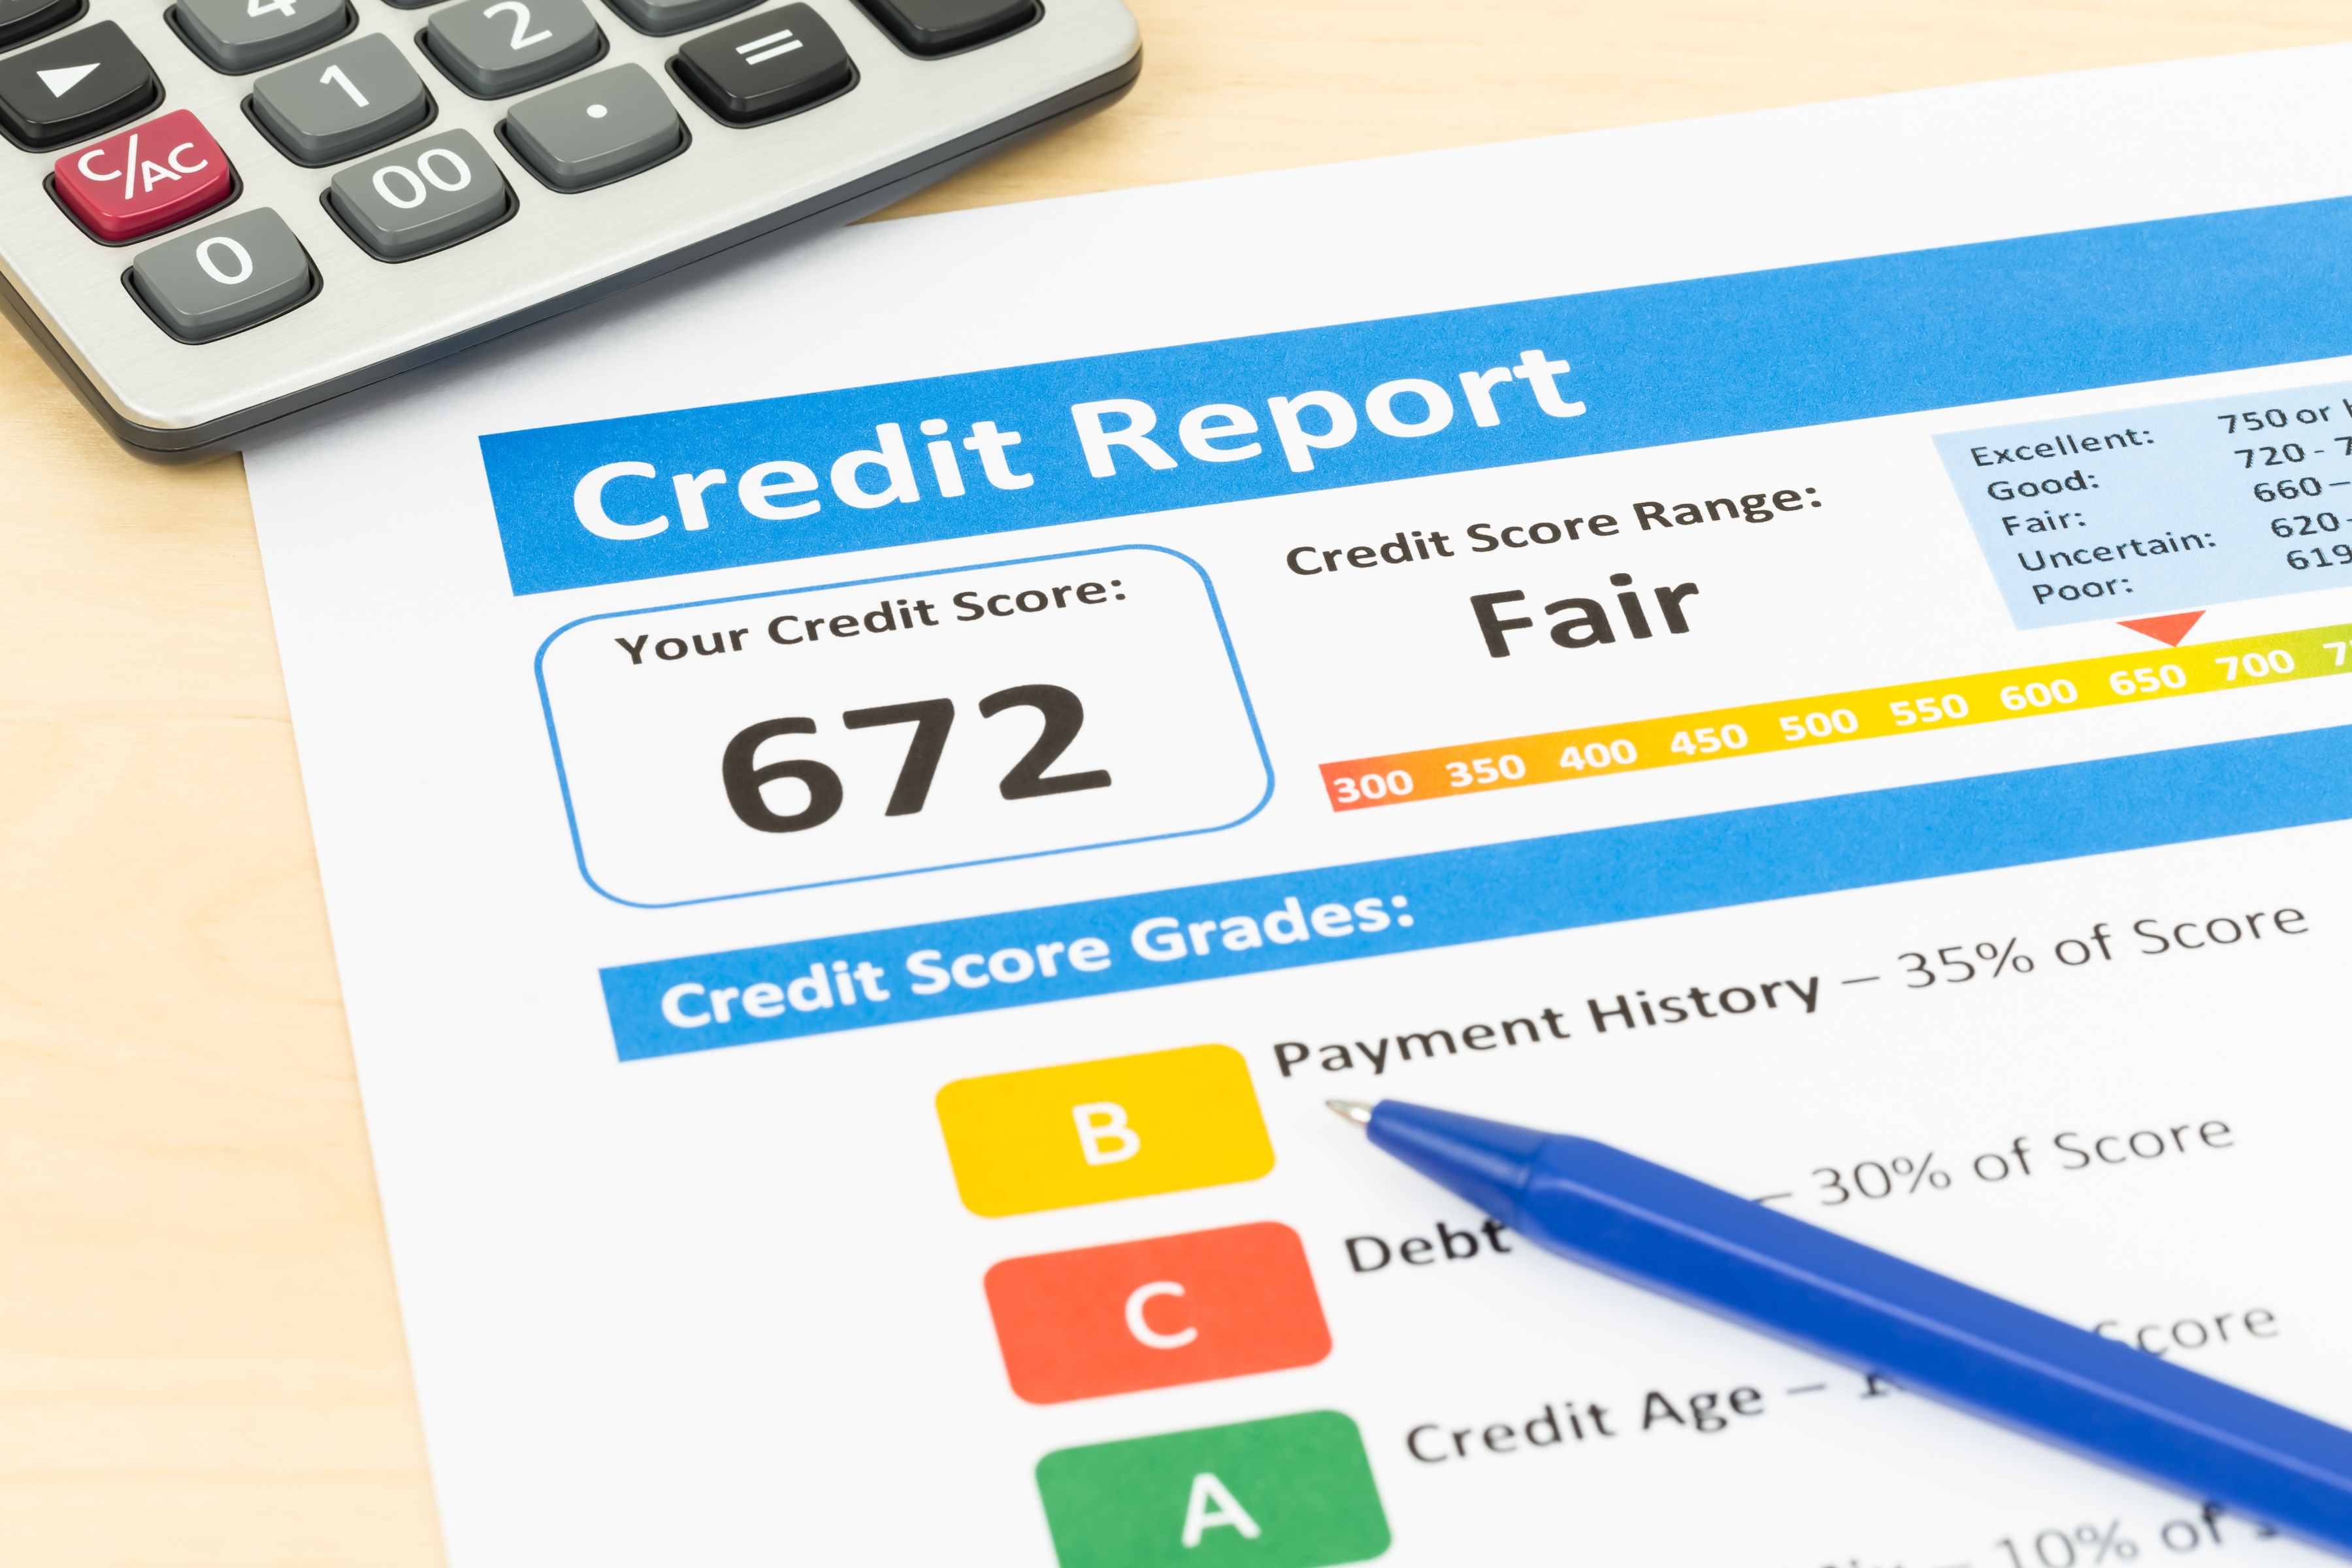
FICO groups the information in your credit reports into five categories. Their general weights are:
- Payment history: 35%
- Amounts owed: 30%
- Length of credit history: 15%
- New credit: 10%
- Credit mix: 10%

These percentages are general guidelines. FICO explains that the importance of each category can vary depending on the information in a person’s credit report.
Read more >> What Is a FICO Score?
Why does length of credit history matter?
A longer record gives scoring models more information about how you have handled credit. In general, a longer credit history can benefit a FICO Score, particularly when the accounts show consistent, on-time payments.
However, a long history is not required for a good score. Someone with a relatively short history may still have a strong FICO Score if the rest of the credit report contains positive information.
Length of history also overlaps with decisions about new accounts. Opening a new account reduces the age of your newest account and usually lowers your average account age. Applying for or opening several accounts within a short period may also affect the separate new-credit category.
That does not mean every new account is harmful. The effect depends on the rest of your credit file, and an account that you manage responsibly can become part of a longer positive history over time.
How is average account age calculated?
To estimate your average account age, add the ages of the accounts appearing on your credit report and divide the total by the number of accounts.
Suppose your report shows six credit cards with these approximate ages:
- Credit Card 1: 20 years
- Credit Card 2: 15 years
- Credit Card 3: 2 years
- Credit Card 4: 1 year
- Credit Card 5: 1 year
- Credit Card 6: 1 year
The oldest account is 20 years old. The six account ages add up to 40 years, so their average age is about 6.7 years, or approximately 6 years and 8 months.
This example shows why the oldest-account age does not tell the whole story. Several recently opened accounts can lower the average even when one or two accounts have been open for many years. The precise calculation used by a scoring model may vary, so a hand calculation is only an estimate.
Does closing an old account shorten your credit history?
Not necessarily right away. A closed account in good standing can generally remain on your credit report for up to 10 years and may continue contributing to the age of your credit file while it appears there. Once the account is removed, it will no longer be part of the information available to a scoring model.
Closing a credit card can have a more immediate effect on credit utilization if losing its credit limit causes your overall utilization rate to rise. That is separate from length of credit history.
Keeping an older card open may be useful when it has no annual fee and you can monitor it safely. But you should not keep an account solely for its age if it is expensive, difficult to manage, or vulnerable to unauthorized use.
How can you build a longer credit history?
You cannot make existing accounts older overnight. You can, however, give your credit history time to develop while building positive information:
- Make every required payment on time.
- Apply for new credit selectively instead of opening several accounts you do not need.
- Keep older accounts in good standing when they remain useful and affordable.
- Review your credit reports to make sure account-opening dates and statuses are accurate.
- Avoid closing an account based only on the assumption that it will disappear immediately.
If you do not yet have a FICO Score, two of FICO’s minimum scoring requirements are at least one account that has been open for six months and at least one account reported to the credit bureau within the past six months. A single account may satisfy both requirements.
Read more >> Why On-Time Payments Matter When Building Credit
Bottom line
Length of credit history is more than the age of your oldest account. FICO may consider your oldest and newest accounts, your average account age, the ages of particular account types, and recent account use.
Time is the main ingredient, but it is not the only one. Consistent payments, manageable balances, and selective credit applications can help you build a stronger overall credit profile while your accounts age.
Kikoff’s Credit Account reports your on-time payments to all three credit bureaus, with no hard credit check to sign up.
Frequently Asked Questions
Disclaimer: The information provided in this blog post is meant for informational purposes only and does not constitute financial advice.