

If you are shopping for a higher-priced home, you may need a mortgage that is larger than the conforming loan limit in your area. That type of financing is commonly called a jumbo loan.
Whether a mortgage is jumbo depends on the loan amount, not simply the home’s purchase price. The limit also varies by location and the number of units in the property. Here is how jumbo loans work, what lenders may review, and how to compare your options.
What is a jumbo loan?
A jumbo loan is a mortgage that exceeds the conforming loan limit for the property’s county and unit count. The Federal Housing Finance Agency (FHFA) sets these limits each year for mortgages that Fannie Mae and Freddie Mac may acquire.
A loan within the applicable limit may be conforming if it also meets the other purchase requirements set by Fannie Mae or Freddie Mac. A jumbo loan is nonconforming because its size exceeds that limit.
Jumbo and conventional are not opposites. A conventional mortgage is not part of a federal government loan program such as FHA, VA, or USDA financing. Both conforming and jumbo loans can be conventional loans.
What are the jumbo loan limits for 2026?
For a one-unit property in most of the United States, the 2026 baseline conforming loan limit is $832,750. A mortgage above that amount is generally considered jumbo in a baseline-limit county.
The one-unit ceiling in designated high-cost areas is $1,249,125. Alaska, Hawaii, Guam, and the U.S. Virgin Islands follow special statutory limits. In those areas, the 2026 one-unit baseline is $1,249,125 and the high-cost ceiling is $1,873,675.
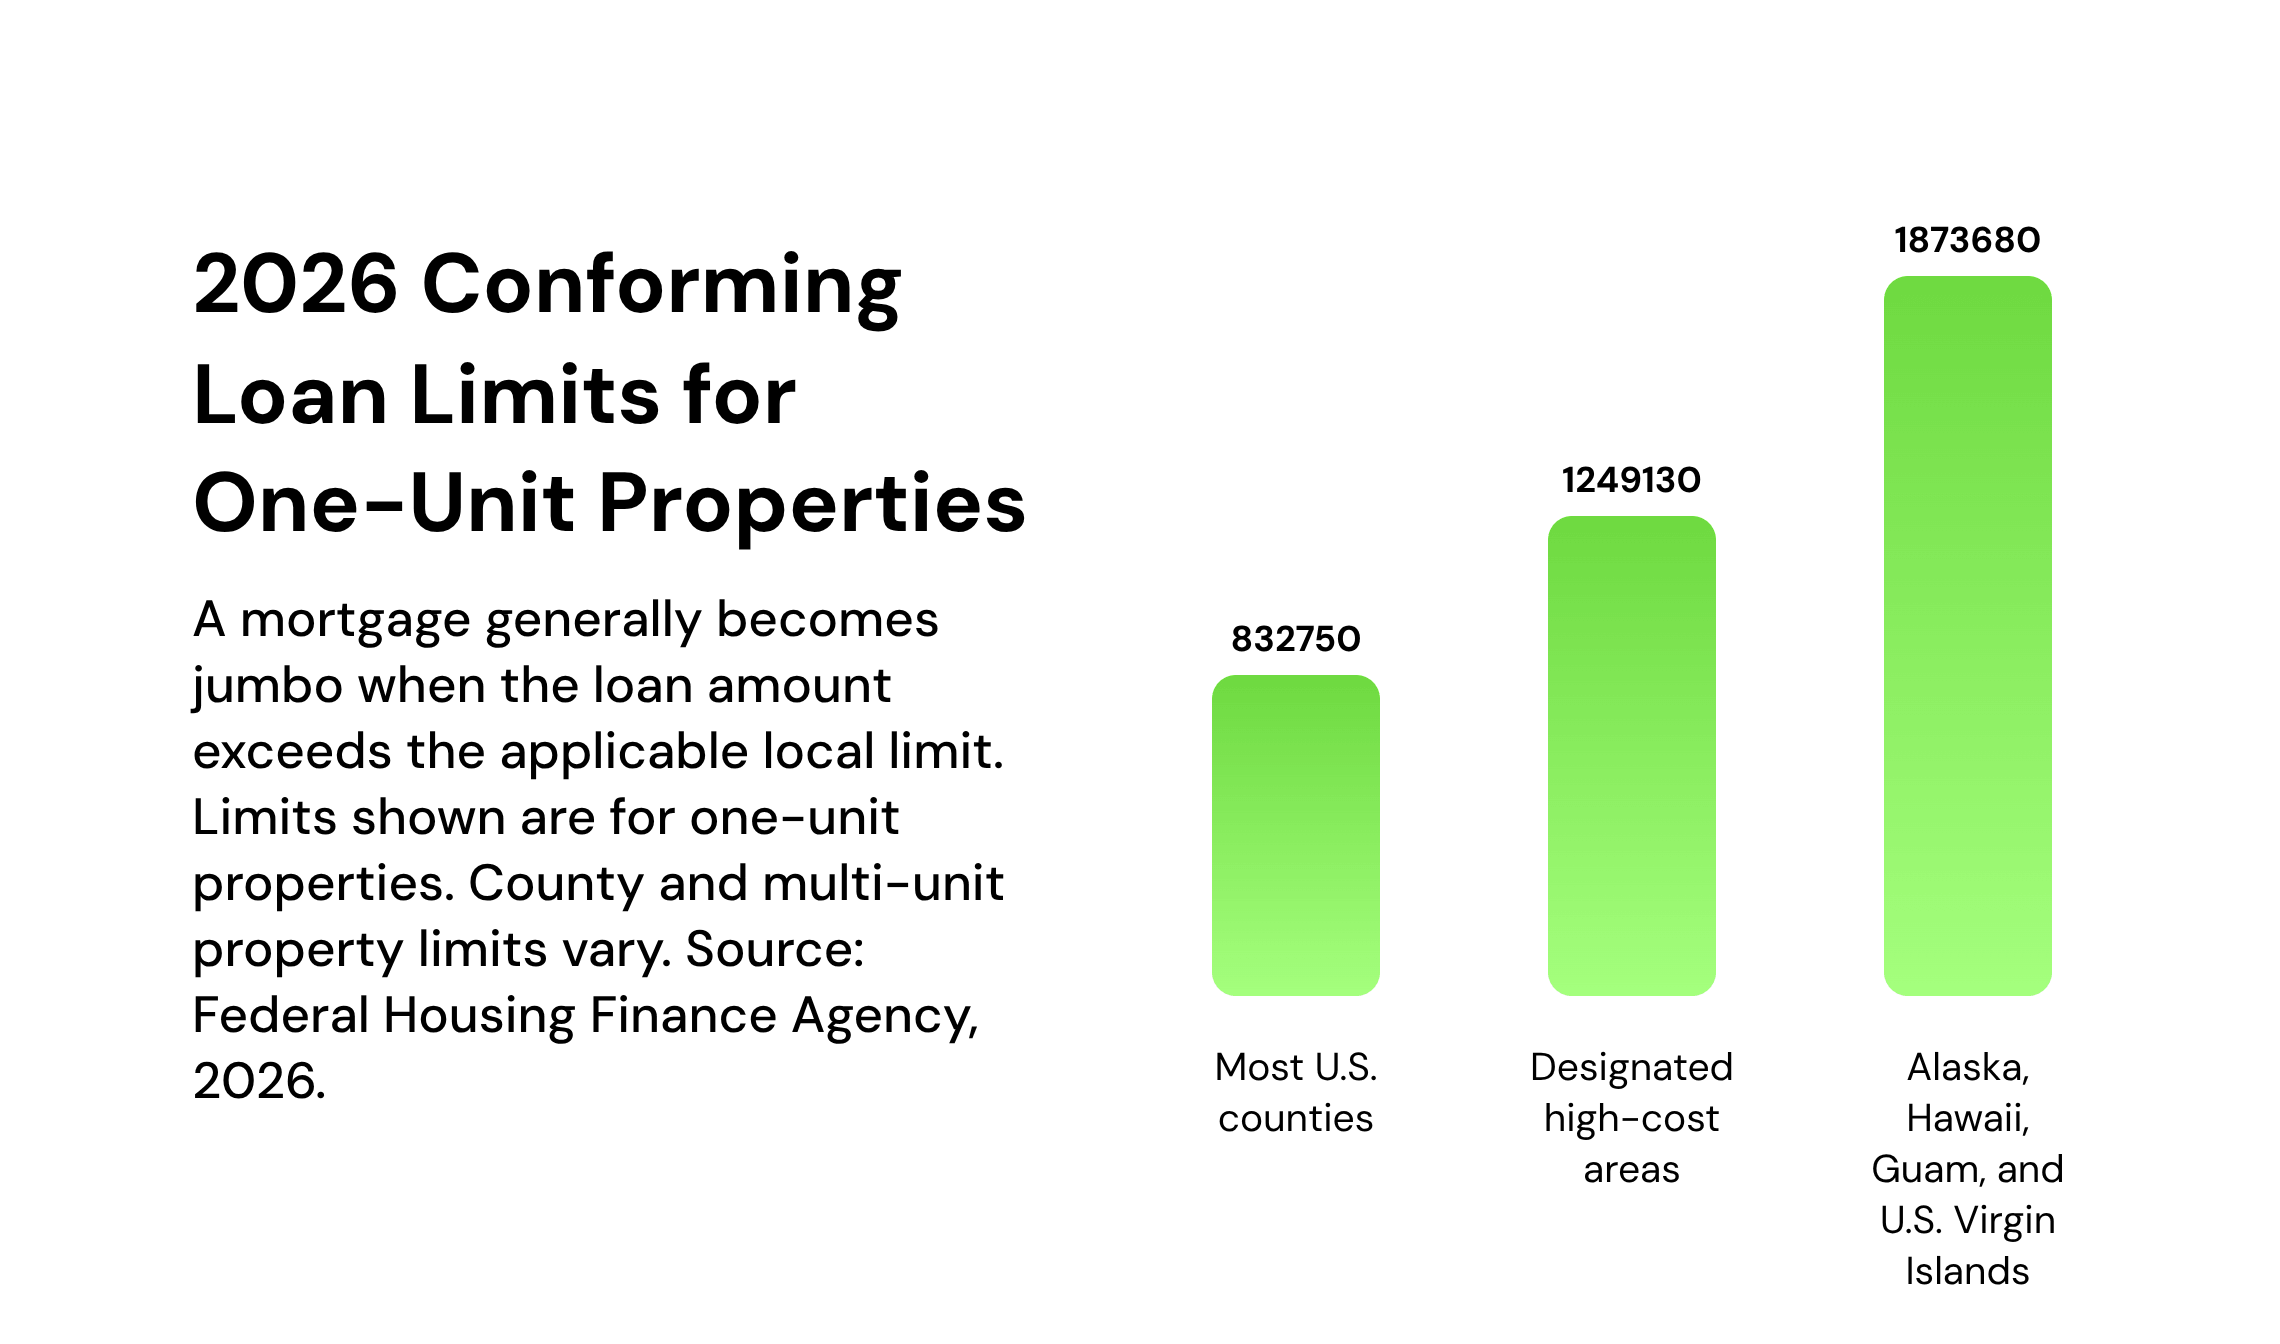
Limits are higher for properties with two to four units and can vary by county. Check the FHFA’s 2026 county loan limit list for the property you are considering.
The purchase price alone does not determine whether you need a jumbo loan. For example, if a home costs $900,000 and you make a $100,000 down payment, the planned loan amount is $800,000. That amount is below the 2026 one-unit baseline limit, so it would not be jumbo based on size in a baseline-limit county.
Quick check: Subtract your planned down payment from the purchase price, then compare the resulting loan amount with the current limit for the property’s county and unit count.
Jumbo loans vs. conforming loans
The main distinction is whether the mortgage is eligible for purchase by Fannie Mae or Freddie Mac. A conforming loan must fall within the applicable limit and meet other program requirements. A jumbo loan exceeds the applicable limit, so the lender cannot sell it to those enterprises as a conforming mortgage.
Because lenders and investors set their own jumbo loan criteria, requirements can vary considerably. According to the Consumer Financial Protection Bureau (CFPB), jumbo loans generally require strong credit and a larger down payment, but there is no single qualification standard that applies to every lender.
Jumbo mortgage rates are not automatically higher than conforming rates. Pricing can shift with market conditions and depends on the lender, loan structure, property, and borrower profile. Comparing actual Loan Estimates is more useful than assuming one loan category will always have a lower rate.
Read more >> What Is Mortgage Amortization?
What do lenders review for a jumbo loan?
Each lender sets its own underwriting standards. Rather than relying on a universal credit score, down payment, debt-to-income ratio, or reserve requirement, ask prospective lenders for the criteria that apply to your loan amount and property type.
Lenders commonly review:
- Credit history and credit scores: Your record of managing debt and making payments may affect eligibility and pricing.
- Income and employment: The lender will generally verify that your income is stable and sufficient for the proposed payment.
- Debt-to-income ratio: Your DTI compares your monthly debt obligations with your gross monthly income. Maximum ratios vary by lender and application.
- Down payment and loan-to-value ratio: A larger down payment reduces the amount borrowed and the lender’s exposure, but the required amount varies.
- Cash reserves: A lender may require liquid assets remaining after closing. Reserve requirements are often expressed as a certain number of months of housing payments, but there is no universal jumbo-loan minimum.
- Property and appraisal: Higher-value or unusual properties may require additional valuation review or more than one appraisal.
Federal ability-to-repay rules generally require mortgage lenders to make a reasonable, good-faith determination that a borrower can repay the loan. The CFPB explains the ability-to-repay and Qualified Mortgage rules in more detail.
Read more >> How to Get a Home Loan With Bad Credit
Pros and cons of a jumbo loan
Potential advantages include:
- Financing a loan amount above the local conforming limit
- Avoiding a larger down payment made solely to keep the mortgage within the limit
- Accessing financing for certain higher-priced or specialized properties
- Potentially competitive rates for well-qualified applicants, depending on current lender pricing
Potential drawbacks include:
- Stricter or more lender-specific underwriting
- Potentially larger down payment and reserve requirements
- A larger loan balance and monthly payment
- Rates and fees that may differ substantially among lenders
- Additional appraisal or property-review requirements in some cases
A jumbo loan is not necessarily the only way to buy a home priced above the conforming limit. A larger down payment may reduce the loan amount enough to fit within the applicable limit. The better option depends on how much cash you want to use at closing, the offers available to you, and your broader financial plan.
How to compare jumbo mortgage offers
Start by confirming the FHFA limit for the property’s county and unit count. Then calculate the amount you expect to borrow after your down payment.
If the loan will be jumbo, request offers from several lenders. The CFPB recommends contacting at least three lenders so you can compare your options.
Review each official Loan Estimate side by side, including:
- Interest rate and annual percentage rate (APR)
- Monthly principal and interest
- Points, origination charges, and lender credits
- Estimated taxes, insurance, and total monthly payment
- Cash needed to close
- Whether the rate is locked and how long the lock lasts
- Any prepayment penalty or balloon payment
The CFPB’s Loan Estimate comparison guide can help you identify differences in upfront costs and five-year borrowing costs. Compare offers issued for the same loan amount, term, rate type, down payment, and lock period whenever possible.
Bottom line
A mortgage is jumbo when the amount borrowed exceeds the conforming loan limit for the property’s location and unit count. For 2026, the one-unit baseline is $832,750 in most of the country, but higher limits apply in designated areas. Because jumbo qualification rules and pricing vary by lender, confirm the correct limit and compare several Loan Estimates before deciding.
If strengthening your credit history is one part of preparing for a future mortgage, Kikoff’s Credit Account reports your on-time payments to all three major credit bureaus, with no hard credit check to join. It can help you add positive payment history, while mortgage approval and terms remain subject to the lender’s requirements.
Frequently Asked Questions
Article Sources
Disclaimer: The information provided in this blog post is meant for informational purposes only and does not constitute financial advice.