With a 593 credit score, you can likely get approved for a secured credit card, an auto loan, or a personal loan from a credit union. You may also qualify for an FHA loan with 3.5% down. You'll pay more than borrowers with good credit, because your score sets your rate. The nearest cutoff is 601, 8 points away, where Experian's near prime auto tier starts.
Is 593 a poor credit score?
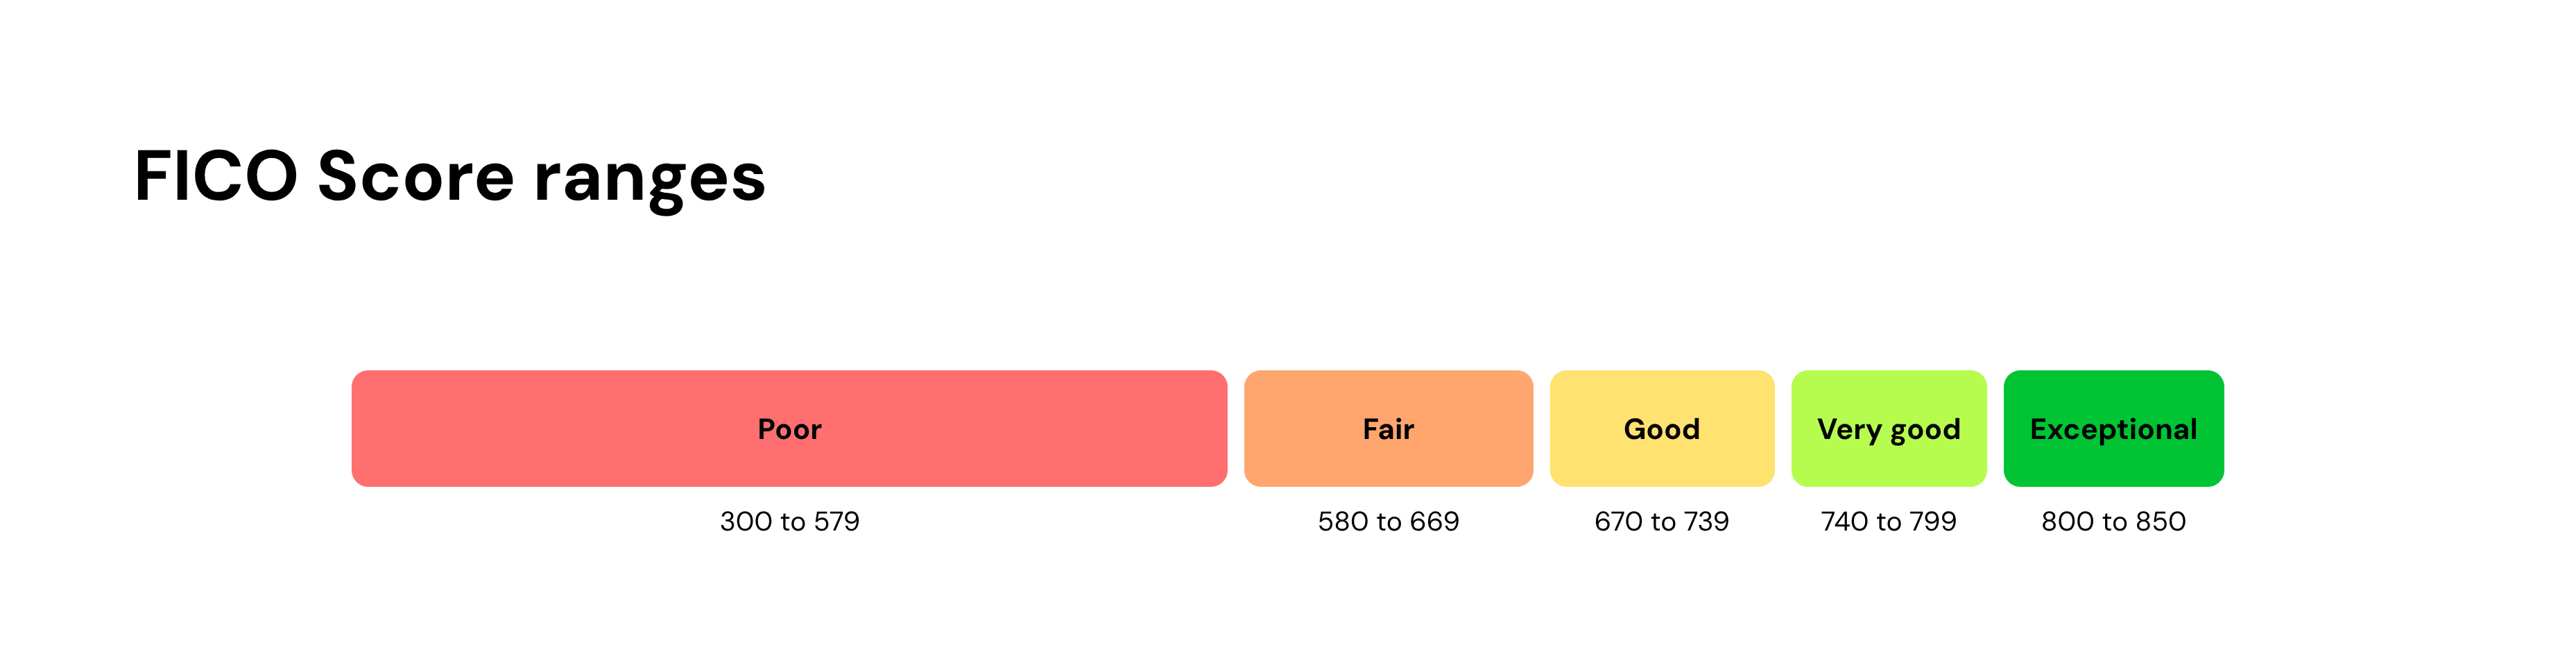
No. FICO's fair range runs from 580 to 669, so 593 sits near the bottom of it, 13 points above where fair credit starts at 580. At 670, you'd move into good credit.
A score in this range usually means your credit report shows one or more of these issues:
- A late payment. A payment 30 days or more late stays on your report for seven years. Its effect on your score shrinks as it ages, especially when newer on-time payments build behind it.
- High card balances. Using a large share of your available credit lowers your score. Unlike a late payment, this changes as soon as your balances come down.
- A short or thin credit history. A thin credit file, meaning a report with only a few accounts or accounts that haven't been open long, gives scoring models less to go on.
Many lenders will work with a 593 score. What changes is the terms, including higher rates, lower limits, bigger deposits, and, in some states, higher car insurance premiums than borrowers with good credit get.
Read more >> What Can You Get Approved For With a 620 Credit Score?
What can you get approved for with a 593 credit score?
More doors are open at 593 than in the poor range. Approval isn't automatic, though, and prices still run high.
Credit cards
Unsecured cards designed for fair credit are possible at 593, though some issuers want a higher score within the range. Expect a low limit and a higher APR than cards for good credit. Before applying, check whether the issuer offers prequalification, which uses a soft credit check that doesn't harm your credit.
A secured credit card is your most likely approval. You put down a refundable deposit that usually becomes your credit limit. A $500 deposit, for example, gets you a $500 limit. You generally get it back if you close the account in good standing or are graduated to an unsecured card with steady on-time payments.
Personal loans
A personal loan is harder to get at 593 than at a higher fair score, but it's a realistic option. Expect a smaller amount and a higher rate than a borrower with good credit would get.
Start with a credit union if you belong to one or can join. Federal credit unions can't charge more than 18% on most loans. Some also offer payday alternative loans (PALs) of up to $2,000, repaid over one to 12 months. Application fees are capped at $20, and rates are capped at 28%.
Online lenders and banks that work with fair credit are another option. Compare offers using prequalification, so only the lender you choose runs a hard credit check. Any of these is cheaper than a payday loan, where a typical $15 fee per $100 borrowed works out to an APR of almost 400%.
Auto loans
Approval for a car loan at 593 is often easier than approval for a personal loan with the same score. That's because your car is the collateral: If you stop paying, the lender can take it back and sell it to cover the loan. That lowers the lender's risk, but it also means falling behind puts your car at risk.
A 593 score falls in Experian's subprime tier (501 to 600). Your credit score plays a major role in the interest rate you're offered on a car loan. On a $20,000, 60-month new car loan at average rates, a subprime borrower would pay about $5,300 more in interest than a super prime borrower, and about $4,300 more than a prime borrower. Experian sorts these tiers by VantageScore 4.0, so your FICO score may place you a little differently.
You're close to the next tier. Experian's near prime tier starts at 601, 8 points above your score.
Use an auto loan calculator to check payment amounts before you sign.
Mortgages
With a 593 credit score, an FHA loan is the most realistic mortgage. Costs depend on the type:
- FHA loans. Borrowers with scores of 580 or higher can qualify with 3.5% down. On a $250,000 home, that's $8,750 up front. At 593, you're 13 points above that cutoff. Below 580, the minimum rises to 10% down, or $25,000 on the same home. Each lender can set higher minimums.
- Conventional loans. Fannie Mae no longer sets a minimum score for loans run through its automated system, but lenders still set their own minimums. Fannie Mae also charges lenders an upfront fee on the loans it buys, based on your score and down payment. At 20% down, the fee for scores of 639 and below is 2.75% of the loan amount, compared with 0.375% at 780 or higher. On a $200,000 loan, that's $5,500 versus $750, and you'd pay it through a higher rate or more cash at closing. The fee drops to 2.25% at 640, or about $1,000 less on a $200,000 loan.
- USDA loans. These are for homes in eligible rural and suburban areas with income limits. USDA doesn't set a minimum score, but lenders typically look for 620 to 640. At 593, you're below that range, so ask each lender about its own minimum.
A lender can show you an FHA and a conventional quote side by side. Our mortgage calculator can help you compare the monthly payments.
What interest rates can you expect with a 593 credit score?
Expect rates toward the high end of the range a lender offers. The average rate was 22.15% for card accounts charging interest and 11.86% for 24-month bank personal loans, according to the Federal Reserve. Those averages cover borrowers at every credit level. With a 593 score, your offers are likely to come in above them.
The rate applies to the whole balance, so even a few points add up. If you can wait to borrow, 8 points would move you into Experian's near prime tier for auto loans.
5 ways to raise a 593 credit score
- Check your credit reports for errors. You can get all three for free every week at AnnualCreditReport.com. If something is wrong, like an account that isn't yours or a late payment you made on time, dispute it with the bureau. Disputing is free.
- Bring any past-due accounts current, if you can. If you're juggling more than one, the National Foundation for Credit Counseling (NFCC) can connect you to free or low-cost counseling at 800-388-2227.
- Pay every bill on time. Payment history is the biggest factor in your score, making up 35% of a FICO Score.
- Pay down card balances. Using less of your available credit can raise your score as soon as your issuer reports the lower balance, which makes it a fast way to close a small gap.
- Apply only when you need to. Each application can add a hard inquiry, which takes a few points off for about a year. Prequalify first where you can.
If your report is thin on accounts, adding one helps. A Kikoff Credit Account reports your payments to all three bureaus.
Read more >> How to Build Credit
Bottom line
At 593, you're in fair credit, and many lenders will approve you for cards, car loans, and FHA mortgages. Your score still sets the price you pay. Just 8 more points would put you in Experian's near prime auto tier, and staying at 580 or higher keeps your FHA down payment at 3.5%. Good credit in FICO's ranges is 77 points away.
Kikoff brings credit building, bill and rent reporting, AI-powered disputes, credit monitoring, and debt negotiation into one place. Sign up with no credit check. Plans start at $5 a month.
Frequently Asked Questions
Article Sources
Disclaimer: The information provided in this blog post is meant for informational purposes only and does not constitute financial advice.