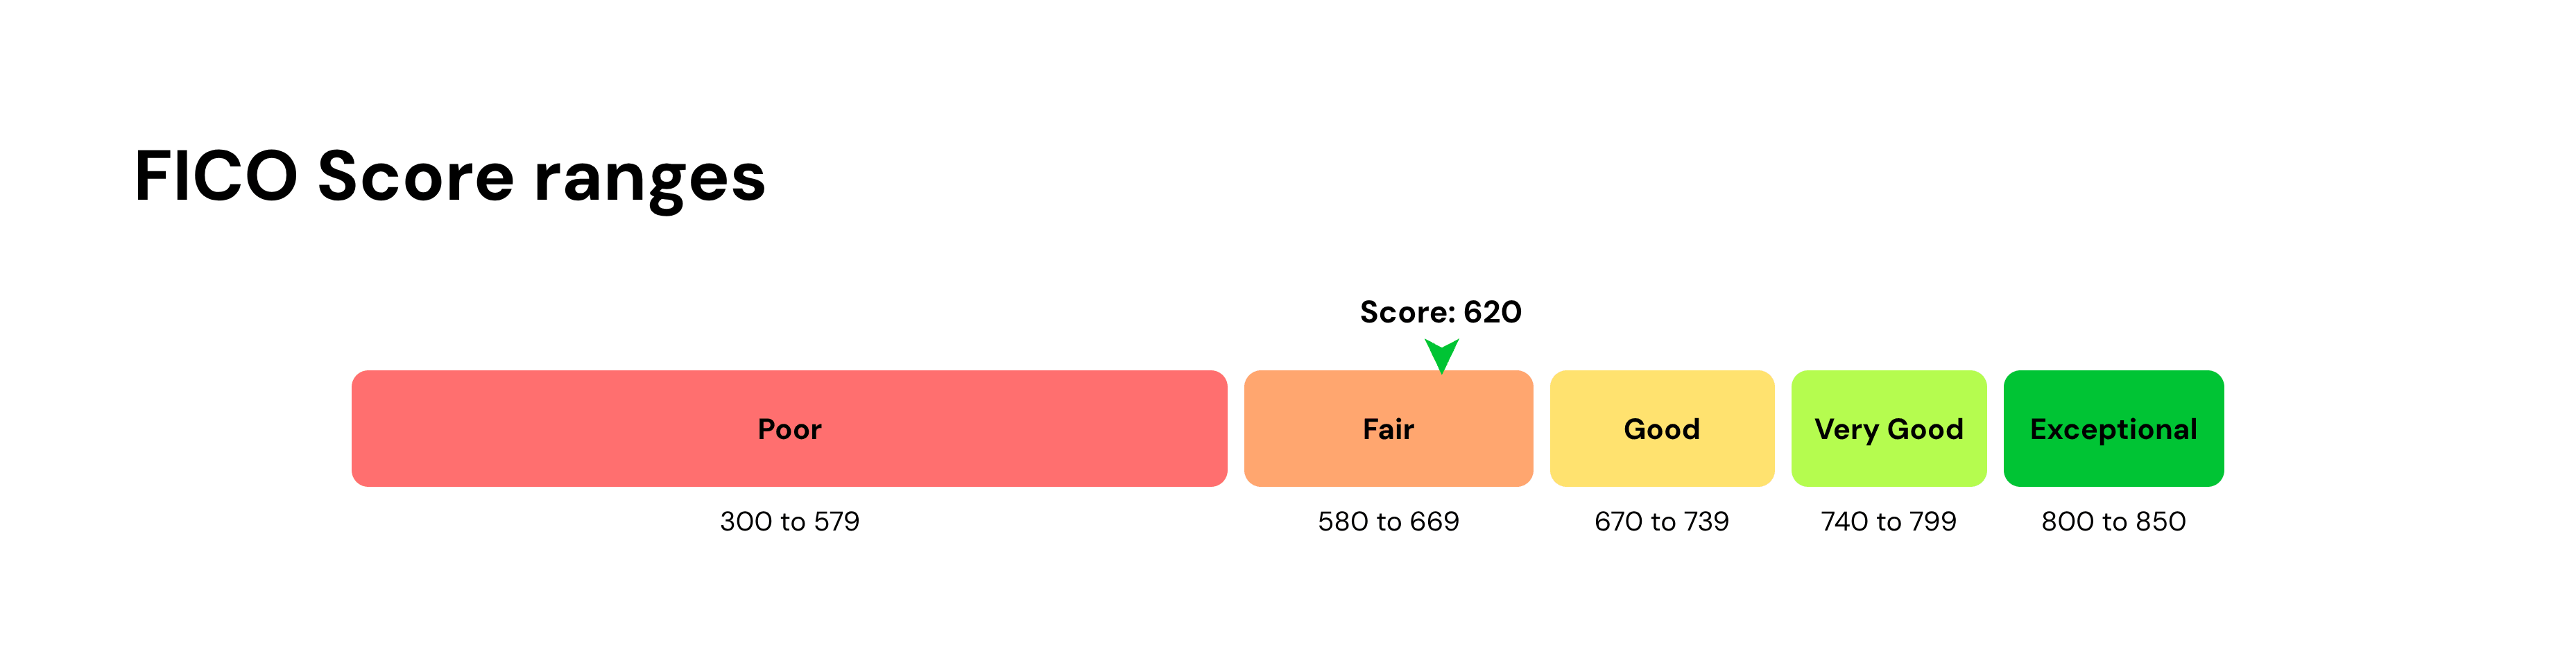
With a 620 credit score, you can likely get approved for an unsecured credit card, a personal loan, an auto loan, or a mortgage. That includes an FHA loan with 3.5% down. You'll pay more than borrowers with good credit, because your score sets your rate. At 620, you're 41 points from prime auto rates and 50 points from good credit.
Is 620 a poor credit score?
No. FICO's fair range runs from 580 to 669, so 620 sits in the lower half of it. At 670, you'd move into good credit.
A score in this range usually means your credit report shows one or more of these issues:
- An older late payment. A payment 30 days or more late stays on your report for seven years. Its effect on your score shrinks as it ages, especially when newer on-time payments build behind it.
- High card balances. Using a large share of your available credit lowers your score. Unlike a late payment, this changes as soon as your balances come down.
- A short or thin credit history. A thin credit file, meaning a report with only a few accounts or accounts that haven't been open long, gives scoring models less to go on.
Many lenders will work with a 620 score. What changes is the terms, including higher rates, lower limits, and, in some states, higher car insurance premiums than borrowers with good credit get.
Read more >> What Can You Get Approved For With a 665 Credit Score?
What can you get approved for with a 620 credit score?
At 620, approval opens up across financial products, but prices can still run high.
Credit cards
Unsecured cards designed for fair credit are realistic with a 620 credit score. Expect a modest limit and a higher APR than cards for good credit. Before applying, check whether the issuer offers prequalification, which uses a soft credit check that doesn't harm your credit.
If you're turned down, a secured credit card is a reliable option. With these cards, you put down a refundable deposit that usually becomes your credit limit. You generally get it back if you close the account in good standing or are graduated to an unsecured card with steady on-time payments.
Personal loans
A personal loan is realistic at 620, though the rate can be higher than a borrower with good credit would get. Include credit unions when comparing lenders: Federal credit unions can't charge more than 18% on most loans.
Online lenders and banks that work with fair credit are another option. Compare offers using prequalification, so only the lender you choose runs a hard credit check.
Auto loans
Approval for a car loan at 620 is usually straightforward, because the loan is secured by the vehicle you’re buying. If you stop paying, the lender can take it back and sell it. That lowers the lender's risk, but it also means falling behind puts your car at risk.
A 620 score falls in Experian's near prime tier (601 to 660). Your credit score plays a major role in the interest rates you're offered on a car loan. On a $20,000, 60-month new car loan at average rates, a near-prime borrower would pay about $3,000 more in interest than a super prime borrower, and about $2,000 more than a prime borrower. Experian sorts these tiers by VantageScore 4.0, so your FICO score may place you a little differently.
Use an auto loan calculator to check the monthly payment before you sign.
Mortgages
With a 620 credit score, mortgages are within reach, with costs depending on the type:
- FHA loans. Borrowers with scores of 580 or higher can qualify with 3.5% down. On a $250,000 home, that's $8,750 up front. Each lender can set higher minimums.
- Conventional loans. Fannie Mae no longer sets a minimum score for loans run through its automated system. It does charge lenders an upfront fee on the loans it buys, based on your score and down payment. At 20% down, the fee for scores of 639 and below is 2.75% of the loan amount, compared with 0.375% at 780 or higher. On a $200K loan, that's $5,500 versus $750, and you'd pay it through a higher rate or more cash at closing.
- USDA loans. These are for homes in eligible rural and suburban areas with income limits. USDA doesn't set a minimum score, but lenders typically look for 620 to 640. At 620, you're at the edge.
A lender can show you an FHA and a conventional quote side by side. Our mortgage calculator can help you compare the monthly payments.
What interest rates can you expect with a 620 credit score?
Expect rates above what borrowers with good credit get. The average credit card charges interest of 22.15%, according to the Federal Reserve, while a 24-month personal loan from a bank currently runs 11.86%. Those averages cover borrowers at every credit level. With a 620 score, your offers may come in above them.
The rate applies to the whole balance, so a few points add up. If you can wait to borrow, about 40 points would move you into the prime tier for auto loans.
5 ways to raise a 620 credit score
- Check your credit reports for errors. You can get all three for free every week at AnnualCreditReport.com. If something is wrong, like an account that isn't yours or a late payment you made on time, dispute it with the bureau. Disputing is free.
- Bring any past-due accounts current, if you can. If you're juggling more than one, the National Foundation for Credit Counseling (NFCC) can connect you to free or low-cost counseling at 800-388-2227.
- Pay every bill on time. Payment history is the biggest factor in your score, making up 35% of a FICO Score.
- Pay down card balances. Using less of your available credit can raise your score as soon as your issuer reports the lower balance.
- Apply only when you need to. Each application can add a hard inquiry, which takes a few points off for about a year. Prequalify first where you can.
If your report is thin on accounts, adding one helps. A Kikoff Credit Account reports your payments to all three bureaus.
Read more >> How to Build Credit
Bottom line
At 620, most lenders will approve you for a range of products. What your score decides now is the price. About 40 more points moves you into prime auto rates, and 50 gets you to good credit for every application after that.
Kikoff brings credit building, bill and rent reporting, AI-powered disputes, credit monitoring, and debt negotiation into one place. Sign up with no credit check. Plans start at $5 a month.
Frequently Asked Questions
Article Sources
Disclaimer: The information provided in this blog post is meant for informational purposes only and does not constitute financial advice.