


With a 524 credit score, you can likely get approved for a secured credit card, an auto loan, or a small loan from a credit union. You may even qualify for an FHA mortgage if you can put 10% down. Unsecured cards and most personal loans are harder to get. You'll pay more for all of these, because your score sets your interest rate.
The nearest milestone is 580, 56 points away. That's where fair credit starts and the FHA down payment drops to 3.5%.
Is 524 a poor credit score?
Yes. A score of 524 is within FICO's lowest range, in the upper half of it. Fair credit starts at 580.
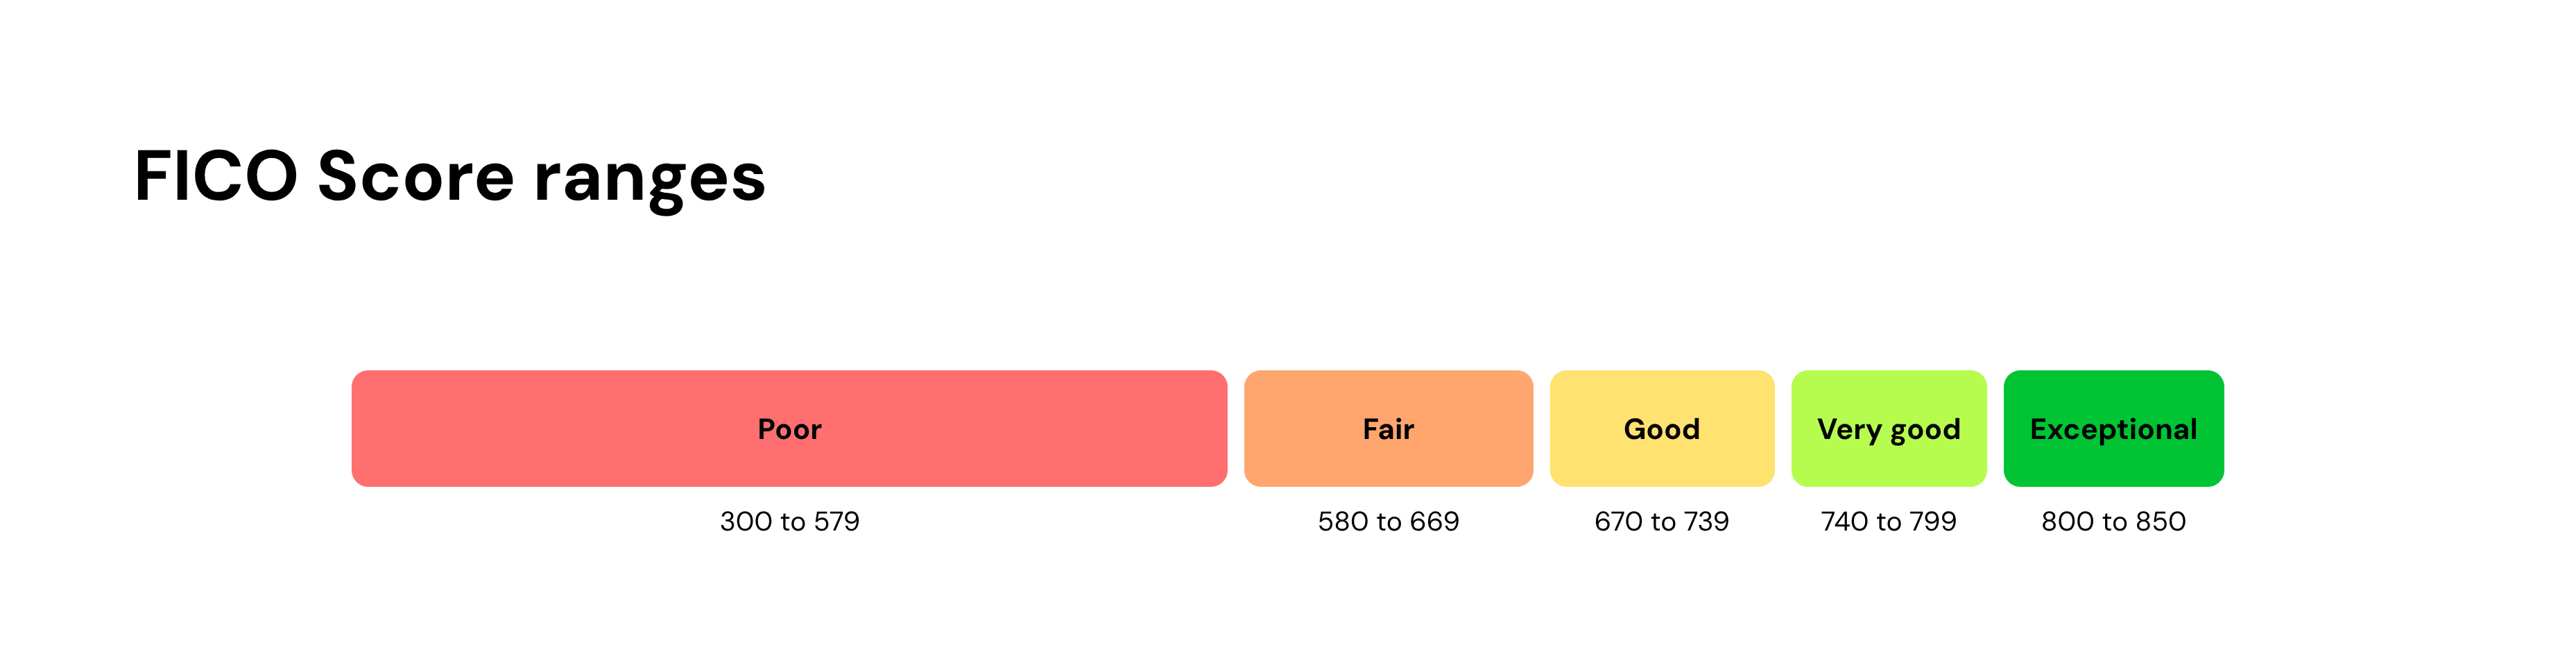
A score in this range usually means your credit report includes negative marks like:
- Missed payments. A payment 30 days late gets reported and stays on your report for seven years. Its effect on your score shrinks as it ages.
- Accounts in collections. This is a debt handed off to a collection agency, often a medical bill or an old card balance. A collection also stays for seven years, counted from the original delinquency.
- High card balances. Using a large share of your available credit lowers your score. Unlike a late payment, this changes as soon as your balances come down.
Lenders read that as a high risk you won't repay. So approvals are harder, and when one comes through, the terms reflect the risk. Expect higher rates, bigger deposits, larger down payments, and, in some states, higher insurance premiums.
Read more >> What Can You Get Approved For With a 560 Credit Score?
What can you get approved for with a 524 credit score?
At 524, you're past the FHA floor of 500, but most approvals still come with conditions. Knowing which products are reachable can save you an application.
Credit cards
Most unsecured cards are hard to get with a 524 score. Before applying for one, check whether the issuer offers prequalification. It uses a soft credit check, so it won't add a hard inquiry to your report.
A secured credit card is your most likely approval. You put down a refundable deposit that typically becomes your credit line. A $500 deposit, for example, gets you a $500 limit. The issuer holds the deposit while the account is open and keeps it if you don't pay.
You generally get the deposit back when you close the account in good standing, or when the issuer graduates you to an unsecured card after steady on-time payments.
Some subprime unsecured cards accept scores in the 500s, but expect a low limit, a high rate, and fees. If you're enrolled in college, a student card is another option. Student cards are designed for people new to credit, so approval at 524 isn't guaranteed.
Personal loans
A personal loan from a bank or online lender is hard to get at 524. If you're approved, expect a small amount, a short term, and a high rate. For example, you might get $500 to repay over six months.
Start with a credit union if you belong to one or can join. Federal credit unions can't charge more than 18% on most loans. Some also offer payday alternative loans (PALs) of up to $2,000, repaid over one to 12 months. Application fees are capped at $20, and rates are capped at 28%.
Online lenders that focus on poor credit are another option, though their rates run higher. Any of these is cheaper than a payday loan, where a typical $15 fee per $100 borrowed works out to an APR of almost 400%.
Auto loans
An auto loan is one of the easier loans to get approved for with a 524 score. That's because your car is the collateral: If you stop paying, the lender can take it back and sell it to cover the loan. That lowers the lender's risk, but it also means falling behind puts your car at risk.
A 524 score falls in Experian's subprime tier (501 to 600). Your credit score plays a major role in the interest rate you're offered on a car loan. On a $20,000, 60-month new car loan at average rates, a subprime borrower would pay about $5,300 more in interest than a super prime borrower, and about $4,300 more than a prime borrower. Experian sorts these tiers by VantageScore 4.0, so your FICO score may place you a little differently.
If banks and credit unions turn you down, buy here, pay here dealers finance cars themselves. They often require weekly or biweekly payments and charge much higher rates than traditional loans.
Use an auto loan calculator to check payment amounts before you sign.
Mortgages
A mortgage is possible at 524, but it's expensive to get into, and not every lender will take it on. FHA loans have the most flexible credit requirements. Borrowers with scores from 500 to 579 can qualify with at least 10% down, though lenders can set their own minimums higher. At 580, the minimum drops to 3.5% down. On a $250,000 home, that's $25,000 down at 524 versus $8,750 at 580.
A conventional mortgage is unlikely. Fannie Mae dropped its 620 minimum for loans run through its automated system in November 2025, but lenders still set their own minimums. USDA loans, for homes in eligible rural and suburban areas with income limits, don't carry a program minimum score either. Lenders typically look for 620 to 640, well above 524.
If you want to buy a home, building your score toward 580 and saving for a down payment work together. Our mortgage calculator can show what 10% down versus 3.5% down looks like in your price range.
What interest rates can you expect with a 524 credit score?
Expect rates near the top of whatever range a lender offers. Card accounts charging interest averaged 22.15%, according to the Federal Reserve, and 24-month personal loans from banks averaged 11.86%. Those averages cover borrowers at every credit level. With a 524 score, your offers are likely to be higher.
The rate applies to the whole balance, so a few points add up. If you can wait to borrow, a 56-point gain to 580 would put you in fair credit and cut the FHA down payment to 3.5%.
5 ways to raise a 524 credit score
- Check your credit reports for errors. You can get all three for free every week at AnnualCreditReport.com. If something is wrong, like an account that isn't yours or a late payment you made on time, dispute it with the bureau. Disputing is free.
- Bring past-due accounts current, if you can. For accounts already in collections, it can be hard to know which to pay first. The National Foundation for Credit Counseling (NFCC) can connect you to free or low-cost counseling at 800-388-2227.
- Pay every current bill on time. Payment history is the biggest factor in your score, making up 35% of a FICO Score.
- Pay down card balances. Using less of your available credit can raise your score as soon as your issuer reports the lower balance. That makes it the fastest factor you can move.
- Apply only when you need to. Each application can add a hard inquiry, which takes a few points off for about a year. Prequalify first where you can.
If your report is thin on positive accounts, adding one helps. A Kikoff Credit Account reports your payments to all three bureaus.
Progress is often slow at first. Late payments and collections lose weight as they age, and each month of on-time payments adds to your record.
Read more >> How to Build Credit
Bottom line
A 524 score still leaves you with options: secured cards, auto loans, credit union PALs, and even an FHA mortgage with 10% down. But your score also sets your price. Reaching 580, 56 points away, moves you into fair credit in FICO's ranges and cuts the FHA down payment to 3.5%.
Kikoff brings credit building, bill and rent reporting, AI-powered disputes, credit monitoring, and debt negotiation into one place. Sign up with no credit check. Plans start at $5 a month.
Frequently Asked Questions
Article Sources
Disclaimer: The information provided in this blog post is meant for informational purposes only and does not constitute financial advice.