



With a 786 credit score, you can likely get approved for premium rewards cards, low-rate personal loans, auto loans, and most mortgages, as long as your income and debts support what you're borrowing. Your score already clears the cutoffs for the top auto and mortgage pricing tiers, though only by a few points. Exceptional credit at 800 is 14 points away, but it changes the label more than the price.
Is 786 a good credit score?
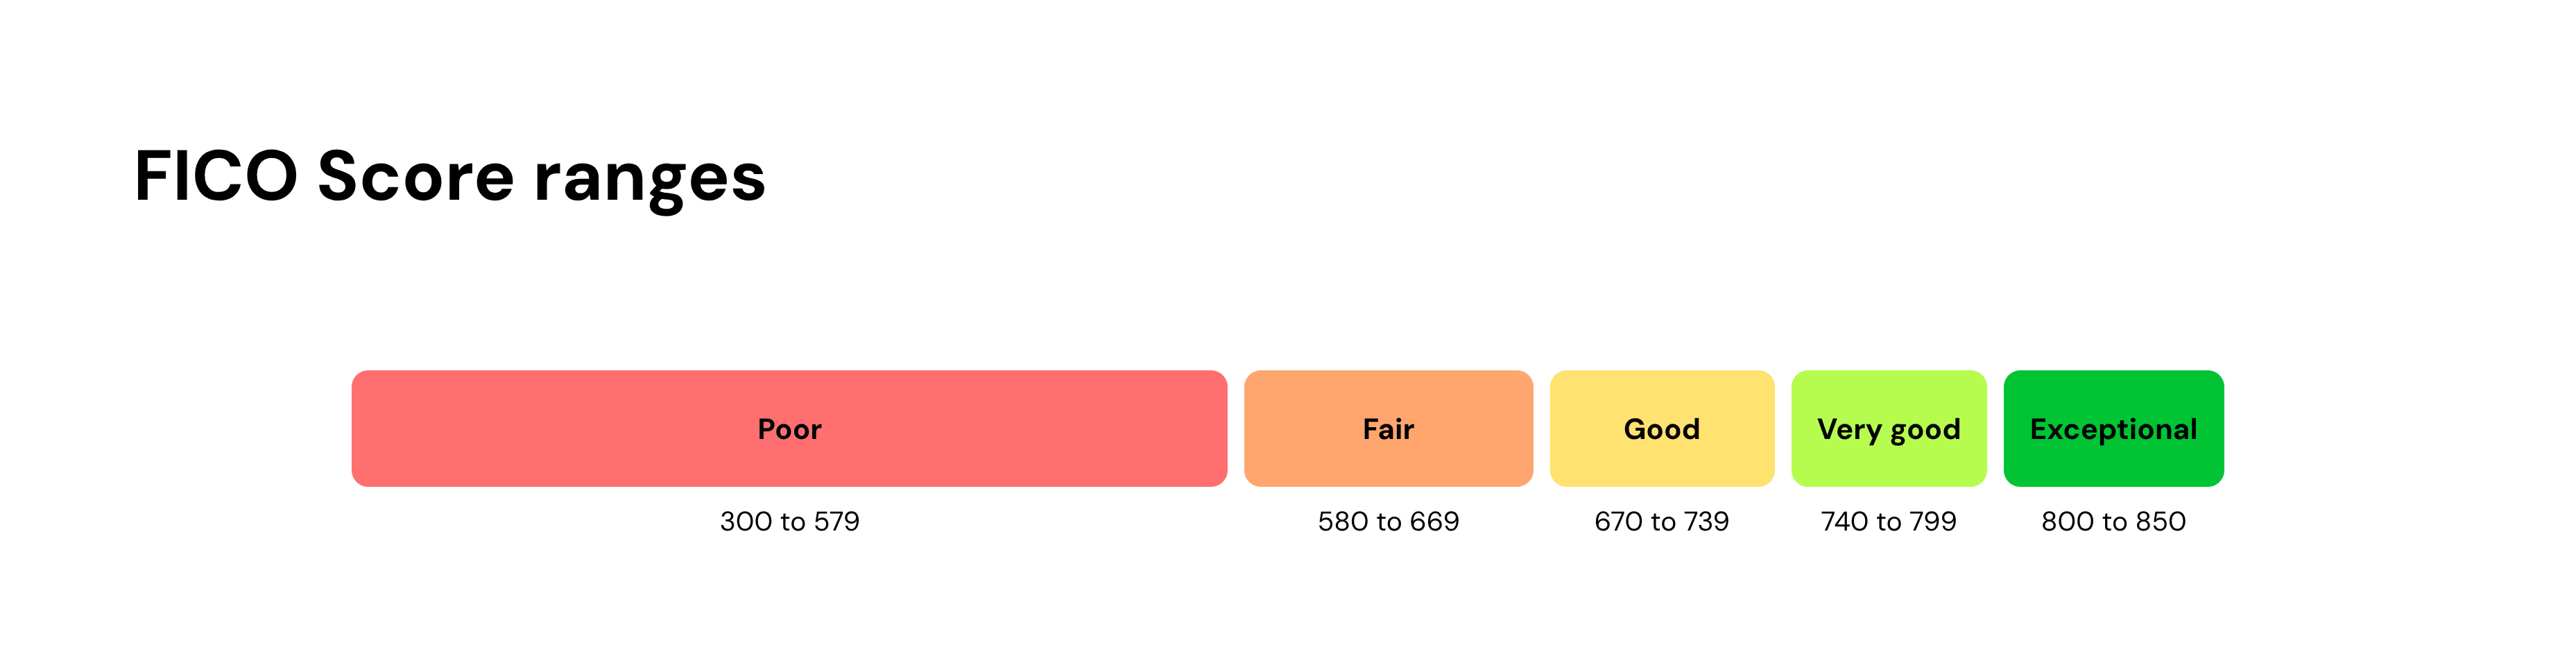
Yes. FICO's very good range runs from 740 to 799, and 786 is in the upper half of it. Exceptional credit starts at 800.
A score this high usually reflects a long run of on-time payments, low reported balances, and few recent applications. At 786, you sit just above the cutoffs that set your price, so the bigger risk is slipping below them. An error on your report or a missed payment can cost more than any further gain would earn you.
Read more >> What Can You Get Approved For With an 825 Credit Score?
What can you get approved for with a 786 credit score?
At 786, credit isn't typically what stands between you and approval. Lenders will look harder at your income, your job history, and your debt-to-income ratio (DTI).
Credit cards
Premium cards with travel rewards, high credit limits, and large sign-up bonuses are realistic at 786. So are long 0% intro APR periods.
Since you'll likely qualify for several, think about how many cards you need and pick those you'll actually use. If you travel, look for airfare and hotel rewards or lounge access. If you're planning a large purchase, a long 0% intro APR period can be worth more than points. It helps only if you pay the balance off before the period ends.
Before applying, check whether the issuer offers prequalification, which uses a soft credit check that doesn't affect your score. A full application triggers a hard inquiry, so only open a new card when it serves a financial goal.
Personal loans
Most personal lenders will approve a 786 if your income and DTI support the loan. Expect offers at or near a lender's lowest advertised interest rates.
The Federal Reserve's average for a 24-month bank personal loan is 11.86%, and a 786 borrower can often get offers below it.
How much you can borrow still depends on your income and existing debt.
Auto loans
At 786, you're in Experian's super prime tier (781+), but only by 5 points. Super prime is the top tier for auto loans, with average rates of 4.41% on new cars and 6.29% on used cars. On a $20,000, 60-month new car loan at average rates, that's about $1,000 less in interest than the prime average. Dropping below 781 would cost you about that much. Experian sorts these tiers by VantageScore 4.0, so your FICO score may place you a little differently.
Manufacturer promotions like 0% financing or cash back offers are within reach. Ask the dealer what score a specific promotion requires. Get preapproved by a bank or credit union first, then compare that rate against the dealer's financing and any promotion. A cash rebate can be worth more than a lower rate.
Use an auto loan calculator to check payment amounts before you sign.
Mortgages
At 786, most mortgage types are open to you, and your score earns Fannie Mae's best pricing, 6 points above the cutoff. Your down payment now matters more than your score.
- Conventional loans. Fannie Mae charges lenders an upfront fee on the loans it buys, based on your score and down payment. For scores of 780 and up, that fee is 0.375% of the loan amount with 20% down and 0% with 25% down or more. On a $200,000 loan, that's $750 versus $0. If your score slipped into the 760 to 779 band, the fee with 20% down would rise to 0.625%, or $1,250, about $500 more. You'd see the difference in your rate or your closing costs.
- FHA loans. These loans are an option, but they carry their own mortgage insurance premium. Borrowers with scores of 580 or higher can qualify with 3.5% down. At 786, a conventional loan is usually the one to price first. Still, an FHA quote is worth comparing if your down payment is small.
- Jumbo loans. Each lender sets its own score, income, and reserve requirements for loans above conventional limits. A 786 meets many of them, but ask each lender.
Small rate differences add up on a mortgage. For example, on a $300,000, 30-year loan, 6.0% instead of 6.5% saves about $98 a month, or about $35,000 over the life of the loan.
Run the numbers >> Use Kikoff's mortgage calculator to estimate your monthly payment and plan your homebuying budget.
What interest rates can you expect with a 786 credit score?
Expect offers at or near a lender's best advertised rates. Exact offers still depend on the lender, the loan, and market conditions. The Federal Reserve's averages across all borrowers were 22.15% for card accounts charging interest and 11.86% for 24-month bank personal loans. At 786, your offers will typically come in below both.
Your score already clears both top pricing cutoffs: 780 for Fannie Mae's mortgage fee and 781 for Experian's super prime auto tier. Exceptional credit starts 14 points higher, at 800, but reaching it changes what you're called more than your price. Lenders are competing for your business, so compare at least two or three offers on any loan.
5 ways to protect or raise a 786 credit score
- Check your reports before a big application. You can get all three for free every week at AnnualCreditReport.com. If something is wrong, like an account that isn't yours, dispute it with the bureau reporting it.
- Keep reported balances low. Your issuer usually reports your statement balance, so paying before the statement closes keeps your utilization low even if you pay in full. With only a few points of room above the top tiers, this matters most in the months before you apply.
- Automate every payment. Payment history makes up 35% of your FICO Score, and a missed payment stays on your report for seven years.
- Limit new applications. Each hard inquiry can take a few points off for about a year. When you're shopping for an auto loan, mortgage, or student loan, FICO counts multiple inquiries made within 14 to 45 days as one, depending on the FICO version. Card and personal loan applications each count separately.
- Freeze your credit when you're not applying. A credit freeze blocks new accounts from being opened in your name. It's free at Equifax, Experian, and TransUnion, and you can lift it temporarily when you apply.
If your report is thin on accounts, adding one helps. A Kikoff Credit Account reports your payments to all three bureaus.
Read more >> What Is a Good Credit Score in 2026?
Bottom line
A 786 score gets you approved for nearly anything, and it already earns the top auto and mortgage pricing tiers. Exceptional credit is 14 points away at 800, but that step changes the label more than the price. What matters more is staying above 780 and 781, because one high reported balance or missed payment can cost you a tier.
Kikoff brings credit building, bill and rent reporting, AI-powered disputes, credit monitoring, and debt negotiation into one place. Sign up with no credit check. Plans start at $5 a month.
Frequently Asked Questions
Article Sources
Disclaimer: The information provided in this blog post is meant for informational purposes only and does not constitute financial advice.