



With a 739 credit score, you can likely get approved for rewards credit cards, 0% intro APR cards, personal loans, prime-rate auto loans, and most mortgages.
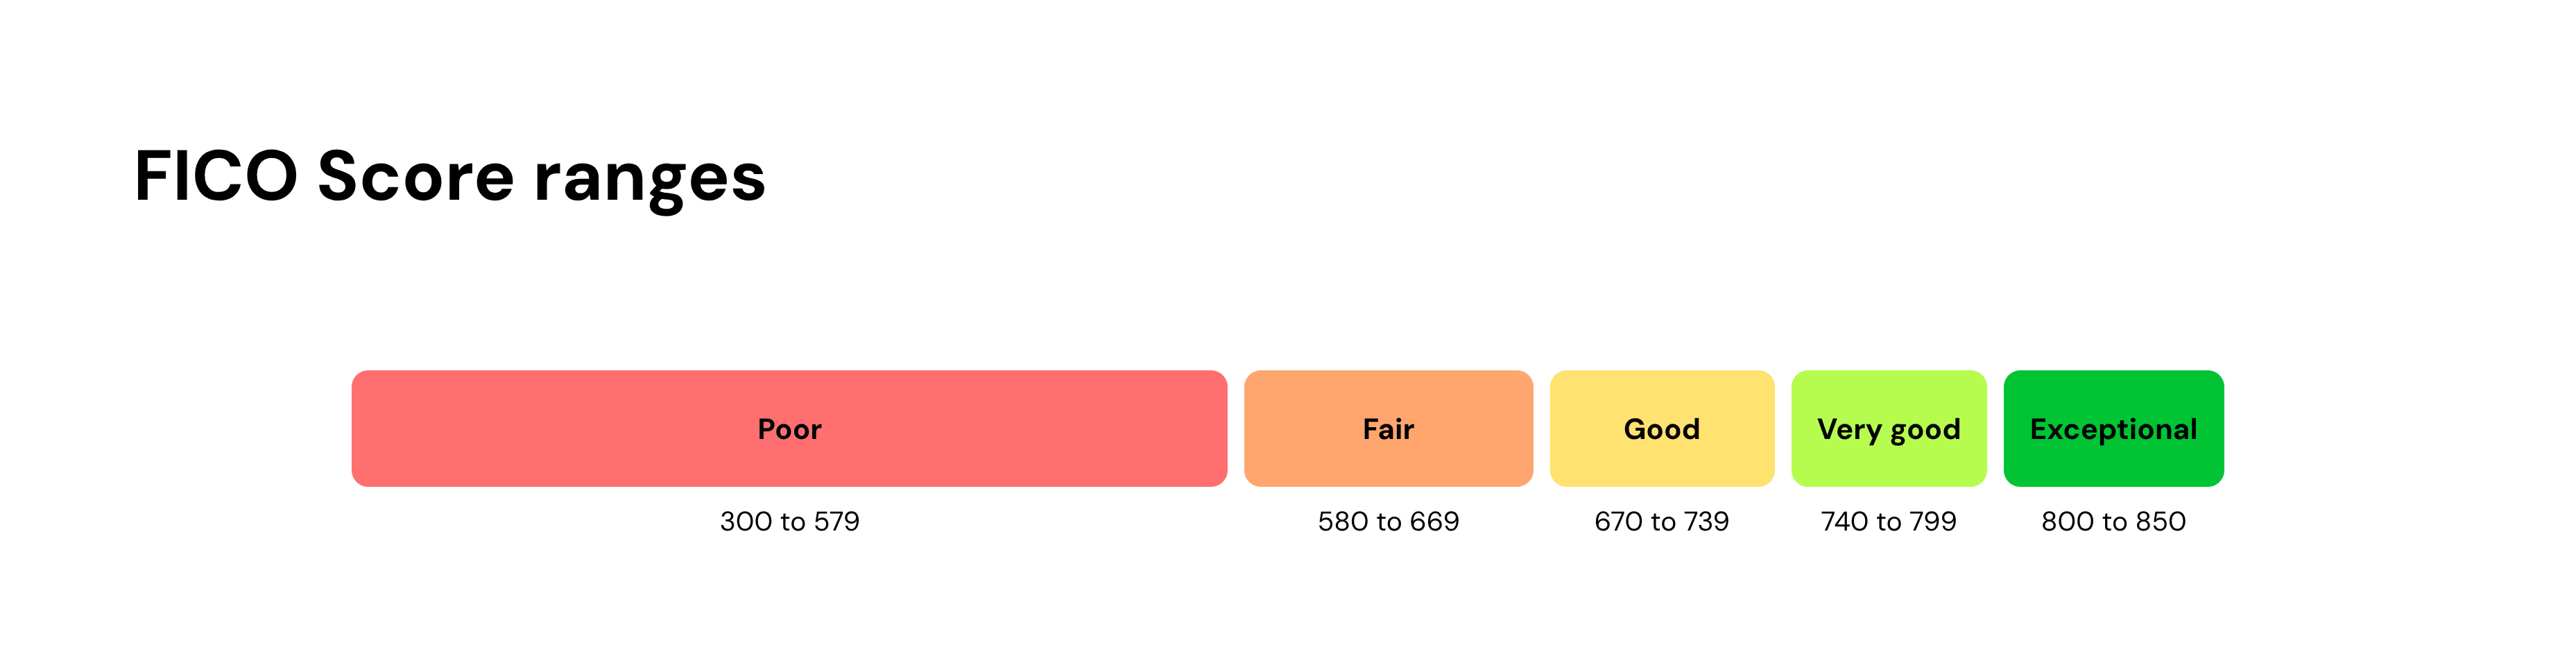
A 739 score is at the very top of FICO's good range. One more point gets you to 740, where very good credit starts and Fannie Mae's mortgage fee drops.
Is 739 a good credit score?
Yes. FICO's good range runs from 670 to 739, and 739 sits at the very top of it. Very good credit starts at 740.
What stands between 739 and very good credit is usually small, like one of these factors:
- Card balances. Using a large share of your available credit holds your score down, even if you pay in full each month. Your issuer reports the balance on your statement, so one high month can show up.
- A recent application. Each hard inquiry can take a few points off for about a year. At 739, that's enough to matter.
- History length. A score backed by a few years of accounts has less to go on than one backed by a decade. Length of credit history only grows with time.
Read more >> What Can You Get Approved For With a 770 Credit Score?
What can you get approved for with a 739 credit score?
At 739, most lenders will approve you, so what's left is the price you get. Lenders will also look closely at your income and your debt-to-income ratio (DTI).
Credit cards
Rewards cards with cash back, points, welcome offers, or introductory 0% APR periods are realistic at 739. Some premium travel cards may look for higher scores. Before applying, check whether the issuer offers prequalification, which uses a soft credit check that doesn't affect your score. A full application triggers a hard inquiry.
A good score doesn't make card interest cheap. The average rate on card accounts charging interest is 22.15%, according to the Federal Reserve. An intro 0% period helps only if you pay the balance off before it ends.
Personal loans
Most personal lenders will approve a 739 score if your income and DTI check out. You'll often see rates in the better half of a lender's advertised range, though the lowest rates usually go to higher scores. For comparison, the Federal Reserve's average for a 24-month bank personal loan is 11.86%. Federal credit unions can't charge more than 18% on most loans, so include them when you compare options.
Auto loans
At 739, you're comfortably in Experian's prime tier (661 to 780). Super prime starts at 781, 42 points away. On a $20,000, 60-month new car loan at average rates, a prime borrower would pay about $1,000 more in interest than a super prime borrower. Experian sorts these tiers by VantageScore 4.0, so your FICO score may place you a little differently.
Manufacturer promotions like 0% financing may be in reach, so ask the dealer what score a specific promotion requires. Before you visit a dealer, get preapproved by a bank or credit union. That gives you a rate to compare against the dealer's offer and any promotion.
Use an auto loan calculator to check payment amounts before you sign.
Mortgages
At a 739 credit score, most mortgage types are open to you. Your score mainly decides what you pay, depending on the type:
- Conventional loans. Fannie Mae no longer sets a minimum score for loans run through its automated system, but lenders still set their own minimums. Fannie Mae does charge lenders an upfront fee on the loans it buys, based on your score and down payment. With 20% down, the fee is 1.25% of the loan amount for scores of 720 to 739, 0.875% at 740 to 759, and 0.375% at 780+. On a $200,000 loan, that's $2,500 at 739, $1,750 at 740, and $750 at 780+, paid through a higher rate or more cash at closing. One more point would save about $750.
- FHA loans. Borrowers with scores of 580 or higher can qualify with 3.5% down. On a $250,000 home, that's $8,750 up front. Each lender can set higher minimums. If your down payment is small, get an FHA quote alongside a conventional one.
- Jumbo loans. These are for amounts above conventional loan limits. Each lender sets its own standards, usually stricter on score, income, and down payment, so whether 739 qualifies depends on the lender.
Run the numbers >> Use Kikoff's mortgage calculator to estimate your monthly payment and plan your homebuying budget.
What interest rates can you expect with a 739 credit score?
Expect solid offers, but not always a lender's best. The Federal Reserve's averages across all borrowers were 22.15% for card accounts charging interest and 11.86% for 24-month bank personal loans. At 739, your offers will likely land at or below those averages.
The next cutoff is 740, just 1 point away. That's where FICO's very good range and Fannie Mae's next fee band both start. After that, the top pricing tiers begin at 780 for Fannie Mae's mortgage fee and 781 for Experian's super prime auto tier.
5 ways to raise a 739 credit score
- Check your credit reports for errors. You can get all three for free every week at AnnualCreditReport.com. If something is wrong, like an account that isn't yours, dispute it with the bureau. Disputing is free.
- Pay down card balances before the statement closes. Your issuer usually reports the statement balance, so paying early lowers the balance that reaches your report, even if you already pay in full. That boost lasts only while the balances stay low.
- Pay every bill on time. Payment history is the biggest factor in your score, making up 35% of a FICO Score.
- Limit new applications before a big loan. Each hard inquiry can take a few points off for about a year. When you're shopping for an auto loan, mortgage, or student loan, FICO counts those inquiries as one if they fall within 14 to 45 days, depending on the FICO version. Credit card and personal loan applications each count separately.
- Think twice before closing a card. Closing one removes its credit limit, which can raise your credit utilization if you carry balances on other cards.
If your report is thin on accounts, adding one helps. A Kikoff Credit Account reports your payments to all three bureaus.
Read more >> What Is a Good Credit Score in 2026?
Bottom line
A credit score of 739 gets you approved for most cards, loans, and mortgages. From here, your score decides how much you pay. You're 1 point from 740, where FICO's very good range and a lower Fannie Mae fee band start. A low reported balance and no new applications can make the difference.
Kikoff brings credit building, bill and rent reporting, AI-powered disputes, credit monitoring, and debt negotiation into one place. Sign up with no credit check. Plans start at $5 a month.
Frequently Asked Questions
Article Sources
Disclaimer: The information provided in this blog post is meant for informational purposes only and does not constitute financial advice.