



With a 310 credit score, your most realistic approval is a secured credit card. Some credit unions may offer a small loan, and an auto loan may be possible with the right lender. Unsecured cards, most personal loans, and mortgages are out of reach for now.
If you do find a lender willing to approve you, expect to pay more, because your score sets your interest rate. The nearest milestone is 500, 190 points away, where FHA mortgages open up with 10% down.
Is 310 a poor credit score?
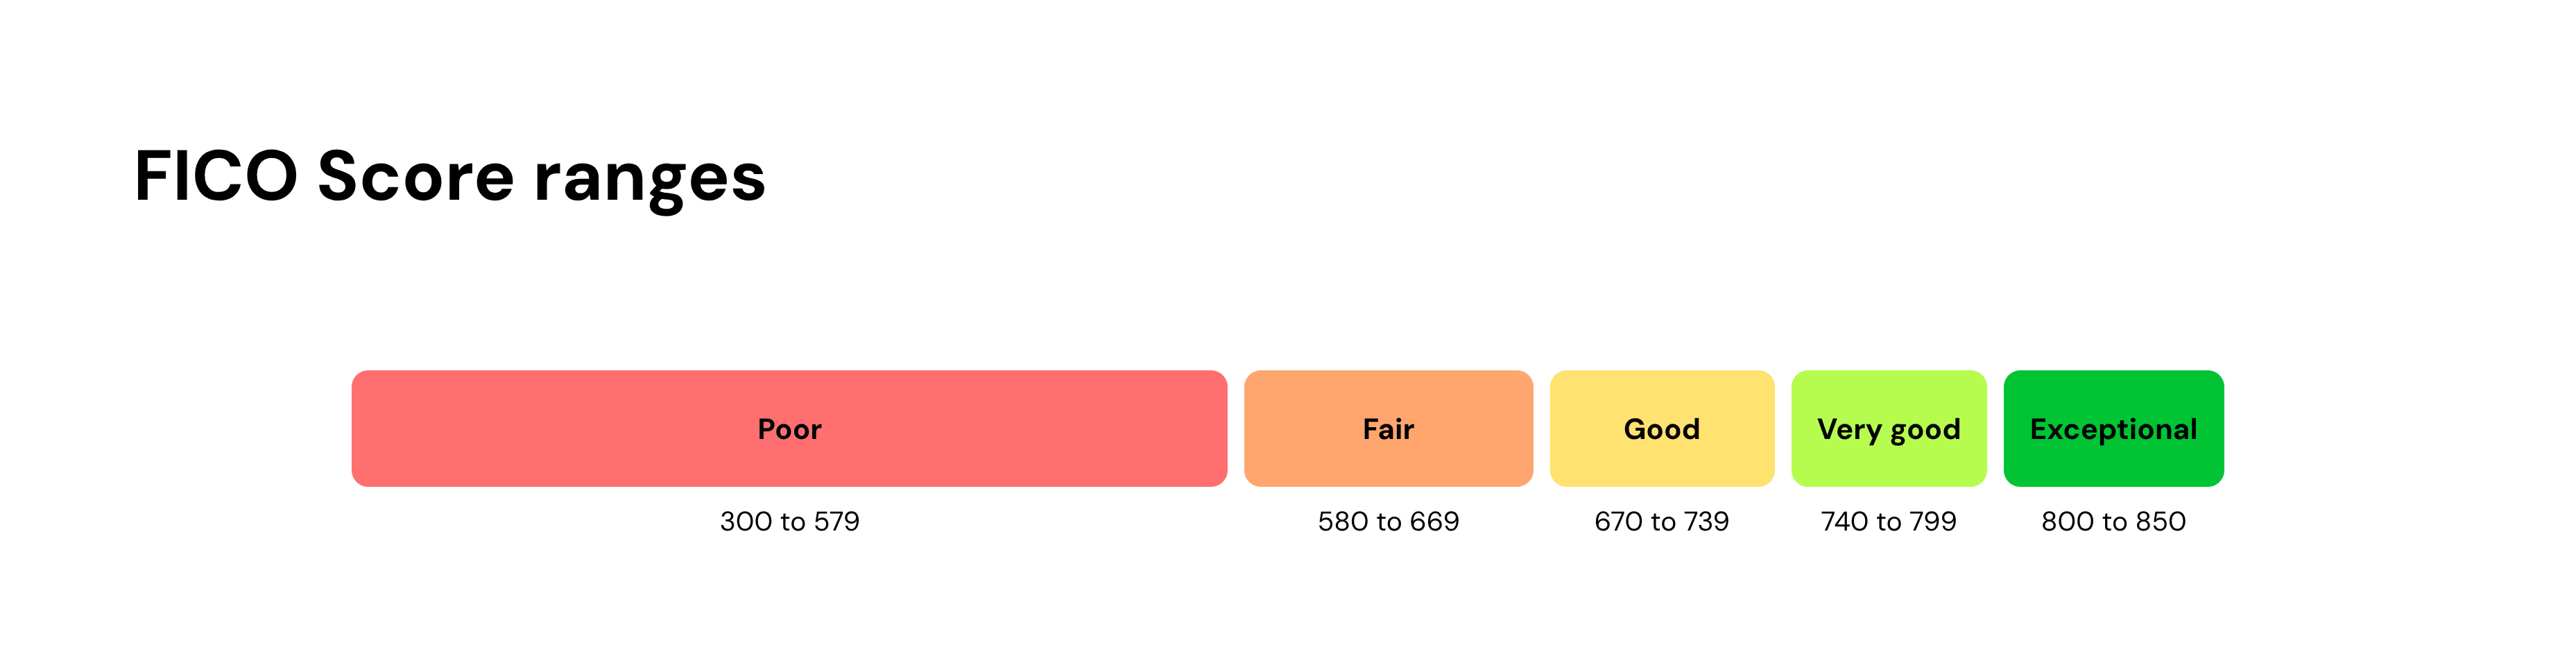
Yes. A score of 310 is near the bottom of FICO's poor range, which runs from 300 to 579. Fair credit starts at 580.
A score this low usually means your credit report includes several negative marks like:
- Missed payments. A payment 30 days late gets reported and stays for seven years. Several late payments, or one that stretched to 90 days, do more damage than a single slip.
- Accounts in collections. A debt handed off to a collection agency, often a medical bill or an old card balance. Also seven years, counted from the original delinquency.
- Charged-off accounts. A lender wrote the debt off as a loss, usually after about four to six months of no payment. You still owe it, and it still reports to the bureaus.
Lenders read that as a very high risk you won't repay. So most applications are turned down, and when one comes through, the terms reflect the risk with higher rates, bigger deposits, larger down payments, and, in some states, higher car insurance premiums.
What can you get approved for with a 310 credit score?
Few financial products are open at 310. Knowing which ones are realistic can save you an application and a hard inquiry.
Credit cards
Most credit cards are unsecured, which means nothing of value backs them. Those cards are very hard to get with a 310 score.
A secured credit card is your most realistic option. With these cards, you put down a refundable deposit that usually becomes your credit limit. A $500 deposit gets you a $500 limit, for example. The issuer holds the deposit while the account is open and keeps it if you don't pay. Approval still isn't guaranteed, because some issuers review your report.
You generally get the deposit back when you close the account in good standing or the issuer graduates you to an unsecured card after steady on-time payments.
Some subprime unsecured cards accept low scores, but even those may turn down a score this close to the floor. If you're approved, expect a low limit, a high rate, and fees.
Personal loans
A personal loan from a bank or online lender is unlikely at 310. If you're approved, expect a small amount, a short term, and a high rate.
If you need a small loan, start with a credit union. Some federal credit unions offer payday alternative loans (PALs) of up to $2,000 repaid over one to 12 months. Application fees are capped at $20, and rates can't go higher than 28%. Each credit union sets its own approval standards, so a PAL isn't guaranteed at 310.
Even so, a PAL is much cheaper than a payday loan, where a typical $15 fee per $100 borrowed works out to an APR of nearly 400%.
Auto loans
An auto loan is one of the easier loans to get approved for with a 310 score, though approval isn't guaranteed.
That's because your car is the collateral: If you stop paying, the lender can take it back and sell it to satisfy the loan. That lowers the lender's risk, but it also means falling behind puts your car at risk.
A 310 score falls in Experian's deep subprime tier (300 to 500). Your credit score plays a major role in the interest rate you're offered on a car loan. On a $20,000, 60-month new car loan at average rates, a deep subprime borrower would pay about $6,900 more in interest than a super prime borrower. Experian sorts these tiers by VantageScore 4.0, so your FICO score may place you a little differently. Experian's subprime tier starts at 501, 191 points up.
If banks and credit unions turn you down, buy here, pay here dealers finance cars themselves. Treat them as a last resort. They often require weekly or biweekly payments and charge much higher rates than traditional loans.
Use an auto loan calculator to check payment amounts before you sign.
Mortgages
A mortgage is out of reach with a credit score of 310. FHA loans have the most flexible credit requirements, allowing borrowers with scores as low as 500 with at least 10% down. Lenders can set their own minimums higher.
If you want to buy a home, work on both building your score and saving money for a down payment. Our mortgage calculator can show what 10% down looks like on a home in your price range.
Read more >> What Can You Get Approved For With a 560 Credit Score?
What interest rates can you expect with a 310 credit score?
Expect rates at the top of whatever range a lender offers, if you're approved. The Federal Reserve's averages across all borrowers were 22.15% for card accounts charging interest and 11.86% for 24-month bank personal loans. Those averages cover borrowers at every credit level. With a 310 score, your offers are likely to be higher.
The rate applies to the whole balance, so even a few points add up. If you can wait to borrow, aim for 500 first. It's 190 points up, and it's where FHA mortgages open with 10% down.
5 ways to raise a 310 credit score
- Check your credit reports for errors. You can get all three for free every week at AnnualCreditReport.com. If something is wrong, like an account that isn't yours or a late payment you made on time, dispute it with the bureau. Disputing is free.
- Bring past-due accounts current. For accounts already in collections, it can be hard to know which to pay first. The National Foundation for Credit Counseling (NFCC) can connect you to free or low-cost counseling at 800-388-2227.
- Pay every current bill on time. Payment history is the biggest factor in your score, making up 35% of a FICO Score.
- Keep card balances low. Using less of your available credit helps your score.
- Apply only when you need to. Each application can add a hard inquiry, which takes a few points off for about a year. At 310, a denial still leaves the inquiry behind. Prequalify first where you can.
If your report is thin on positive accounts, adding one helps. A Kikoff Credit Account reports your payments to all three bureaus.
Progress is often slow at first. Late payments and collections lose weight as they age, and each month of on-time payments adds to your record.
Read more >> Which Debt Should I Pay Off First?
Bottom line
A 310 score leaves you with few options: mainly secured cards, and at some credit unions, PALs. Your score doesn't just decide whether you're approved. It also sets the rate on every dollar you borrow.
The first goal is 500, 190 points from where you are now. That's where FHA mortgages open with 10% down. Building your score before your next application is how you get a lower rate.
Kikoff brings credit building, bill and rent reporting, AI-powered disputes, credit monitoring, and debt negotiation into one place. Sign up with no credit check. Plans start at $5 a month.
Frequently Asked Questions
Article Sources
Disclaimer: The information provided in this blog post is meant for informational purposes only and does not constitute financial advice.