


A credit score is a three-digit number from 300 to 850 that tells lenders how likely you are to repay what you borrow. It helps decide whether you're approved for a loan, a card, or an apartment, and even what interest rate you'll pay.
Your score is calculated from what's on your credit report, including whether you've paid on time, how much of your available credit you're using, how long you've had credit, and other factors. And you don't just have one score: FICO and VantageScore build the scoring models, and each of the three credit bureaus can give you a different number.
How credit scores are calculated
Your credit score comes from your credit reports, the records kept by the three major credit bureaus:
- Equifax
- Experian
- TransUnion
Banks, card issuers, lenders, and collection agencies report your accounts to these bureaus. Scoring models from FICO and VantageScore then turn that report into a number.
To produce a FICO Score, your report needs at least one account that's been open for six months or longer, and at least one account reported in the past six months. Without both, you have a credit report but no FICO Score.
VantageScore's bar is lower: It can score a report with one account that's been open for about a month. That's why a credit app may show you a score while a lender says it can't pull a FICO Score.
Read more >> How to Build Credit From Scratch
Your biggest bill may be building nothing
Rent is usually the largest and most consistent payment a renter makes, and many landlords don’t report it to the credit bureaus. Years of paying on time can leave your file exactly where it started.
Kikoff Rent Reporting adds your rent to your Equifax and TransUnion reports, and can include up to two years of past rent. That's payments you’ve already made, counting for the first time.
The different types of credit scores
Many people talk about "your credit score" as if there's a single number. In fact, there are two main scoring models: FICO and VantageScore.
Both are designed to show lenders how risky you are to lend to, but each works a bit differently.
FICO
FICO is the industry leader, saying 90% of top lenders use its scores. If you apply for any kind of credit, chances are the lender will check your FICO Score.
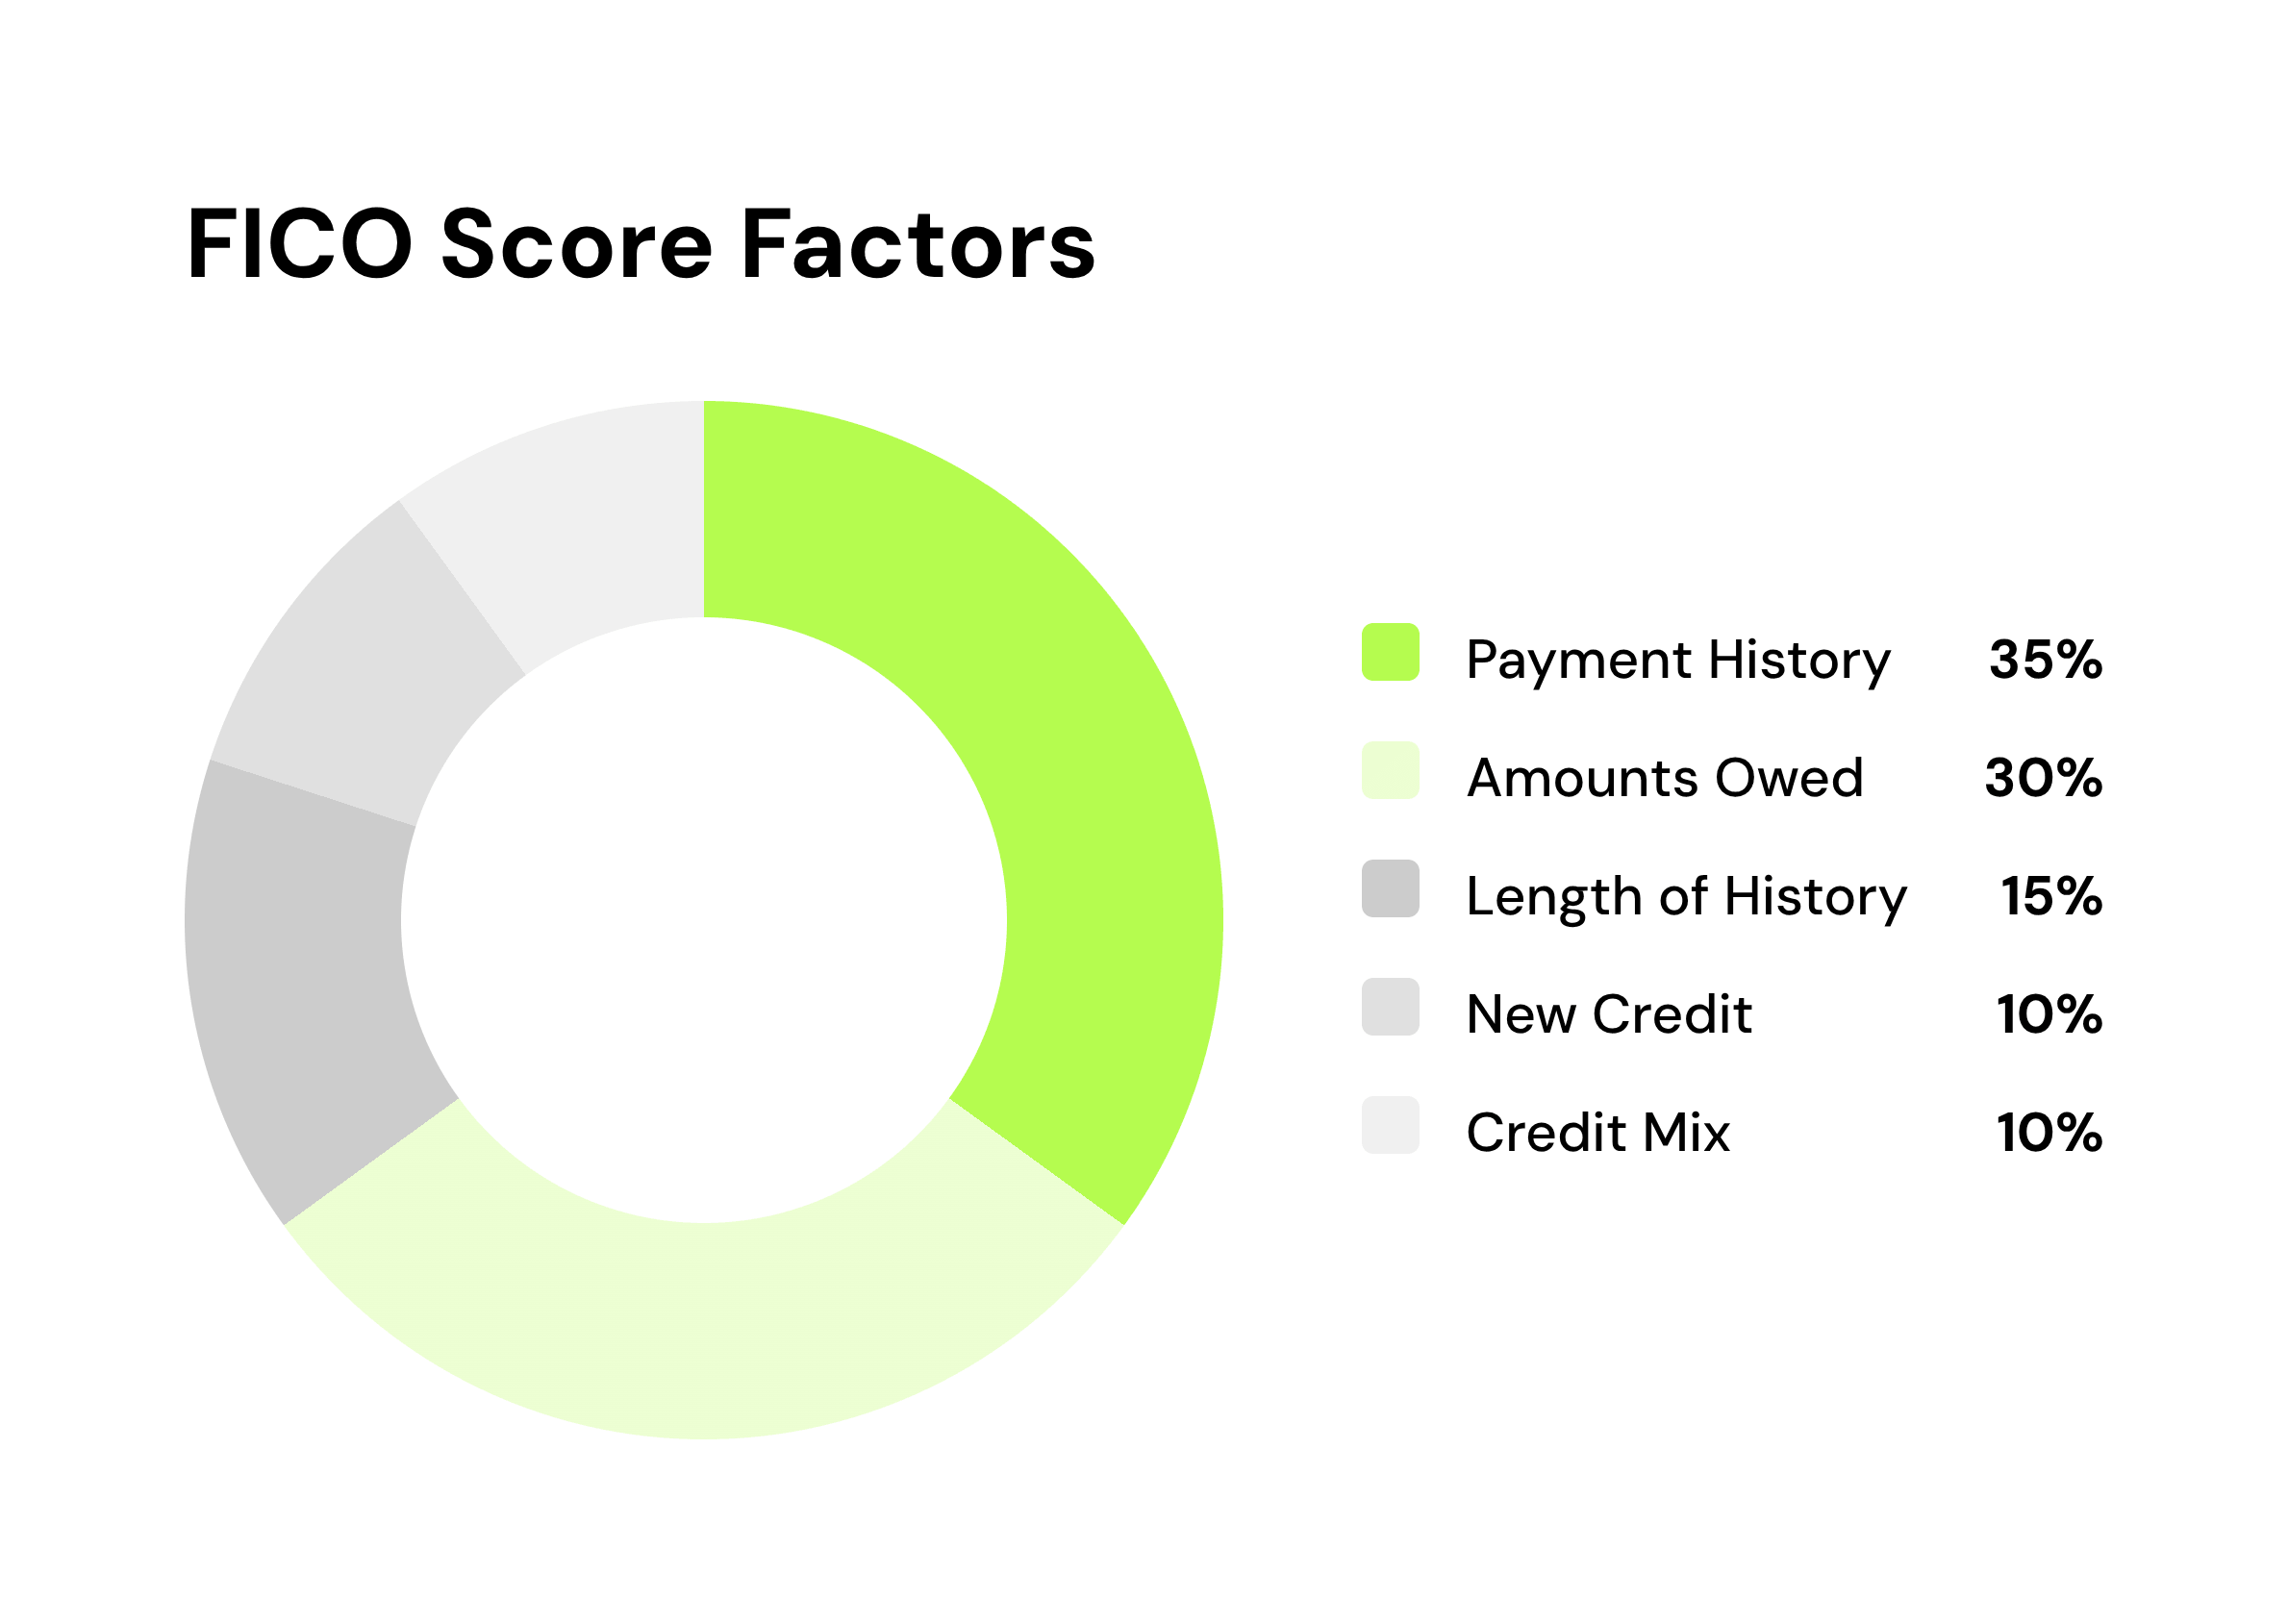
FICO weighs five factors: payment history (35%), amounts owed (30%), length of credit history (15%), new credit (10%), credit mix (10%).
If you've ever looked up your FICO score, you may have seen more than one number. FICO releases new versions from time to time, and each lender chooses which one to use. FICO also makes versions built for card issuers and auto lenders.
Each of the three bureaus can produce a FICO Score from its own data. Since the bureaus don't always have the same information, it's normal for your scores to differ a little from bureau to bureau.
VantageScore
VantageScore was created by the three bureaus in 2006. It isn't as widely used as FICO, but it's gaining ground. In September 2026, the Federal Housing Finance Agency approved VantageScore 4.0 for mortgages sold to Fannie Mae and Freddie Mac.
Like FICO, it uses weighted factors, with VantageScore 4.0 using six: payment history (41%), depth of credit (20%), credit utilization (20%), recent credit (11%), balances (6%), and available credit (2%).
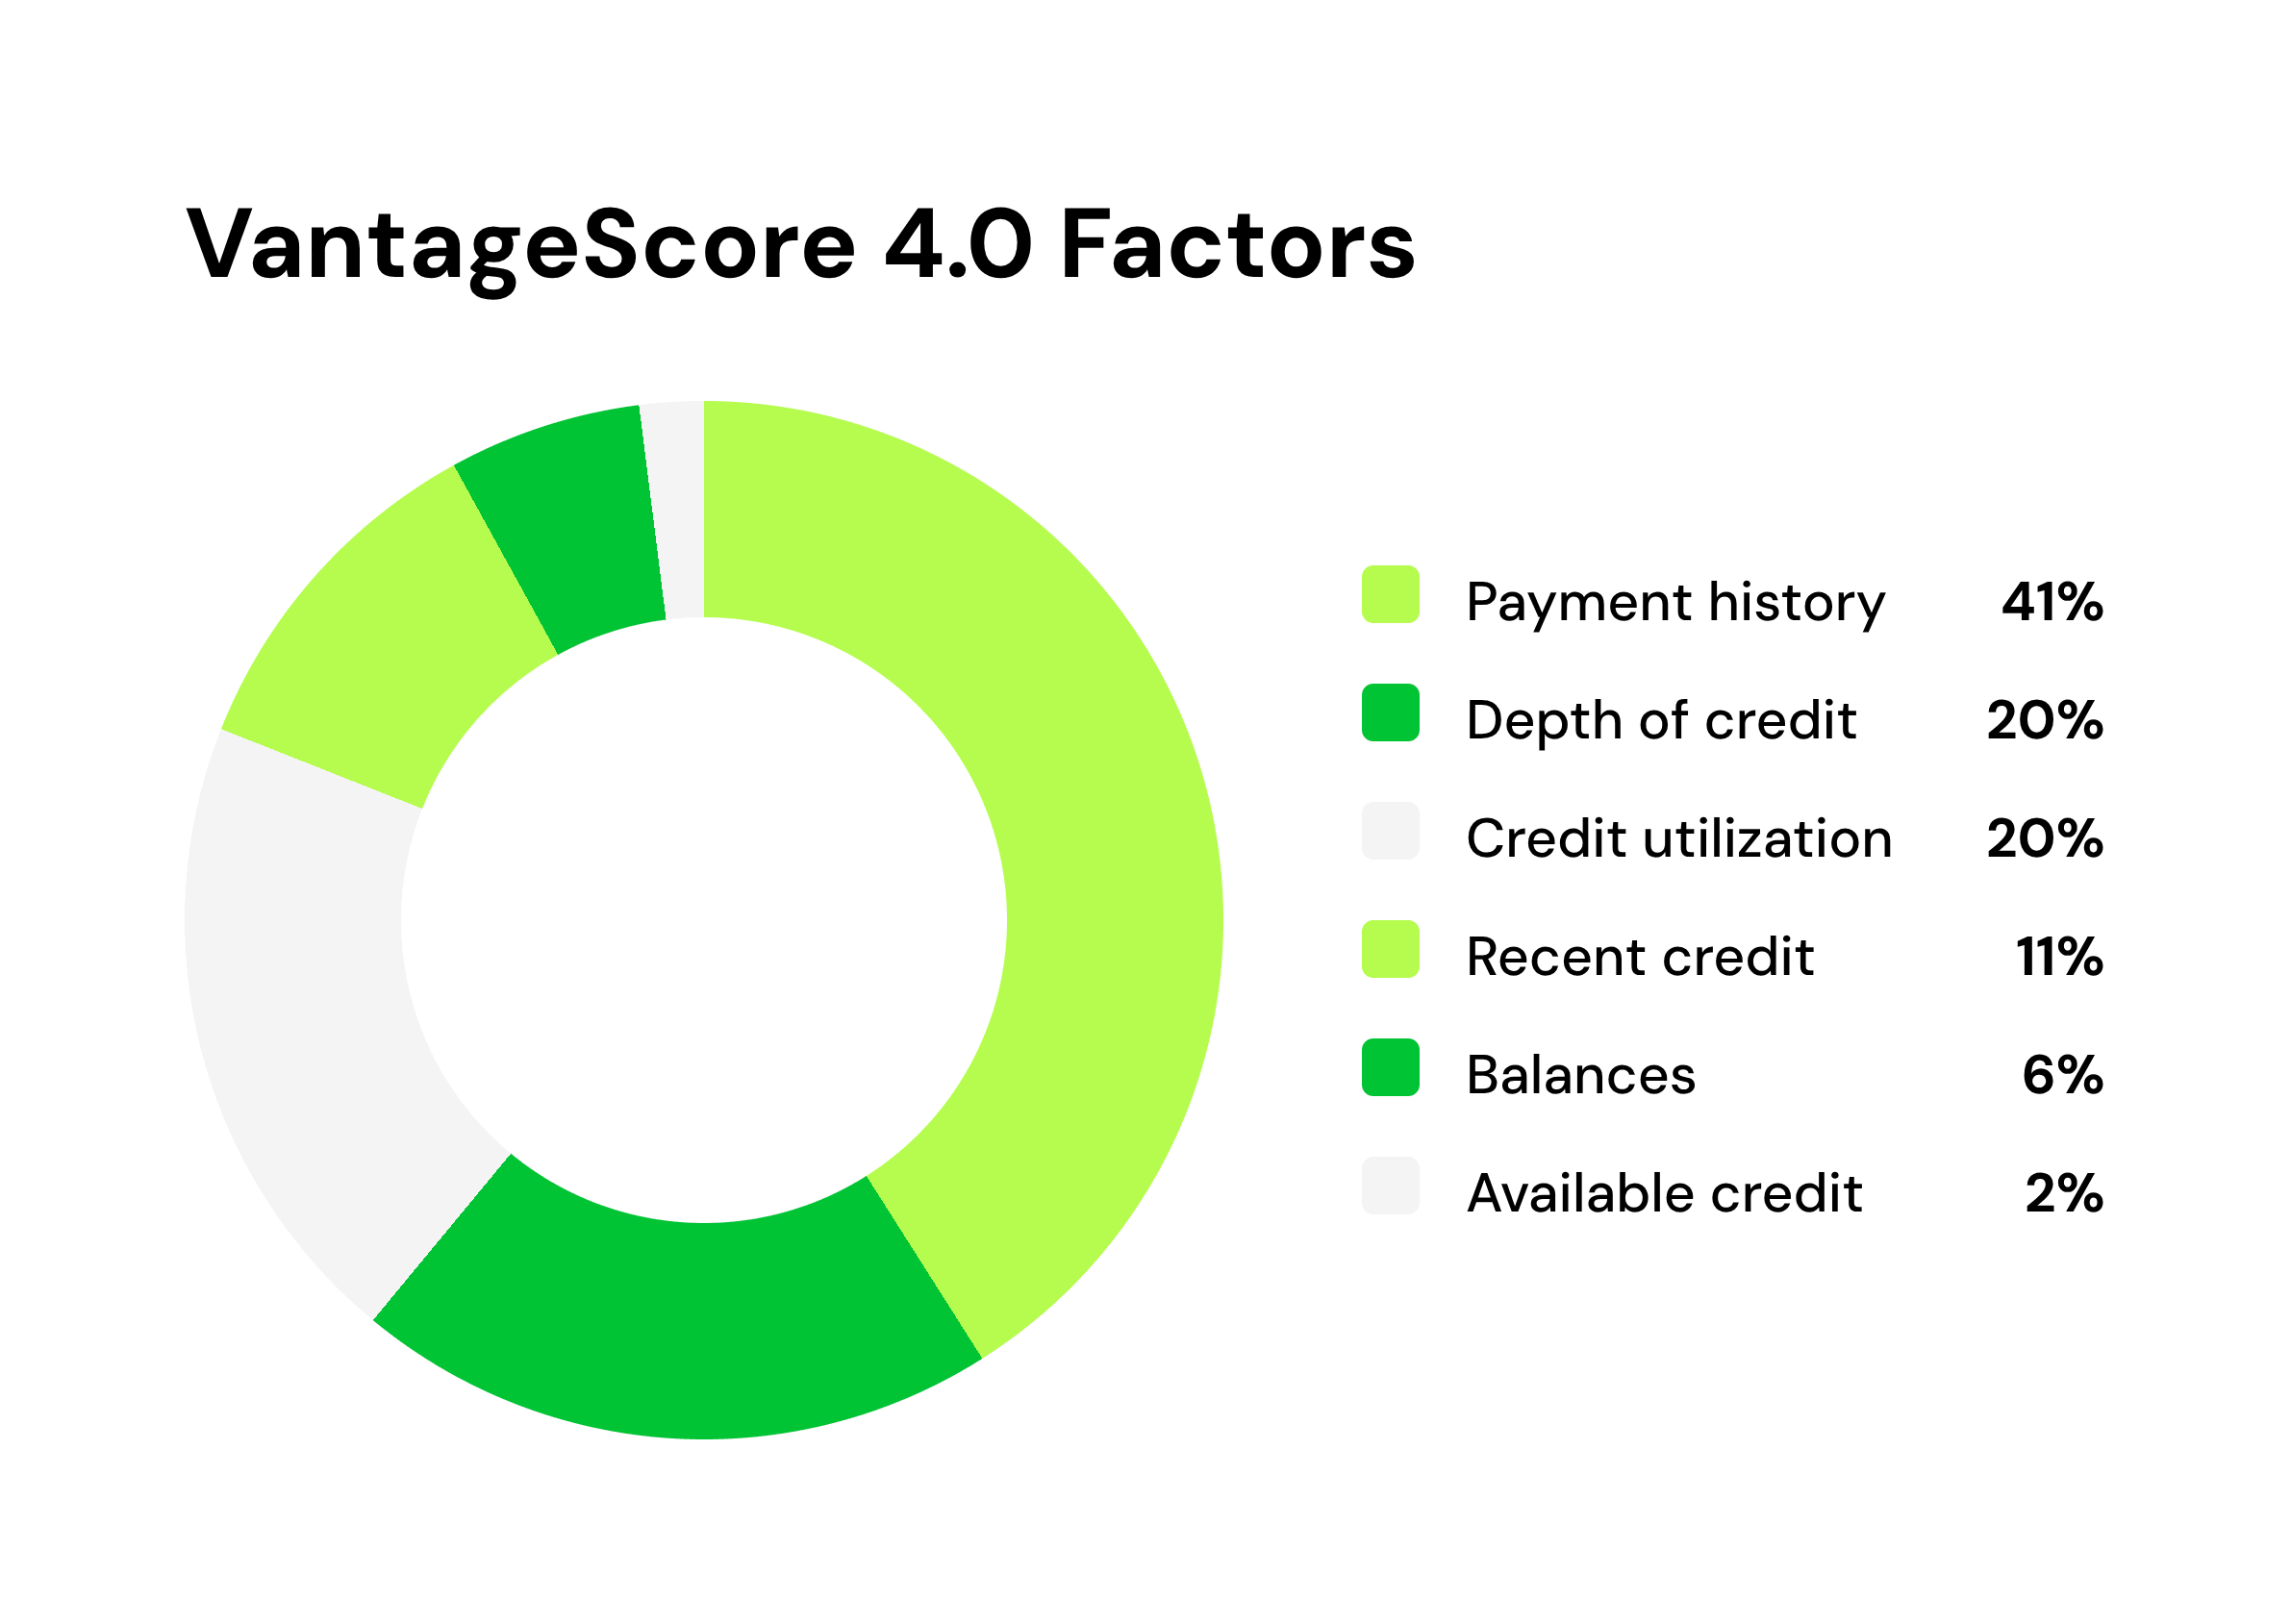
Because the two models weigh factors differently, your FICO Score and your VantageScore won't always match.
Read more >> What's the Difference Between FICO and VantageScore?
What is a good credit score?
Every credit score is on a spectrum. The average FICO Score in the U.S. is 713 as of March 2026, according to Experian.
To help people understand where their credit stands, FICO and VantageScore publish score ranges.
FICO Scores run from 300 to 850:
VantageScores also run from 300 to 850. Before VantageScore 3.0 came out in 2013, they used a scale of 501 to 990.
VantageScore sorts scores into four tiers:
The two scoring models cover the same range, but tiers don't line up. A 670 is a good score with FICO and prime with VantageScore, and the same person can have different numbers on each.
Read more >> What Is a Good Credit Score ?
Why credit scores matter
Your credit score can affect more than whether you're approved for a credit card or loan. Here's where it shows up.
Your credit score isn’t your credit report
Your credit report is the record: every account, balance, payment, and collection, kept by Equifax, Experian, and TransUnion. It’s free every week at AnnualCreditReport.com.
Your credit score is a number calculated from that record. There isn’t just one: FICO and VantageScore use different formulas, lenders pull different versions, and the score in your banking app might not be the one a lender sees.
What a score leaves out: Your score is built only from what's in your credit report. Your income, job, savings, address, age, race, and marital status aren't part of it. A lender may still ask about income separately, but a job loss or a pay cut doesn't lower your score by itself.
What this means for you: The report is what you fix, and the score is what moves afterward. You can dispute something on your report. You can’t dispute a score.
How to check your credit score
Your credit reports are free every week at AnnualCreditReport.com, but the reports don't include a score. For the score itself:
- Your card issuer or bank. Many show a free score in their app or on your statement. Check which model it uses and which bureau it comes from.
- The credit bureaus. Experian, Equifax, and TransUnion each offer free access to a score on their sites either for free or through a membership.
- Kikoff. Every Kikoff plan includes a weekly credit report, and Kikoff Premium adds three-bureau reports and scores.
Checking your own score is a soft inquiry, so it never lowers it.
Read more >> 5 Best Credit Monitoring Apps
What can hurt your credit score?
Factor weights show what the scoring models care about. Here's what tends to move your score in real life.
Late payments
Payment history is the biggest factor in both FICO and VantageScore, so one late payment can cause a significant drop.
A payment usually isn't reported as late until it's 30 days past due. Once it's reported, it stays on your report for up to seven years, though its effect on your score fades over time.
High credit utilization
Credit utilization is how much of your available credit you're using. When you're using more of your available credit, lenders see you as a risky borrower, and your score can drop.
A common rule of thumb is to stay under 30%. FICO's own guidance is that lower is better, and that keeping your utilization below 10% can help you build and maintain a good score.
Collections
An account usually goes to collections after several months of missed payments, so the late payments are already on your report. A collection adds a second, more serious negative mark.
How much it hurts depends on where your credit started. Someone at 700 has further to fall than someone at 450, so the same collection can drop the higher score more. That's because scoring models measure change in risk, and a new collection is a bigger change on an otherwise clean report.
If a collection is accurate, disputing it won't remove it, but you may be able to settle it. Kikoff's AI Debt Negotiation, free for all Kikoff users, contacts the collector and works toward a settlement offer, typically within five business days. Settling for less than the full balance can still affect your credit, so weigh that before you accept. A nonprofit credit counselor can help you compare a settlement with a payment plan.
Bankruptcy
Two common types of bankruptcy are:
- Chapter 7, which wipes out many debts, though you may have to sell some of what you own. Most student loans, recent taxes, child support, and alimony usually survive.
- Chapter 13, which sets up a three- to five-year repayment plan and usually lets you keep your property.
Bankruptcy can give you a fresh start, but it usually causes a large drop in your score. As with collections, higher starting scores tend to fall further. Chapter 7 stays on your credit report for 10 years, and Chapter 13 for seven years from the filing date.
What you can keep and which debts qualify depend on state law. A licensed bankruptcy attorney can explain how the rules apply where you live. To talk through alternatives first, the National Foundation for Credit Counseling (NFCC) offers free or low-cost counseling at 800-388-2227.
Closing old accounts
Say you've just paid off a credit card and want to close it so you aren't tempted to use it again. That's a reasonable choice, but it can push your credit utilization up without you spending a dime.
Here's how it works with two cards:
Right now, you're using $1,000 of $3,000 in total credit. That's 33%.
Close the paid-off card, and the $1,000 limit goes with it. Same debt, same spending, but now you're using $1,000 of $2,000. That's 50%. Without borrowing another dollar.
The card itself doesn't disappear from your report. If it was in good standing, it stays on your report for up to 10 years, continuing to count toward your credit history the whole time. What you lose is its limit.
Applying for a lot of credit at once
When you apply for a loan or a card, the lender does a hard inquiry into your credit file. For most people, one inquiry takes less than five points off a FICO Score, and the effect fades within a year.
Several applications in a short window add up, because to a lender, they signal new debt on the way.
Rate shopping is the exception. If you're comparing offers for a mortgage, an auto loan, or a student loan within 14 days (or up to 45 days with newer FICO versions), FICO groups those inquiries together, so three quotes affect your score about as much as one.
Read more >> Most Common Credit Building Mistakes
When your score changes on its own. Each lender reports to the bureaus on its own schedule, usually once a month, so your score can shift several times a month as new balances post. A high balance reported the day before your payment can make your utilization look higher than it really is.
Paying off a loan can also lower your score slightly. If it was your only installment loan, your credit mix becomes less varied. The drop is usually small, and the paid-off loan stays on your report as positive history.
How to improve your credit score
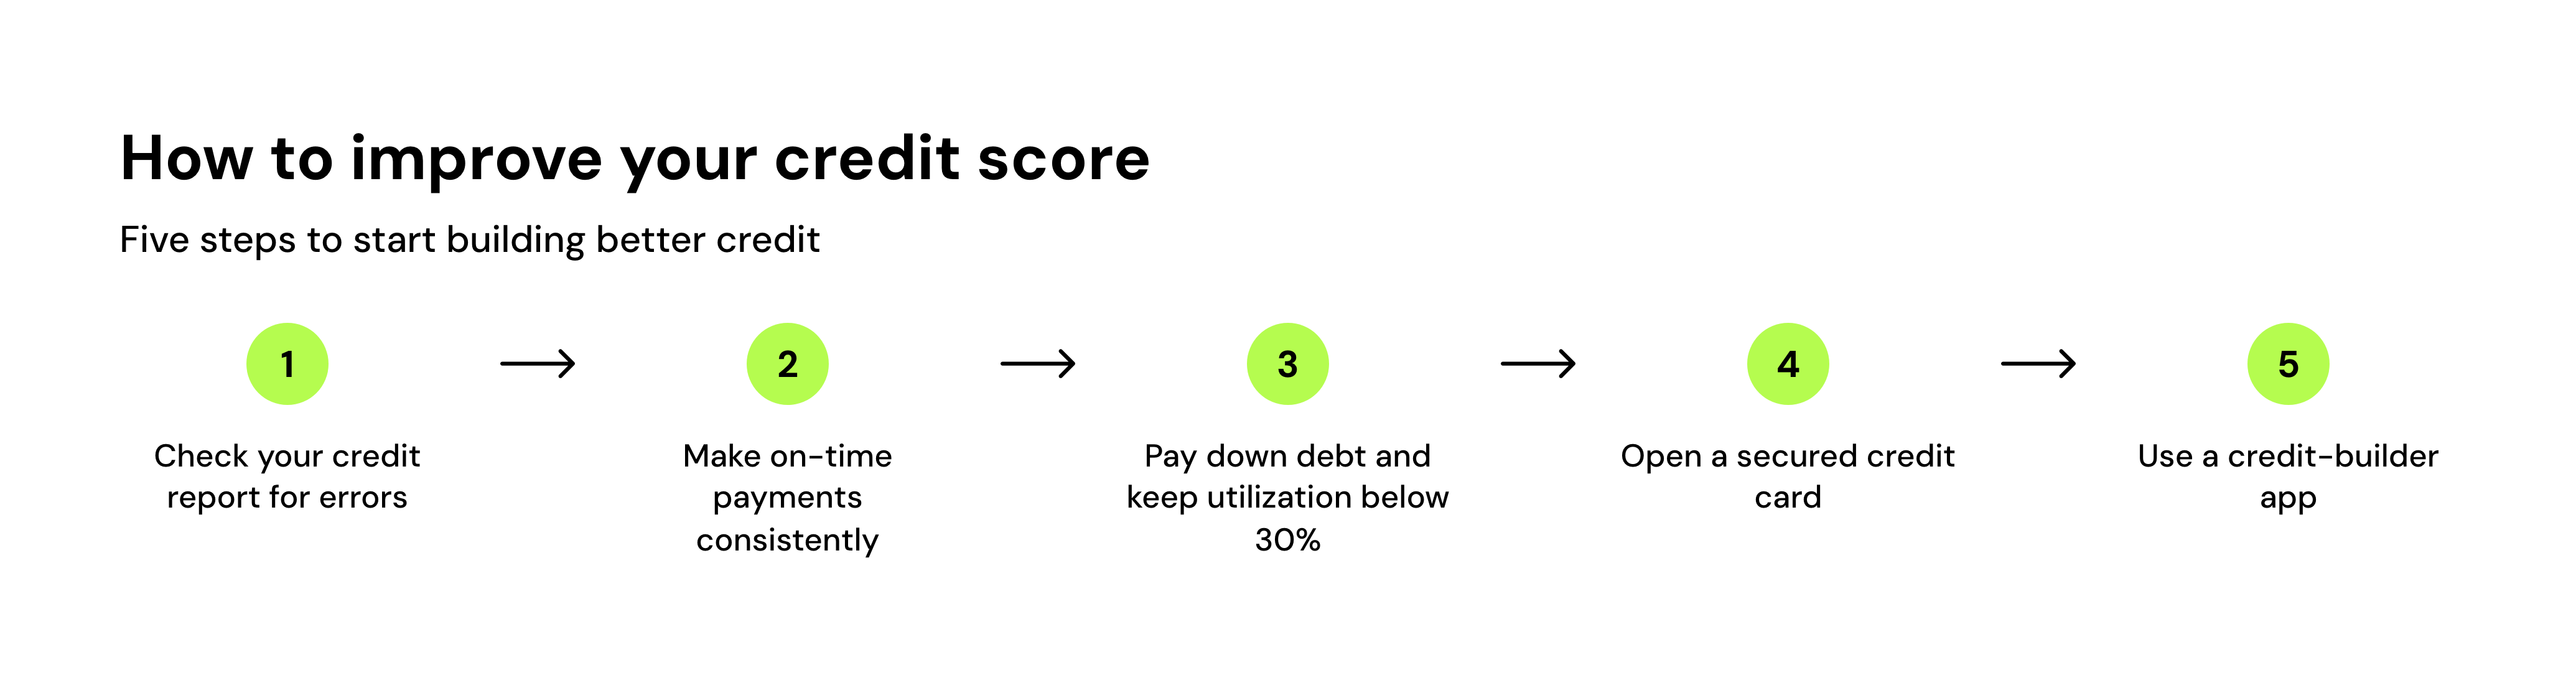
These five steps can move your score in the right direction.
1. Check your credit report for errors
Credit reports are usually accurate, but mistakes happen. Start with your reports from all three bureaus. They're free every week at AnnualCreditReport.com. Look for accounts you don't recognize, wrong balances, or late payments you actually made on time.
If something is wrong, dispute it with each bureau that shows it and with the company that reported it.
You can do it for free online with each of the bureaus. If you'd rather not write the letters yourself, Kikoff's AI Credit Disputes drafts them for you in a few taps.
Disputes only work on information that's inaccurate, not on accurate negative marks, like bills you paid late.
2. Keep making on-time payments
Payment history carries the most weight in both FICO and VantageScore models. If you have a car loan, personal loan, credit card, or other credit account, paying on time every month is the most direct way to build your score over time.
3. Pay down debt and keep utilization low
Lowering your card balances can lift your score quickly, because utilization is based on your most recent reported balances.
Pick a payoff method
If you have high credit card balances, a payoff plan helps. Two common debt payoff strategies:
- Snowball method, which targets debts by lowest balance first, offering quick wins that can keep you motivated.
- Avalanche method, which targets debts with the highest rates first, saving you the most in interest as you pay down what you owe.
With either method, you pay the minimum on every account and put whatever extra you have toward one target bill. When that bill is cleared, you roll its whole payment (the minimum plus the extra) to the next target. Each bill you clear makes the next one go faster.
Other options
If you qualify, a debt consolidation loan can carry a lower rate than your cards, depending on your credit. A loan moves the debt rather than reducing it, and the cards you pay off stay open, which can be tempting to fill back up.
Another option is becoming an authorized user on someone else's card. That adds that account's history and limit to your report, as long as the issuer reports authorized users. You aren't responsible for the balance, but the account isn't yours either: The cardholder can remove you at any time, and their late payments can show up on your own report.
4. Open an account for building credit
If you have a low score or a thin credit file, common advice is to get a credit card, use it for small purchases, and pay it off each month. If you can't qualify for a traditional card, a secured card is one option.
With a secured card, you pay a refundable deposit, which usually sets your limit. You use it and pay it off like a regular card. And you get the deposit back when you close the account in good standing or the issuer upgrades you to an unsecured card with a history of on-time payments.
5. Try a credit-builder account
A secured card asks you to put money up front, and that deposit stays tied up until you close the account or get upgraded. A credit-builder account works without a deposit.
The Kikoff Credit Account is a credit line that reports to Equifax, Experian, and TransUnion. There's no credit check to open it and no deposit. When you pay on time each month, that payment is added to your credit history at all three bureaus — the factor both FICO and VantageScore weigh most. The account also adds to your available credit, which can help lower your utilization.
Read more >> 7 Ways to Improve Your Credit Fast
Bottom line
A credit score is a three-digit number that tells lenders how you handle credit, built from what's on your reports at Equifax, Experian, and TransUnion. Both FICO and VantageScore weight one factor most: whether you pay on time.
That factor only counts if an account is reporting it. If nothing on your report has been updated in the past six months, FICO can't score you at all.
What helps most next depends on what your report is missing. Kikoff brings credit building, bill and rent reporting, AI-powered disputes, credit monitoring, and debt negotiation into one place. Sign up with no credit check. Plans start at $5 a month.
Frequently Asked Questions
Article Sources
Disclaimer: The information provided in this blog post is meant for informational purposes only and does not constitute financial advice.