


With an 801 credit score, you can likely get approved for nearly any credit card, personal loan, auto loan, or mortgage, as long as your income and debts support what you're borrowing. You're just inside exceptional credit and already in the top auto and mortgage pricing tiers.
The cutoffs that matter now sit below you. You're 20 points above 781, where Experian's super prime auto tier starts, and 21 points above 780, where Fannie Mae's top mortgage fee band starts.
Is 801 a good credit score?
Yes. FICO's exceptional range runs from 800 to 850, and 801 sits near the bottom of it.
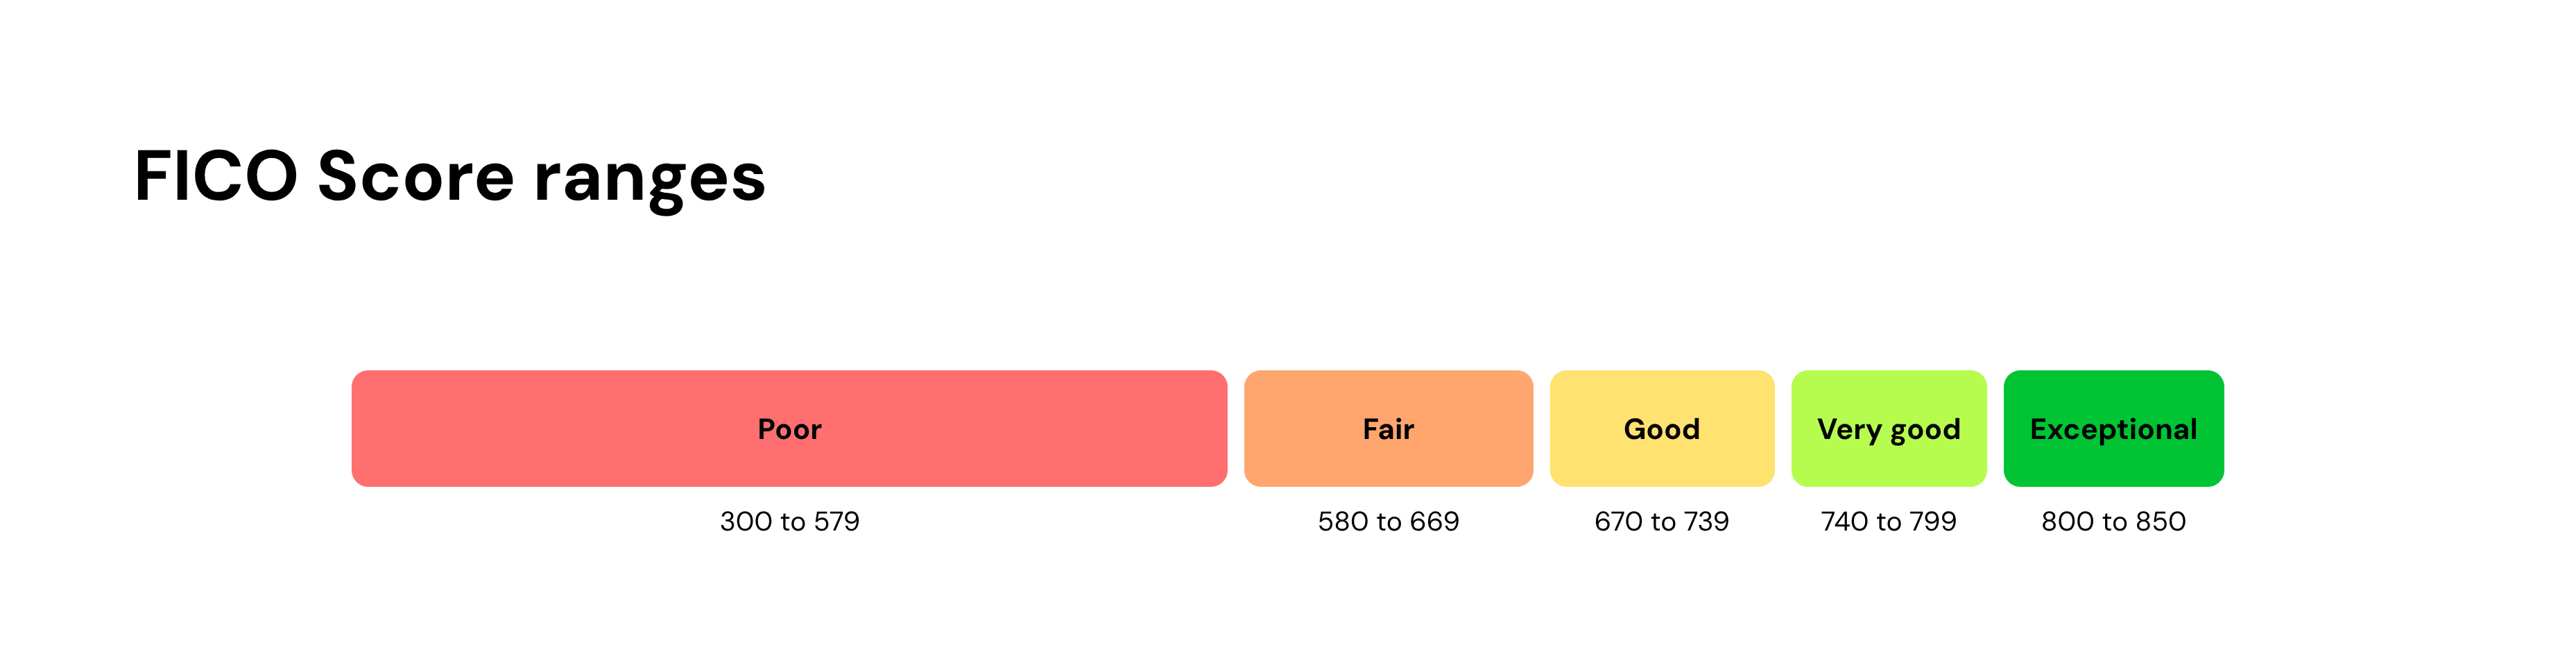
A score this high usually reflects years of on-time payments, low reported balances, and few recent applications. At 801, a high statement balance or a new hard inquiry could drop you below 800. That changes what you're called more than what you pay. Fannie Mae's fee and Experian's auto tiers don't change unless you fall below 780 or 781.
Read more >> What Is a Good Credit Score in 2026?
What can you get approved for with an 801 credit score?
At 801, your score usually isn't what's limiting you. Lenders will look harder at your income, your job history, and your debt-to-income ratio (DTI).
Credit cards
Premium travel cards, top-tier cash back cards, large sign-up bonuses, high credit limits, and long 0% intro APR offers are all realistic at 801. You'll likely see more prescreened offers, too.
Since you can choose almost any card, pick the ones you'll actually use. If you travel, look for airfare and hotel rewards or lounge access. If you're planning a large purchase, a long 0% intro APR period can be worth more than points. It helps only if you pay the balance off before the period ends.
Each new application triggers a hard inquiry, so open a new card only when it serves a financial goal. Before applying, check whether the issuer offers prequalification. It uses a soft credit check that doesn't affect your score.
Personal loans
Expect offers at or near a lender's lowest advertised interest rates.
The Federal Reserve's average for a 24-month bank personal loan is 11.86%, and an 801 borrower will typically see offers below that.
How much you can borrow still depends on your income and existing debt.
Auto loans
At 801, you're in Experian's super prime tier (781+), 20 points above where it starts. Super prime borrowers average 4.41% on new cars and 6.29% on used cars. On a $20,000, 60-month new car loan at average rates, a super prime borrower would pay about $1,000 less in interest than a prime borrower. Dropping below 781 would cost you that difference. Experian sorts these tiers by VantageScore 4.0, so your FICO score may place you a little differently.
Manufacturer promotions like 0% financing or cash back offers are realistic at this score. Ask the dealer what score a specific promotion requires. Get preapproved by a bank or credit union first, then compare that rate against the dealer's financing and any promotion. A cash rebate can be worth more than a lower rate.
Use an auto loan calculator to check payment amounts before you sign.
Mortgages
At 801, every mainstream mortgage type is open to you, and your score already earns Fannie Mae's best pricing. Your down payment is now what matters most.
- Conventional loans. Fannie Mae charges lenders an upfront fee on the loans it buys, based on your score and down payment. For scores of 780 and up, that fee is 0.375% of the loan amount with 20% down and 0% with 25% down or more. On a $200,000 loan, that's $750 versus $0. You'd see the difference in your rate or your closing costs.
- FHA loans. These loans are an option, but they carry their own mortgage insurance premium. Borrowers with scores of 580 or higher can qualify with 3.5% down, or $8,750 on a $250,000 home. Each lender can set higher minimums. At 801, a conventional loan is usually the one to price first. Still, an FHA quote is worth comparing if your down payment is small.
- Jumbo loans. Each lender sets its own score, income, and reserve requirements for loans above conventional limits. At 801, your score will rarely be what holds you back. Income and reserves usually decide approval, so ask each lender.
Small rate differences add up on a mortgage. For example, on a $300,000, 30-year loan, 6.0% instead of 6.5% saves about $98 a month, or about $35,000 over the life of the loan.
Run the numbers >> Use Kikoff's mortgage calculator to estimate your monthly payment and plan your homebuying budget.
What interest rates can you expect with an 801 credit score?
Expect offers at or near a lender's best advertised rates. Exact offers still depend on the lender, the loan, and market conditions. The Federal Reserve's averages across all borrowers were 22.15% for card accounts charging interest and 11.86% for 24-month bank personal loans. At 801, your offers will typically come in below both.
Raising your score past 801 changes little. The top pricing tiers start below you: 781 for Experian's super prime auto tier and 780 for Fannie Mae's mortgage fee. That leaves you a cushion of 20 and 21 points. Lenders are competing for your business, so compare at least two or three offers on any loan.
5 ways to protect an 801 credit score
- Check your reports regularly. You can get all three for free every week at AnnualCreditReport.com. If something is wrong, like an account that isn't yours, dispute it with the bureau.
- Freeze your credit when you're not applying. A credit freeze blocks new accounts from being opened in your name. It's free at Equifax, Experian, and TransUnion, and you can lift it temporarily when you apply.
- Automate every payment. Payment history makes up 35% of your FICO Score, and a missed payment stays on your report for seven years.
- Keep reported balances low. Your issuer usually reports your statement balance, so paying before the statement closes keeps your utilization low even if you pay in full.
- Rate-shop in one window. FICO counts multiple auto, mortgage, or student loan inquiries made within 14 to 45 days as one, depending on the FICO version. Card and personal loan applications each count separately, and each hard inquiry can take a few points off for about a year.
Read more >> How to Get an 850 Credit Score
Bottom line
At 801, you can get approved for nearly anything at a lender's best pricing. You have 20 points of room above super prime auto pricing and 21 above Fannie Mae's top fee band. Protecting that cushion matters more than chasing 850.
Kikoff brings credit building, bill and rent reporting, AI-powered disputes, credit monitoring, and debt negotiation into one place. Sign up with no credit check. Plans start at $5 a month.
Frequently Asked Questions
Article Sources
Disclaimer: The information provided in this blog post is meant for informational purposes only and does not constitute financial advice.