


With a 684 credit score, you can likely get approved for rewards credit cards, personal loans, prime-rate auto loans, and most mortgages.
A 684 score is good credit, but only by 14 points, and the lowest rates still go to higher scores. The next pricing cutoff is 700, just 16 points away. Very good credit starts at 740, 56 points away.
Is 684 a good credit score?
Yes. FICO's good range runs from 670 to 739, and 684 sits in the lower half of it.
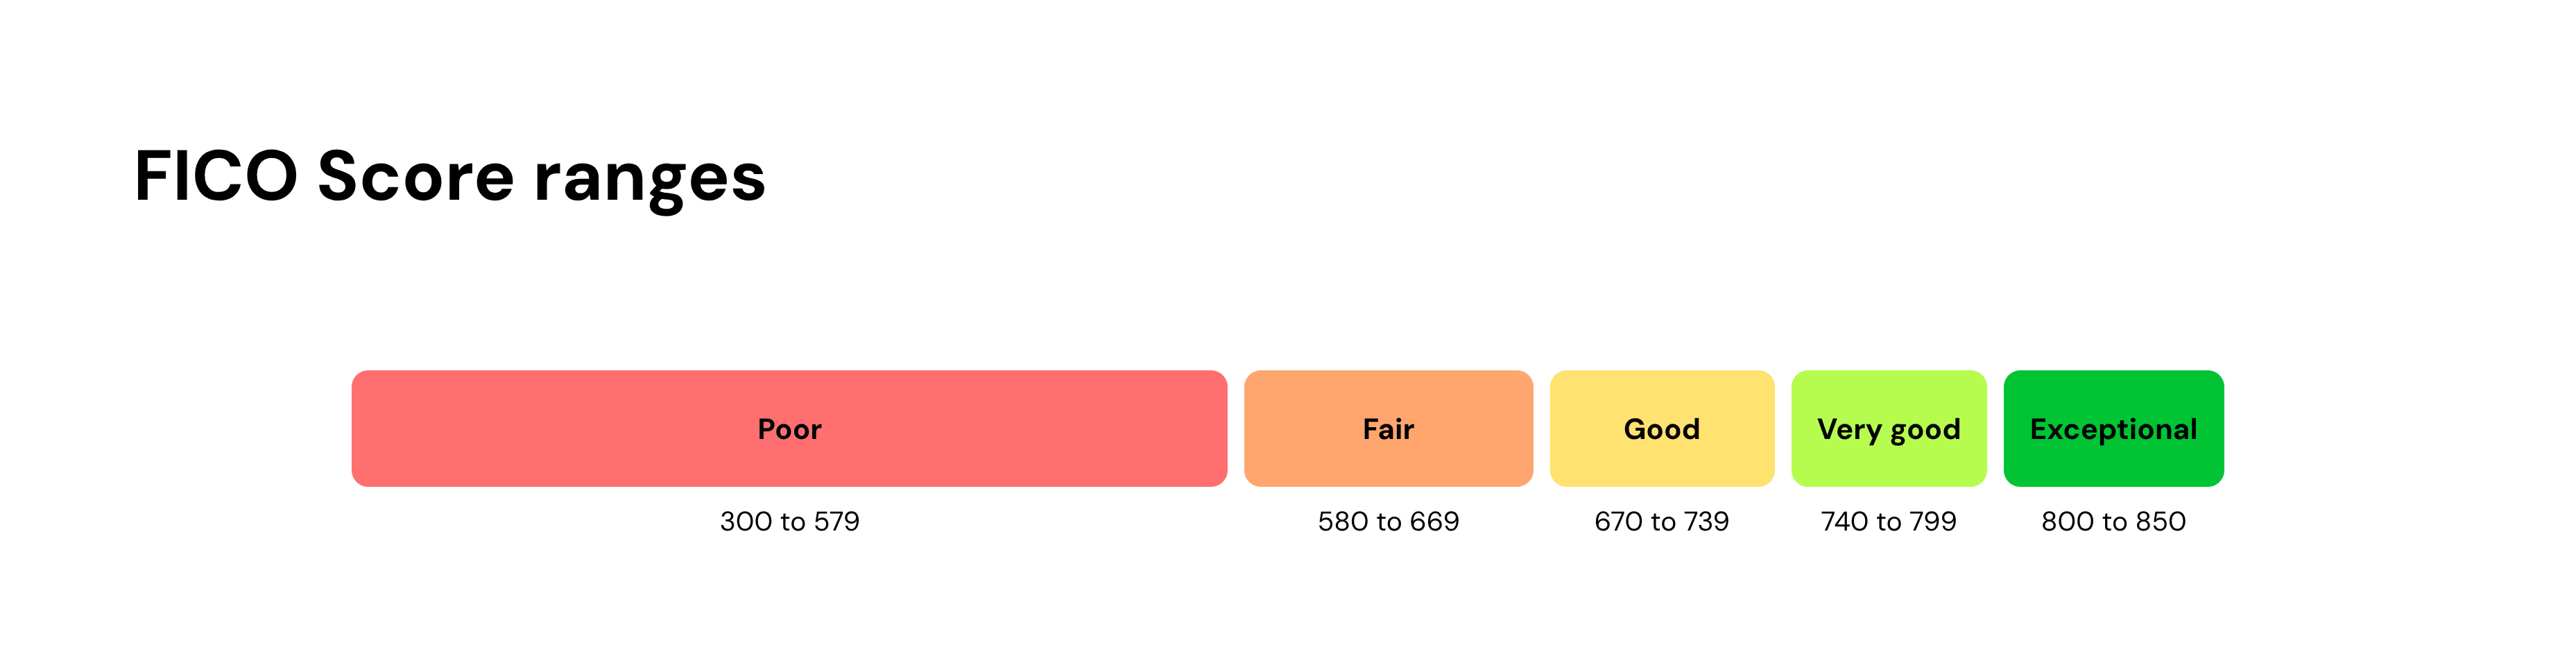
What stands between 684 and very good credit is usually one of these factors:
- Card balances. Using a large share of your available credit holds your score down, even if you pay in full each month. Your issuer reports the balance on your statement.
- History length. A score backed by a few years of accounts has less to go on than one backed by a decade. Length of credit history only grows with time.
- An older late payment. A payment 30 days or more late stays on your report for seven years. Its effect fades as on-time payments build behind it.
Read more >> What Can You Get Approved For With a 700 Credit Score?
What can you get approved for with a 684 credit score?
At 684, most lenders will approve you, so what's left is the price you get.
Credit cards
Rewards cards with cash back, points, or welcome offers are realistic at 684. Many 0% introductory APR cards are within reach too, though some premium travel cards look for higher scores. Before applying, check whether the issuer offers prequalification, which uses a soft credit check that doesn't affect your score.
A good score doesn't make card interest cheap. The average rate on card accounts charging interest is 22.15%, according to the Federal Reserve. An intro 0% period helps only if you pay the balance off before it ends.
Personal loans
Most personal lenders will approve a 684 score if your income and debt-to-income ratio (DTI) check out. You may not get a lender's lowest advertised rate, but you're past the high-rate tier. For comparison, the Federal Reserve's average for a 24-month bank personal loan is 11.86%. Federal credit unions can't charge more than 18% on most loans, so include them when you compare options.
Auto loans
At 684, you're in Experian's prime tier (661 to 780), 23 points above the cutoff. Your credit score plays a major role in the interest rate you're offered on a car loan. On a $20,000, 60-month new car loan at average rates, a prime borrower would pay about $1,000 more in interest than a super prime borrower. Experian sorts these tiers by VantageScore 4.0, so your FICO score may place you a little differently.
Manufacturer promotions like 0% financing may require higher scores, so ask the dealer what score a specific promotion needs before you count on it.
Use an auto loan calculator to check payment amounts before you sign.
Mortgages
At a 684 credit score, most mortgage types are open to you. Your score mainly decides what you pay, depending on the type:
- Conventional loans. Fannie Mae no longer sets a minimum score for loans run through its automated system, but lenders still set their own minimums. Fannie Mae does charge lenders an upfront fee on the loans it buys, based on your score and down payment. With 20% down, the fee is 1.75% of the loan amount for scores of 680 to 699, compared with 1.375% at 700 to 719 and 0.375% at 780+. On a $200,000 loan, the fee at 684 is $3,500, paid through a higher rate or more cash at closing. Reaching 700 would cut it by about $750.
- FHA loans. Borrowers with scores of 580 or higher can qualify with 3.5% down. On a $250,000 home, that's $8,750 up front. Each lender can set higher minimums. If your down payment is small, get an FHA quote alongside a conventional one.
- Jumbo loans. These are for amounts above conventional loan limits. Each lender sets its own standards, usually stricter on score, income, and down payment, so 684 may fall short with some lenders.
Run the numbers >> Use Kikoff's mortgage calculator to estimate your monthly payment and plan your homebuying budget.
What interest rates can you expect with a 684 credit score?
Expect solid offers, but not a lender's best. The Federal Reserve's averages across all borrowers were 22.15% for card accounts charging interest and 11.86% for 24-month bank personal loans. At 684, your offers will likely land near those averages or a bit below them.
The next pricing cutoff is 700, 16 points away, where Fannie Mae's upfront mortgage fee drops a band. FICO's very good range starts at 740, 56 points away.
5 ways to raise a 684 credit score
- Check your credit reports for errors. You can get all three for free every week at AnnualCreditReport.com. If something is wrong, like an account that isn't yours, dispute it with the bureau. Disputing is free.
- Pay down card balances before the statement closes. Your issuer usually reports the statement balance, so paying early lowers the balance that reaches your report, even if you already pay in full.
- Pay every bill on time. Payment history is the biggest factor in your score, making up 35% of a FICO Score.
- Shop for rates within a tight window. FICO counts multiple auto, mortgage, or student loan inquiries made within a period of 14 to 45 days as one, depending on the FICO version. Credit card and personal loan applications each count separately.
- Think twice before closing a card. Closing one removes its credit limit, which can raise your credit utilization if you carry balances on other cards.
If your report is thin on accounts, adding one helps. A Kikoff Credit Account reports your payments to all three bureaus.
Read more >> What Is a Good Credit Score in 2026?
Bottom line
A credit score of 684 gets you approved for most cards, loans, and mortgages. From here, your score decides how much you pay. You're 16 points from 700, where Fannie Mae's upfront fee drops, and 56 points from very good credit in FICO's ranges.
Kikoff brings credit building, bill and rent reporting, AI-powered disputes, credit monitoring, and debt negotiation into one place. Sign up with no credit check. Plans start at $5 a month.
Frequently Asked Questions
Article Sources
Disclaimer: The information provided in this blog post is meant for informational purposes only and does not constitute financial advice.