With a 393 credit score, you can still get approved for a secured credit card, some auto loans, and small loans from some credit unions. Unsecured cards, most personal loans, and mortgages are mostly out of reach for now.
If a lender does approve you, you'll likely pay more, because your score sets your interest rate. The nearest milestone is 500, 107 points away. That's where FHA mortgages open up with 10% down.
Is 393 a poor credit score?
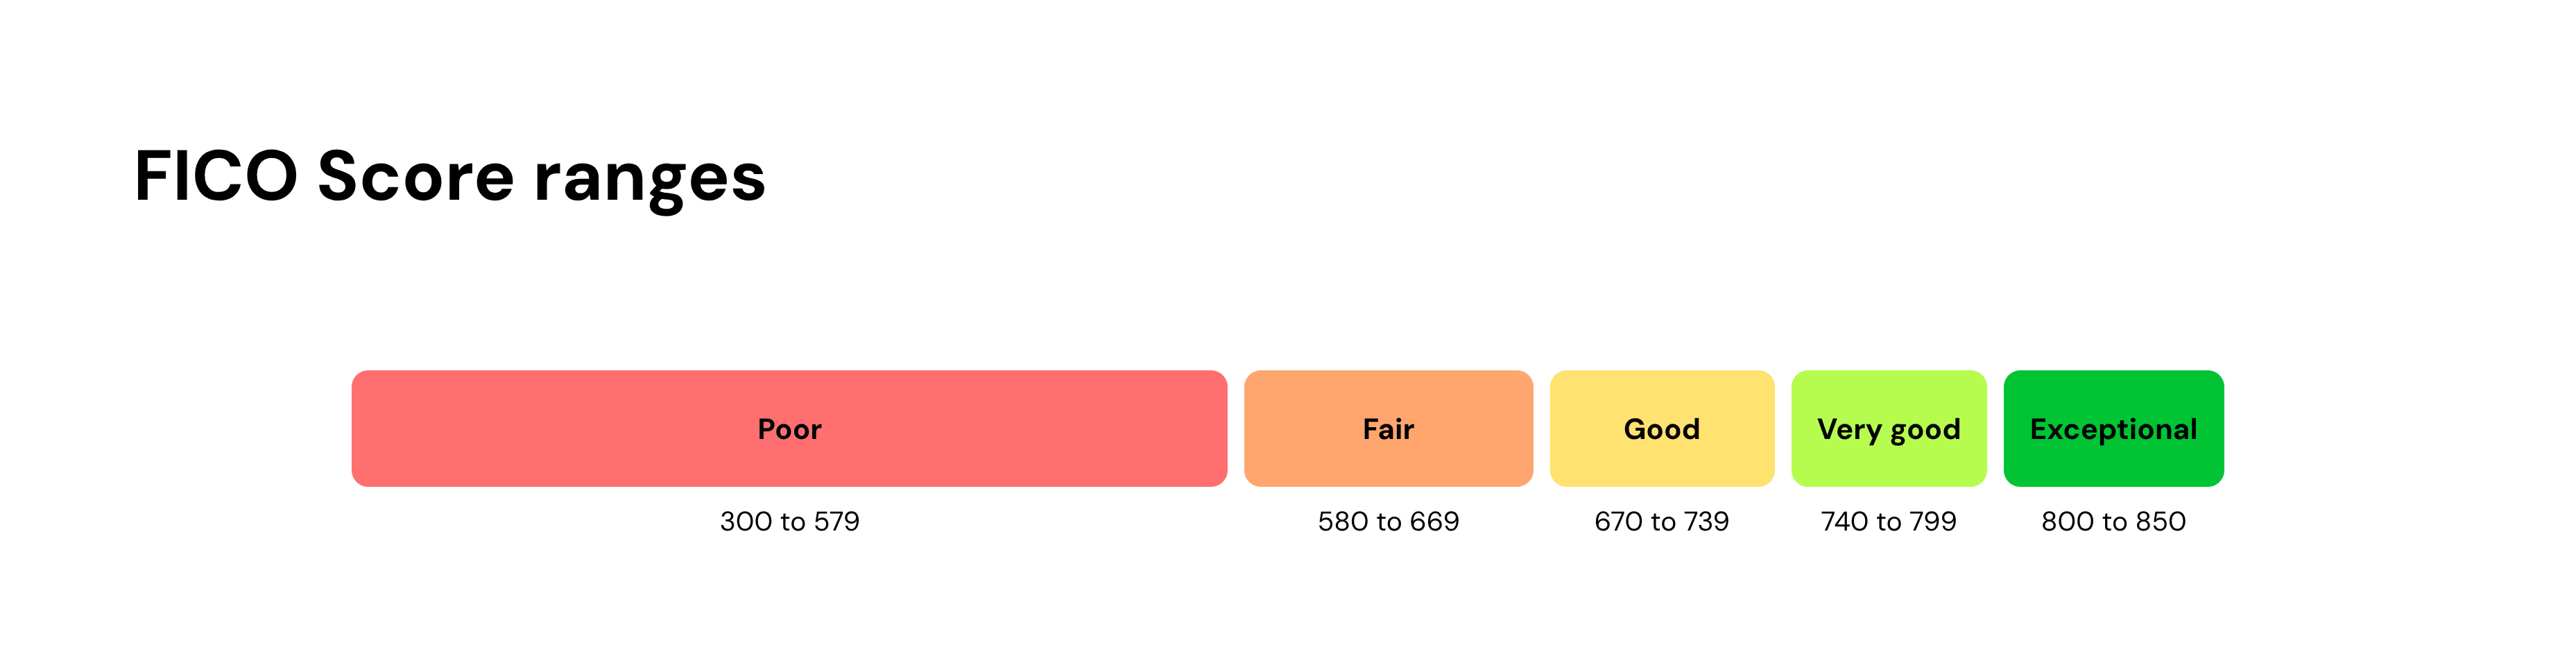
Yes. FICO's poor range runs from 300 to 579, and 393 is in the lower half of it. Fair credit starts at 580, 187 points up.
A score this low usually means your credit report includes negative marks like:
- Missed payments. A payment 30 days late gets reported and stays for seven years. Several of them, or one that stretched to 90 days, does more damage than a single slip.
- Accounts in collections. This is a debt handed off to a collection agency, often a medical bill or an old card balance. A collection also stays for seven years, counted from the original delinquency.
- Charged-off accounts. A lender wrote the debt off as a loss, usually after about four to six months of no payment. You still owe it, and it still reports to the bureaus.
Lenders read that as a high risk you won't repay. So approvals are harder, and when one comes through, the terms reflect the risk. Expect higher rates, bigger deposits, larger down payments, and, in some states, higher insurance premiums.
What can you get approved for with a 393 credit score?
Only a few financial products are realistic at 393. Knowing which ones can save you an application.
Credit cards
Most credit cards are unsecured, which means nothing of value backs them. Those cards are very hard to get with a 393 score.
A secured credit card is your most realistic option. With these cards, you put down a refundable deposit that usually becomes your credit limit. A $500 deposit gets you a $500 limit, for example. The issuer holds the deposit while the account is open and keeps it if you don't pay.
You generally get it back when you close the account in good standing, or when the issuer graduates you to an unsecured card after steady on-time payments.
A few subprime unsecured cards accept very low scores, but expect a low limit, a high rate, and fees.
Personal loans
A personal loan from a bank or online lender is very hard to get at 393. If you're approved, expect a small amount, a short term, and a high rate. For example, you might get $500 to repay over six months.
If you need a small loan, start with a credit union. Some federal credit unions offer payday alternative loans (PALs) of up to $2,000, repaid over one to 12 months. Application fees are capped at $20, and rates can't go higher than 28%. Approval isn't guaranteed, but it's worth asking.
That's much cheaper than a payday loan, where a typical $15 fee per $100 borrowed works out to an APR of nearly 400%.
Auto loans
An auto loan is one of the easier loans to get approved for with a 393 score.
That's because your car is the collateral: If you stop paying, the lender can take it back and sell it to satisfy the loan. That lowers the lender's risk, but it also means falling behind puts your car at risk.
A 393 score falls in Experian's deep subprime tier (300 to 500). Your credit score plays a major role in the interest rate you're offered on a car loan. On a $20,000, 60-month new car loan at average rates, a deep subprime borrower would pay about $6,900 more in interest than a super prime borrower. The next tier up, subprime, starts at 501. Experian sorts these tiers by VantageScore 4.0, so your FICO score may place you a little differently.
If banks and credit unions turn you down, buy here, pay here dealers finance cars themselves. Treat them as a last resort. They often require weekly or biweekly payments and charge much higher rates than traditional loans.
Use an auto loan calculator to check payment amounts before you sign.
Mortgages
A mortgage is very unlikely with a credit score of 393. FHA loans have the most flexible credit requirements, allowing borrowers with scores as low as 500 with at least 10% down. Lenders can set their own minimums higher.
If you want to buy a home, work on both building your score and saving money for a down payment. Our mortgage calculator can show what 10% down looks like on a home in your price range.
Read more >> What Can You Get Approved For With a 450 Credit Score?
What interest rates can you expect with a 393 credit score?
Expect rates near the top of whatever range a lender offers. In its G.19 release, the Federal Reserve reported an average of 22.15% for card accounts charging interest and 11.86% for 24-month bank personal loans. Those averages cover borrowers at every credit level. With a 393 score, your offers are likely to be higher.
The rate applies to the whole balance, so even a few percentage points add up. If you can wait to borrow, gaining 107 points gets you to 500, the FHA floor with 10% down.
5 ways to raise a 393 credit score
- Check your credit reports for errors. You can get all three for free every week at AnnualCreditReport.com. If something is wrong, like an account that isn't yours or a late payment you made on time, dispute it with the bureau. Disputing is free.
- Bring past-due accounts current. For accounts already in collections, it can be hard to know which to pay first. The National Foundation for Credit Counseling (NFCC) can connect you to free or low-cost counseling at 800-388-2227.
- Pay every current bill on time. Payment history is the biggest factor in your score, making up 35% of a FICO Score.
- Keep card balances low. Using less of your available credit helps your score.
- Apply only when you need to. Each application can add a hard inquiry, which takes a few points off for about a year. Where an issuer offers prequalification, it uses a soft credit check instead.
If your report is thin on positive accounts, adding one helps. A Kikoff Credit Account reports your payments to all three bureaus.
Progress is often slow at first. Late payments and collections lose weight as they age, and each month of on-time payments adds to your record.
Read more >> Which Debt Should I Pay Off First?
Bottom line
A 393 score still leaves you with a few options: secured cards, some auto loans, and credit union PALs. But your score doesn't just decide whether you're approved. It also sets the rate on every dollar you borrow.
Your first target is 500, 107 points up. It's where FHA mortgages open with 10% down.
Kikoff brings credit building, bill and rent reporting, AI-powered disputes, credit monitoring, and debt negotiation into one place. Sign up with no credit check. Plans start at $5 a month.
Frequently Asked Questions
Article Sources
Disclaimer: The information provided in this blog post is meant for informational purposes only and does not constitute financial advice.