With a 758 credit score, you can likely get approved for premium rewards cards, low-rate personal loans, auto loans, and most mortgages, as long as your income and debts support what you're borrowing. A 758 is very good credit. You're also 2 points below 760, where Fannie Mae's mortgage fee with 20% down drops by about $500 on a $200,000 loan.
Is 758 a good credit score?
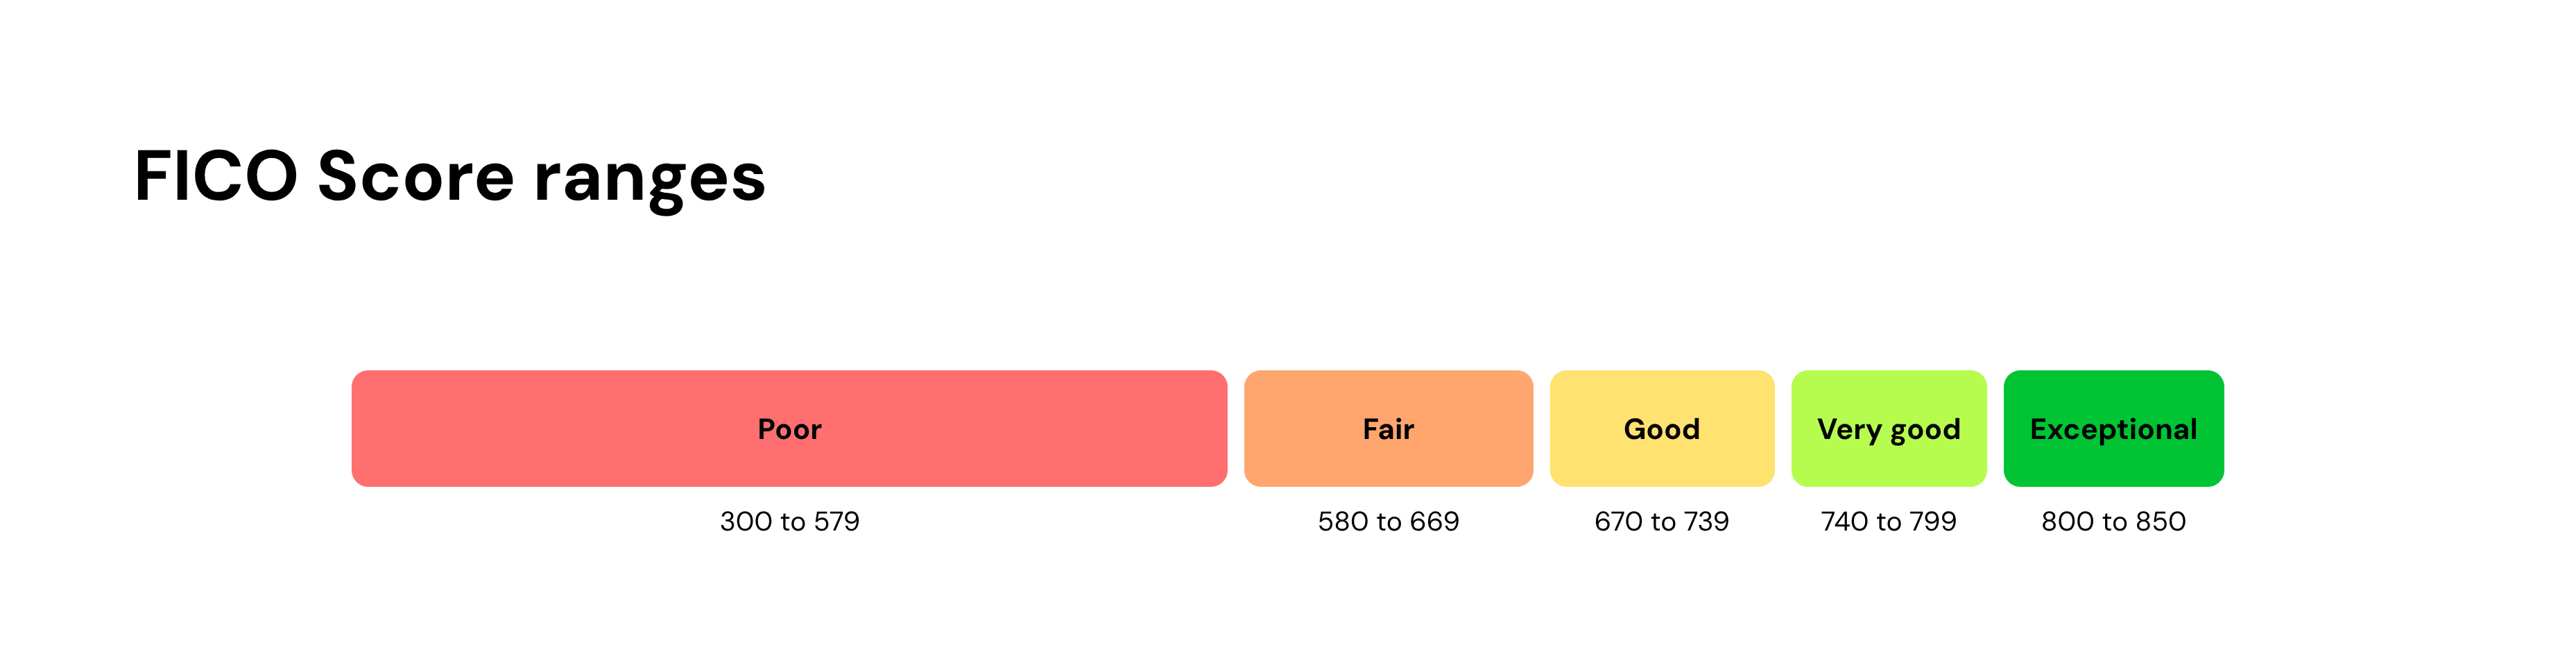
Yes. FICO's very good range runs from 740 to 799, and 758 is in the lower half of it.
A score this high usually reflects a long run of on-time payments, low card balances, and few recent applications. What separates 758 from the top pricing tiers is usually small, like a month's reported balance, a recent hard inquiry, or a few more years of history.
Read more >> What Is a Good Credit Score in 2026?
What can you get approved for with a 758 credit score?
At 758, your credit usually isn't what stands between you and approval. Lenders will look harder at your income, your job history, and your debt-to-income ratio (DTI).
Credit cards
Premium cards with travel rewards, high credit limits, and large sign-up bonuses are realistic at 758. So are long 0% intro APR periods.
Since you'll likely qualify for several, compare them on what you'll actually use: travel perks, cash back on everyday spending, bonus categories, or how long the intro period lasts. Get prequalified where you can. Prequalification uses a soft credit check that doesn't harm your credit. Only the application itself triggers a hard inquiry.
Personal loans
Most personal lenders will approve a 758 if your income and DTI support the loan. Expect offers in the lower part of a lender's advertised range.
The Federal Reserve's average for a 24-month bank personal loan is 11.86%, and a 758 borrower can often get offers below it. Federal credit unions can't charge more than 18% on most loans.
Auto loans
At 758, you're in Experian's prime tier (661 to 780), 23 points short of super prime at 781. On a $20,000, 60-month new car loan at average rates, a prime borrower would pay about $1,000 more in interest than a super prime borrower. Experian sorts these tiers by VantageScore 4.0, so your FICO score may place you a little differently.
Manufacturer promotions, like 0% financing, may be within reach. Ask the dealer what score a specific promotion requires. Before you visit a dealer, get preapproved by a bank or credit union. That gives you a rate to compare against the dealer's offer and any promotion.
Use an auto loan calculator to check payment amounts before you sign.
Mortgages
At 758, most mortgage types are open to you, and you're 2 points from Fannie Mae's next fee band:
- Conventional loans. Fannie Mae charges lenders an upfront fee on the loans it buys, based on your score and down payment. With 20% down, the fee is 0.875% of the loan amount at 740 to 759, 0.625% at 760 to 779, and 0.375% at 780+. On a $200,000 loan, that's $1,750 at your score, $1,250 at 760, and $750 at 780. You'd see the difference in your rate or your closing costs.
- FHA loans. These loans are an option, but they carry their own mortgage insurance premium. Borrowers with scores of 580 or higher can qualify with 3.5% down, and each lender can set higher minimums. At 758, compare an FHA quote with a conventional one, especially if your down payment is small.
- Jumbo loans. Each lender sets its own score, income, and reserve requirements for loans above conventional limits. A 758 meets many of them, but ask each lender.
Small rate differences add up on a mortgage. For example, on a $300,000, 30-year loan, 6.0% instead of 6.5% saves about $98 a month, or about $35,000 over the life of the loan.
Run the numbers >> Use Kikoff's mortgage calculator to estimate your monthly payment and plan your homebuying budget.
What interest rates can you expect with a 758 credit score?
Expect strong offers, close to the best a lender advertises. Exact rates depend on the lender, the loan, and market conditions. The Federal Reserve's averages across all borrowers were 22.15% for card accounts charging interest and 11.86% for 24-month bank personal loans. At 758, your offers will likely come in below both.
The closest pricing cutoff is 760, 2 points up: Fannie Mae's fee there is about $500 lower on a $200,000 loan with 20% down. After that come 780 for Fannie Mae's top fee band and 781 for Experian's super prime auto tier. Reaching 800 changes what you're called more than your price.
5 ways to protect or raise a 758 credit score
- Check your reports before a big application. You can get all three for free every week at AnnualCreditReport.com. If anything is wrong, like an account that isn't yours, dispute it with the bureau reporting it.
- Keep reported balances low. Your issuer usually reports your statement balance. Paying it down before the statement closes keeps your utilization low, even if you already pay in full.
- Never miss a payment. Payment history makes up 35% of a FICO Score.
- Limit new applications. Each hard inquiry can take a few points off for about a year. When you're shopping for an auto loan, mortgage, or student loan, keep it within a tight window. FICO counts those inquiries as one if they fall within 14 to 45 days, depending on the FICO version. Card and personal loan applications each count separately.
- Think twice before closing a card. Closing one removes its credit limit, which can raise your utilization if you carry balances on other cards.
If your report is thin on accounts, adding one helps. A Kikoff Credit Account reports your payments to all three bureaus.
Read more >> What Can You Get Approved For With a 770 Credit Score?
Bottom line
A 758 score gets you approved for nearly everything, at rates close to a lender's best. Your nearest cutoff is just 2 points away: At 760, Fannie Mae's fee drops by about $500 on a $200,000 loan with 20% down. Past that, 780 and 781 bring the best mortgage and auto pricing, so keep reported balances low and avoid unnecessary hard inquiries.
Kikoff brings credit building, bill and rent reporting, AI-powered disputes, credit monitoring, and debt negotiation into one place. Sign up with no credit check. Plans start at $5 a month.
Frequently Asked Questions
Article Sources
Disclaimer: The information provided in this blog post is meant for informational purposes only and does not constitute financial advice.