



With a 603 credit score, you can likely get approved for an auto loan, a fair-credit or secured credit card, a personal loan, or an FHA mortgage with 3.5% down. Not every lender will say yes, and you'll pay more than borrowers with good credit, because your score sets your rate. At 603, you're 58 points from prime auto rates and 67 points from good credit.
Is 603 a poor credit score?
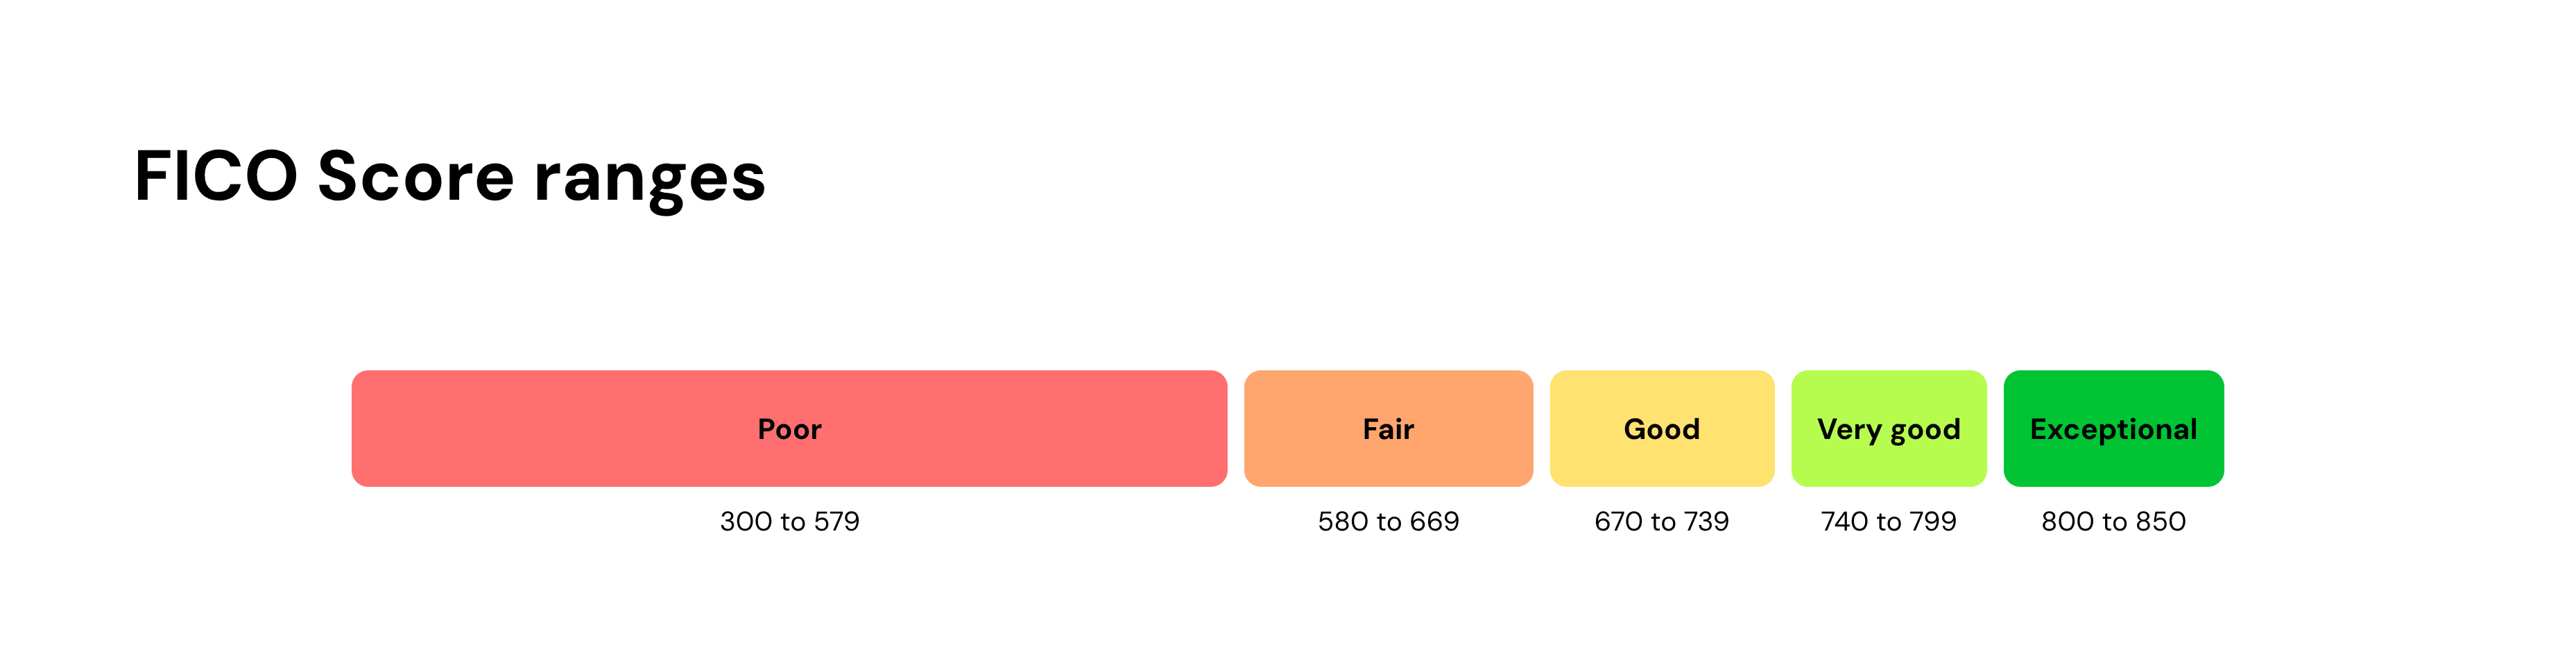
No. FICO's fair range runs from 580 to 669, so 603 sits in the lower half of it. At 670, you'd move into good credit.
A score in this range usually means your credit report shows one or more of these issues:
- A late payment. A payment 30 days or more late stays on your report for seven years. Its effect on your score shrinks as it ages, especially when newer on-time payments build behind it.
- High card balances. Using a large share of your available credit lowers your score. Unlike a late payment, this changes as soon as your balances come down.
- A short or thin credit history. A thin credit file, meaning a report with only a few accounts or accounts that haven't been open long, gives scoring models less to go on.
Many lenders will work with a 603 score. What changes is the terms, including higher rates, lower limits, and, in some states, higher car insurance premiums than borrowers with good credit get.
Read more >> What Can You Get Approved For With a 620 Credit Score?
What can you get approved for with a 603 credit score?
At 603, most types of credit are open to you, but not every lender will approve you, and prices run high. Knowing which products are realistic can save you an application.
Credit cards
Unsecured cards designed for fair credit are possible with a 603 credit score. Expect a modest limit and a higher APR than cards for good credit. Before applying, check whether the issuer offers prequalification, which uses a soft credit check that doesn't harm your credit.
If you're turned down, a secured credit card is a reliable option. With these cards, you put down a refundable deposit that usually becomes your credit limit. A $500 deposit gets you a $500 limit, for example. You generally get it back if you close the account in good standing or are graduated to an unsecured card with steady on-time payments.
Personal loans
A personal loan is realistic at 603, but expect a smaller amount and a higher rate than a borrower with good credit would get. Start with a credit union if you belong to one or can join. Federal credit unions can't charge more than 18% on most loans. Some also offer payday alternative loans (PALs) of up to $2,000 with rates capped at 28%.
Online lenders and banks that work with fair credit are another option. Compare offers using prequalification, which uses a soft check, so only the lender you choose runs a hard credit check. Any of these is cheaper than a payday loan, where a typical $15 fee per $100 borrowed works out to an APR of almost 400%.
Auto loans
Approval for a car loan at 603 is often easier than approval for a personal loan. That's because your car is the collateral: If you stop paying, the lender can take it back and sell it. That lowers the lender's risk, but it also means falling behind puts your car at risk.
A 603 score falls in Experian's near prime tier (601 to 660). Your credit score plays a major role in the interest rate you're offered on a car loan. On a $20,000, 60-month new car loan at average rates, a near prime borrower would pay about $3,000 more in interest than a super prime borrower, and about $2,000 more than a prime borrower. Experian sorts these tiers by VantageScore 4.0, so your FICO score may place you a little differently.
At 603, you're only 2 points above the near prime cutoff of 601. Dropping below 601 would put you in Experian's subprime tier, where the gap with super prime grows to about $5,300.
Use an auto loan calculator to check payment amounts before you sign.
Mortgages
With a 603 credit score, a mortgage is within reach, with costs and odds depending on the type:
- FHA loans. Borrowers with scores of 580 or higher can qualify with 3.5% down. On a $250,000 home, that's $8,750 up front. Each lender can set higher minimums.
- Conventional loans. Fannie Mae no longer sets a minimum score for loans run through its automated system, but lenders still set their own, and some will want more than 603. Fannie Mae also charges lenders an upfront fee on the loans it buys, based on your score and down payment. At 20% down, the fee for scores of 639 and below is 2.75% of the loan amount, compared with 0.375% at 780 or higher. On a $200,000 loan, that's $5,500 versus $750, and you'd pay it through a higher rate or more cash at closing. The next fee band starts at 640, where the fee drops to 2.25%. That's about $1,000 less on a $200,000 loan.
- USDA loans. These are for homes in eligible rural and suburban areas with income limits. USDA doesn't set a minimum score, but lenders typically look for 620 to 640. At 603, most lenders will likely want a higher score.
A lender can show you an FHA and a conventional quote side by side. Our mortgage calculator can help you compare the monthly payments.
What interest rates can you expect with a 603 credit score?
Expect rates above what borrowers with good credit get. The Federal Reserve's averages across all borrowers were 22.15% for card accounts charging interest and 11.86% for 24-month bank personal loans. Those averages cover borrowers at every credit level. With a 603 score, your offers will likely come in above them.
The rate applies to the whole balance, so a few points add up. If you can wait to borrow, 58 more points would move you into the prime tier for auto loans, and 67 would get you to good credit.
5 ways to raise a 603 credit score
- Check your credit reports for errors. You can get all three for free every week at AnnualCreditReport.com. If something is wrong, like an account that isn't yours or a late payment you made on time, dispute it with the bureau. Disputing is free.
- Bring any past-due accounts current, if you can. If you're juggling more than one, the National Foundation for Credit Counseling (NFCC) can connect you to free or low-cost counseling at 800-388-2227.
- Pay every bill on time. Payment history is the biggest factor in your score, making up 35% of a FICO Score.
- Pay down card balances. Using less of your available credit can raise your score as soon as your issuer reports the lower balance, but that boost lasts only while the balances stay low.
- Apply only when you need to. Each application can add a hard inquiry, which takes a few points off for about a year. Prequalify first where you can.
If your report is thin on accounts, adding one helps. A Kikoff Credit Account reports your payments to all three bureaus.
Read more >> How to Build Credit
Bottom line
At 603, many lenders will approve you, and an FHA mortgage with 3.5% down is open to you. What your score decides now is mostly the price. Reaching prime auto rates takes 58 more points, and good credit in FICO's ranges takes 67.
Kikoff brings credit building, bill and rent reporting, AI-powered disputes, credit monitoring, and debt negotiation into one place. Sign up with no credit check. Plans start at $5 a month.
Frequently Asked Questions
Article Sources
Disclaimer: The information provided in this blog post is meant for informational purposes only and does not constitute financial advice.