


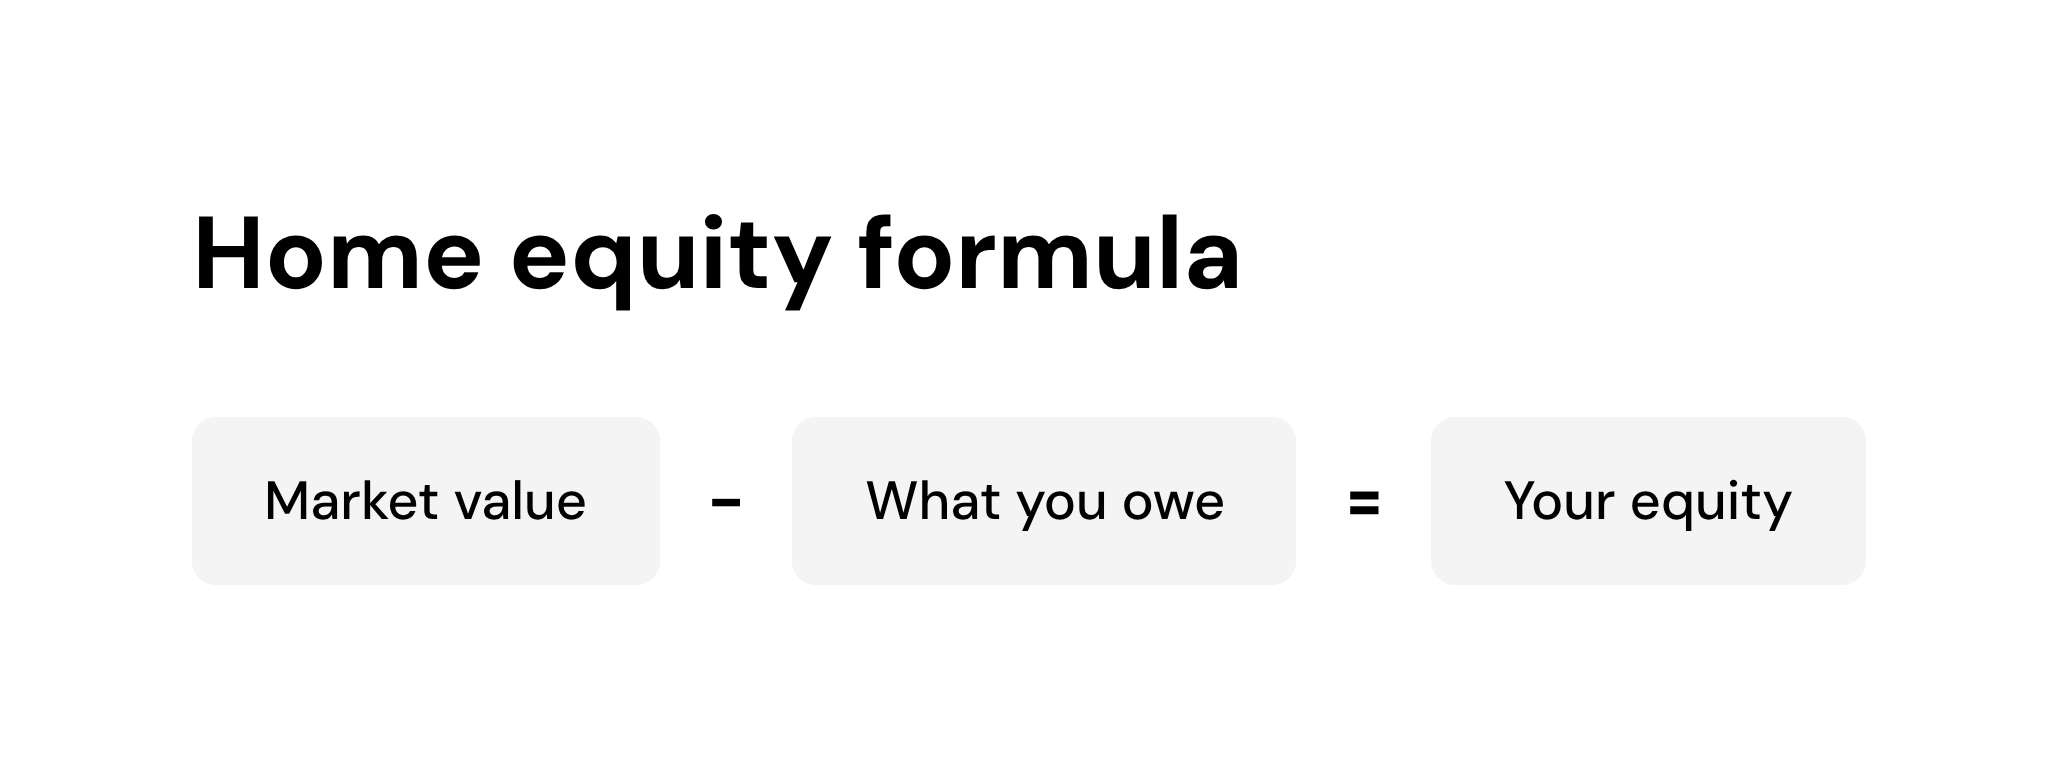
To figure out your home equity, take what your home is worth today and subtract what you still owe on it. If your home could sell for $350,000 and you owe $210,000, you have $140,000 in equity.
That’s the easy part. The trickier part is tracking down the right two numbers. Your home’s value is an estimate until an appraiser weighs in, and the balance on your statement isn’t always everything you owe.
How to calculate home equity
You only need two numbers: what your home would sell for today, and the total of every loan that uses your home as collateral. Subtract the second from the first, and what’s left is your equity.
The home equity formula
Home equity = current market value − all loans secured by your home
Watch the words “all loans.” It’s easy to count only your main mortgage. But a second mortgage, a home equity loan, or a home equity line of credit (HELOC) counts too, and each one lowers your equity.
Running the numbers: How home equity works
Let’s say your home’s market value is $350,000, and you still owe $210,000 on your mortgage.
Now say you also have a HELOC with a $20,000 balance. That brings what you owe to $230,000, so your equity drops to $120,000, or about 34% of your home’s value.
You might also hear lenders mention your loan-to-value ratio, or LTV. It’s the other side of your equity percentage: what you owe divided by what your home is worth. In the first example, that’s $210,000 divided by $350,000 — or 60%.
So 40% equity and 60% LTV describe the same home from opposite ends.
Read more >> How to Build Home Equity Faster

How to find your home’s current market value
Your market value is what a buyer would likely pay for your home now, which can be quite different from what you paid for it. There are three ways to estimate it. The more hands-on the method, the more precise the number.
Online home value estimators
Real estate websites can estimate your home’s value in seconds, using public records, past sales, and nearby listings. They’re a free, easy way to get a ballpark number.
Just don’t treat any one estimate as the final word. It can’t stand in for a formal appraisal, and it won’t show any updates or additions you never reported to your local tax assessor.
Try two or three sites. If they don’t agree, go by the range rather than the highest number.
Comparative market analysis
A comparative market analysis (CMA) is a report from a real estate agent. It compares your home with similar homes that recently sold nearby. Because an agent knows the area, they can account for things a website misses, like a new roof or a busy street.
Before you get one, it’s fair to ask about the fee and whether it comes with any obligation to list with that agent.
Professional appraisal
A licensed appraiser comes to your home, looks at its condition, and compares it with recent sales to set a formal value. If you borrow against your home or refinance, your lender will usually order its own valuation, often an appraisal, and that’s the number that counts for a loan.
If you’re just curious, an appraisal may be more than you need. If you’re about to make a big decision based on your equity, it’s the most reliable number you can get.
Read more >> How to Get Equity Out of a Paid-Off Home
How to find your remaining mortgage balance
Your monthly mortgage statement or your servicer’s online account shows your outstanding principal, or the amount you still owe on the loan itself. That’s close enough for a quick estimate. Your servicer is the company you send your payments to, and it may not be the same company that gave you the loan.
When you want the most exact number, ask your servicer for a payoff amount. It isn’t the same as your current balance: it adds any interest owed through the day you’d pay the loan off, and it can include unpaid fees.
Next, add up anything else that uses your home as collateral:
- A second mortgage or home equity loan. You’ll find the balance on that loan’s statement.
- A HELOC. Count only what you’ve borrowed so far, not your full credit limit.
- Any other liens. A lien is a legal claim on your property, such as one for unpaid property taxes. Your county recorder’s office keeps property records you can check.
Read more >> How To Lower Your Monthly Mortgage Payment
How to find your servicer and your balance
If you don’t have a recent statement, your servicer’s name is on your last payment confirmation or your annual escrow statement. Your loan may have been transferred since closing, so it isn’t necessarily the lender you originally borrowed from.
Call the number on their website and ask two things: your current principal balance, and a payoff statement. The payoff is the more useful of the two, because it includes interest through the date you’d pay, which the balance alone doesn’t.
What affects your home equity over time
Your equity changes any time either side of the formula changes. You have a lot of say over one side, and much less over the other.
Paying down your mortgage
Every on-time payment lowers what you owe, so your equity grows even if your home’s value stays the same. Don’t be surprised if it feels slow at first. Early in a loan, more of each payment goes to interest, so this part builds gradually.
Here’s one that trips people up. If you pay private mortgage insurance (PMI), the rules for canceling it use your home’s original value, not what it’s worth today. You can generally ask your servicer to cancel PMI once your balance is scheduled to reach 80% of that original value, as long as you’re current on payments and have a good payment history. Your servicer may also ask for proof, like an appraisal, that your home hasn’t lost value. In general, your servicer must end it automatically at 78%. FHA and VA loans follow different rules.
If your home has gone up in value, ask your servicer whether a new appraisal counts toward canceling PMI.
Changes in property value
When home prices in your area go up, your equity goes up with them. When they fall, it shrinks. That’s why your equity can change even when you haven’t touched your loan.
Prices can also dip below what you owe. About 2.1% of mortgages were underwater in the second quarter of 2026, according to Cotality, a property data company.
Home improvements
A new kitchen or bathroom can add value to your home, but most projects don’t add as much as they cost. In the 2025 Cost vs. Value report, only five of 28 remodeling projects were estimated to return more than their cost at resale.
That doesn’t mean a project isn’t worth doing. If it makes your home better to live in, that counts too. Just don’t count the full price as new equity. And if you pay for the work with a loan secured by your home, remember to add that balance to what you owe.
Read more >> Home Equity Loan vs. Home Improvement Loan: What's the Difference?
Why your home equity matters
Your equity is the part of your home’s value that’s truly yours. Homeowners with a mortgage had about $310,000 in equity on average in mid-2026, Cotality reports. Knowing your own number helps with three big decisions:
- When you sell. Think of your equity as roughly what’s left after the sale pays off your loans. Selling costs and your exact payoff amount come out first, so the check you walk away with is usually smaller than your equity on paper.
- When you want to drop PMI. How your balance compares with your home’s original value decides when PMI can end.
- When you borrow against it. A home equity loan or HELOC lets you borrow against your equity. If you still have a mortgage, either one is a second loan you’d repay on top of it, and your home is the collateral. If you fall behind, the lender can foreclose your home.
Lenders also won’t let you borrow all of your equity. Each one sets a limit on how much you can owe, your mortgage plus the new loan, as a share of your home’s value, usually 80% to 85%. Lenders call this your combined loan-to-value ratio, or CLTV.
On that same $350,000 home, an 80% cap means your total debt can’t be higher than $280,000. Subtract the $210,000 mortgage, and you could borrow up to $70,000, or half of your $140,000 equity.
The cap varies, so ask each lender the same question: What’s the most I can owe in total as a percentage of my home’s value?
Read more >> Can You Get a Home Equity Loan with Bad Credit?
Know your number? Here’s who to call next
If you’re thinking of borrowing against your home: The house secures the debt. That’s why the rate is lower than a card's, and why falling behind can cost you the house. A HUD-approved housing counselor will go through the numbers with you before you sign.
If you owe more than your home is worth: Day to day, it’s the same payment, same progress. It matters when you sell or refinance, since most options need equity you don’t have. A housing counselor can walk you through what’s open to you.
Counseling is free or low cost. Call HUD 800-569-4287 or find a HUD counselor near you. You don’t need to be in trouble to call.
Bottom line
Your home equity is your home’s market value minus everything you owe on it. Use your payoff amount for what you owe. For what your home is worth, an online estimate is a fine start, and an appraisal is the number to use when it needs to hold up.
If you ever borrow against that equity, it isn’t the only thing a lender weighs. Your credit helps decide whether you’re approved and what rate you’re offered. If you have a few months before you apply, a Kikoff Credit Account reports your on-time payments to Equifax, Experian, and TransUnion. There’s no credit check to sign up, and plans start at $5 a month. If you’re already applying, check with your lender before opening any new account.
Frequently Asked Questions
Article Sources
Disclaimer: The information provided in this blog post is meant for informational purposes only and does not constitute financial advice.