

Freelancing offers flexibility and independence, but an unpredictable paycheck can make financial planning harder. When client payments arrive late or work slows down, keeping up with credit payments can take extra preparation.
You can build credit without a W-2 job. Start with accounts that report your payments, keep borrowing manageable, and plan for the gaps between invoices.
How to build credit as a freelancer: the fundamentals
Whether you’re a freelancer or a traditional W-2 employee, the basics of building credit are the same:
- Pay on time: Make at least the required payment on your credit accounts by each due date.
- Check reporting: Confirm which credit bureaus receive your account activity. Not every bill you pay appears on your credit reports.
- Keep balances low: Leave room on your credit cards and avoid spending more than you can repay.
- Build gradually: Choose accounts you can manage during slower months, not just your busiest ones.
There is no guaranteed timeline for building credit. Your progress depends on your starting history, the accounts reporting, and how you manage them.
If your credit history is limited or you’ve had financial setbacks, a credit-building product may be an option. Compare its total cost, payment requirements, and reporting practices before signing up.
How credit works for self-employed freelancers
Your income and employment history do not factor into your FICO Scores. Employment information may appear on a credit report, but being self-employed does not itself count against your score.
Credit bureaus collect account information, and scoring models use that information to calculate scores. FICO considers these main categories:
- Payment history
- Amounts owed, including credit utilization
- Length of credit history
- Credit mix, or the types of accounts you have
- New credit, including recent inquiries and newly opened accounts
As a freelancer, your income might fluctuate from month to month. That fluctuation does not directly affect your score, but missed payments or growing balances can.
Credit utilization measures how much of your available revolving credit you’re using. Lower reported balances are generally better for credit scoring; 30% is not a target you need to reach or a boundary that guarantees a particular result.
You also do not need to pay interest to build credit. Options include:
- Having eligible rent payments reported through your landlord or a reporting service
- Using a credit-building account that reports payments
- Using a credit card for affordable purchases and paying the full statement balance by the due date
Before choosing a product, check its fees and which bureaus it reports to. Not every scoring model considers rent payments, and an interest-free product can still come with other costs.
Read more >> How to Read a Credit Report
Can you build credit without a W-2?
Yes. You do not need a W-2 to have a credit history. What matters for building that history is the account information reported about you.
Applying for credit is a separate question. A lender may ask you to document your freelance income, even though income is not part of your credit score. For example, a mortgage lender may request additional documentation when you are self-employed or have irregular income.
To prepare for an application and manage your accounts:
- Ask which income documents the provider accepts before applying.
- Keep records of income received and business expenses.
- Choose payments you can afford during a slower month.
- Avoid unnecessary credit applications.
- Keep business and personal finances separate where practical to make budgeting and recordkeeping easier.
Separating your finances does not build personal credit by itself, but it can help you see what is available for household bills after business costs.
Kikoff’s Credit Account is a free revolving credit line used only for purchases in the Kikoff Store. It charges no interest and reports your on-time payments to all three credit bureaus, with no hard credit check to sign up. Approval and eligibility requirements still apply.
Common mistakes to avoid
When your income varies, a payment that looks manageable during a busy month can become harder to cover later. Watch out for these mistakes:
- Applying for several accounts at once
- Choosing a product without checking its fees and reporting practices
- Counting on an unpaid invoice to cover an upcoming bill
- Setting up autopay without monitoring the linked account’s balance
- Closing a credit card without considering its costs and effect on available credit
During stronger months, set aside money for upcoming bills when you can, after accounting for business expenses and taxes. Payment reminders can help you track due dates even when your income does not follow a regular schedule.
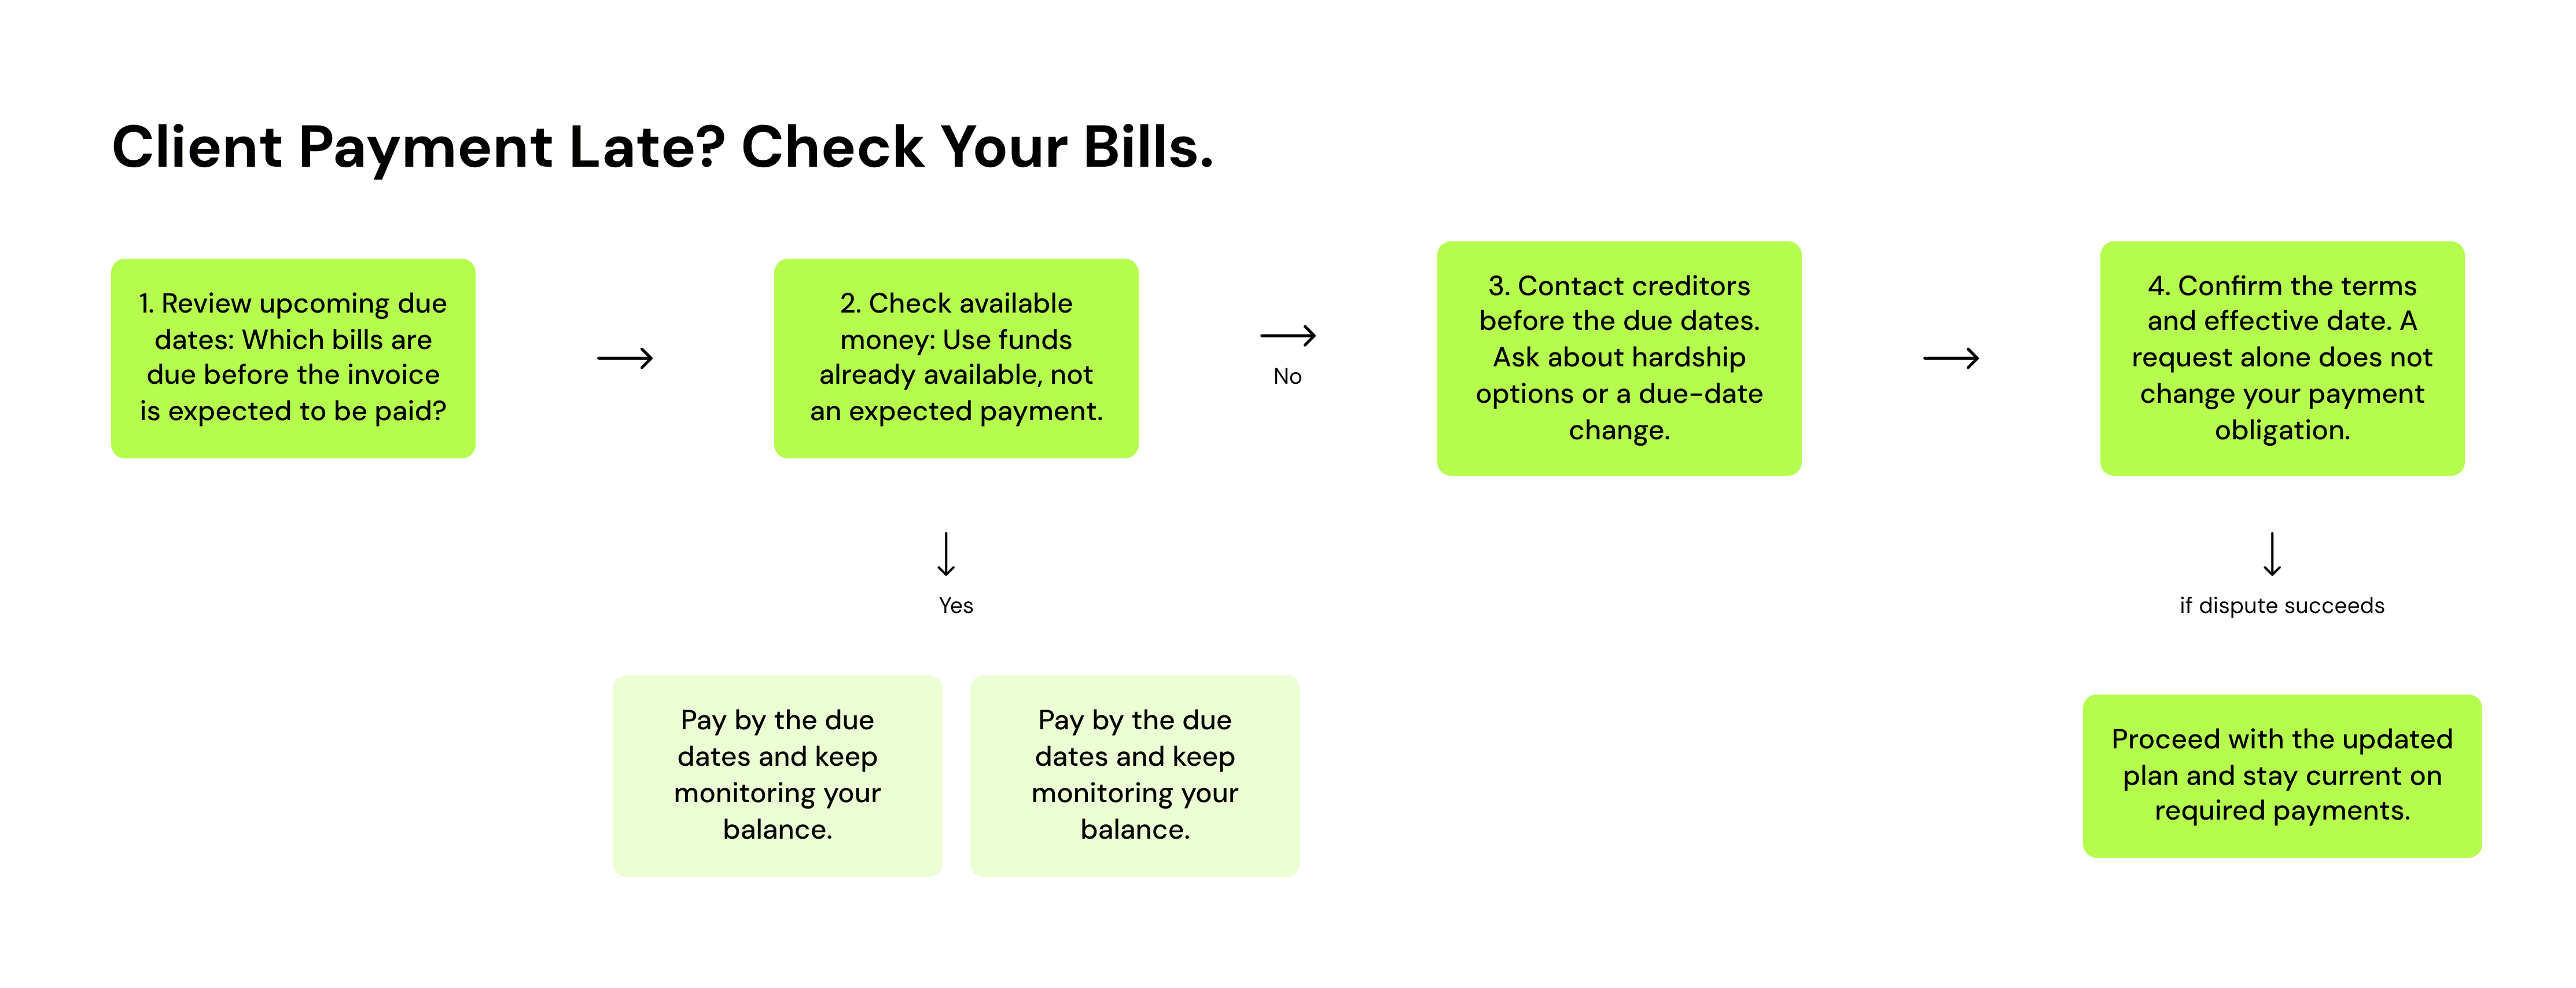
If a client payment is late: Check which bills are due before the money is expected to arrive. If you cannot make a credit payment, contact the creditor before the due date and ask about hardship options or whether a different due date is available. Confirm when any change takes effect.
Keeping a paid-off card open can preserve available credit, but it is not always worth paying an annual fee or keeping an account that encourages overspending. Closed accounts in good standing can continue contributing to your credit history while they remain on your reports.
If a card is expensive to keep, ask whether the issuer offers a no-fee version. Consider your budget alongside any potential credit effect.
Read more >> What Happens if You Miss a Credit Card Payment
Bottom line
You don’t need a regular paycheck to build credit, but you do need a payment plan that can handle uneven income. Focus on manageable accounts, on-time payments, and keeping enough room in your budget for slower months.
Before adding an account, compare its costs and confirm what it reports. You do not need to borrow more or pay interest just to build a credit history.
Kikoff’s Credit Account reports your on-time payments to all three credit bureaus, with no hard credit check to sign up. If it fits your budget, start building a positive credit history with Kikoff.
Frequently Asked Questions
Disclaimer: The information provided in this blog post is meant for informational purposes only and does not constitute financial advice.