Opening your first checking account means choosing a bank or credit union, bringing an ID and your Social Security number or ITIN, and making a first deposit. Before you pick one, check two things that are easy to miss: the monthly fee and the overdraft policy.
6 steps to open your first checking account
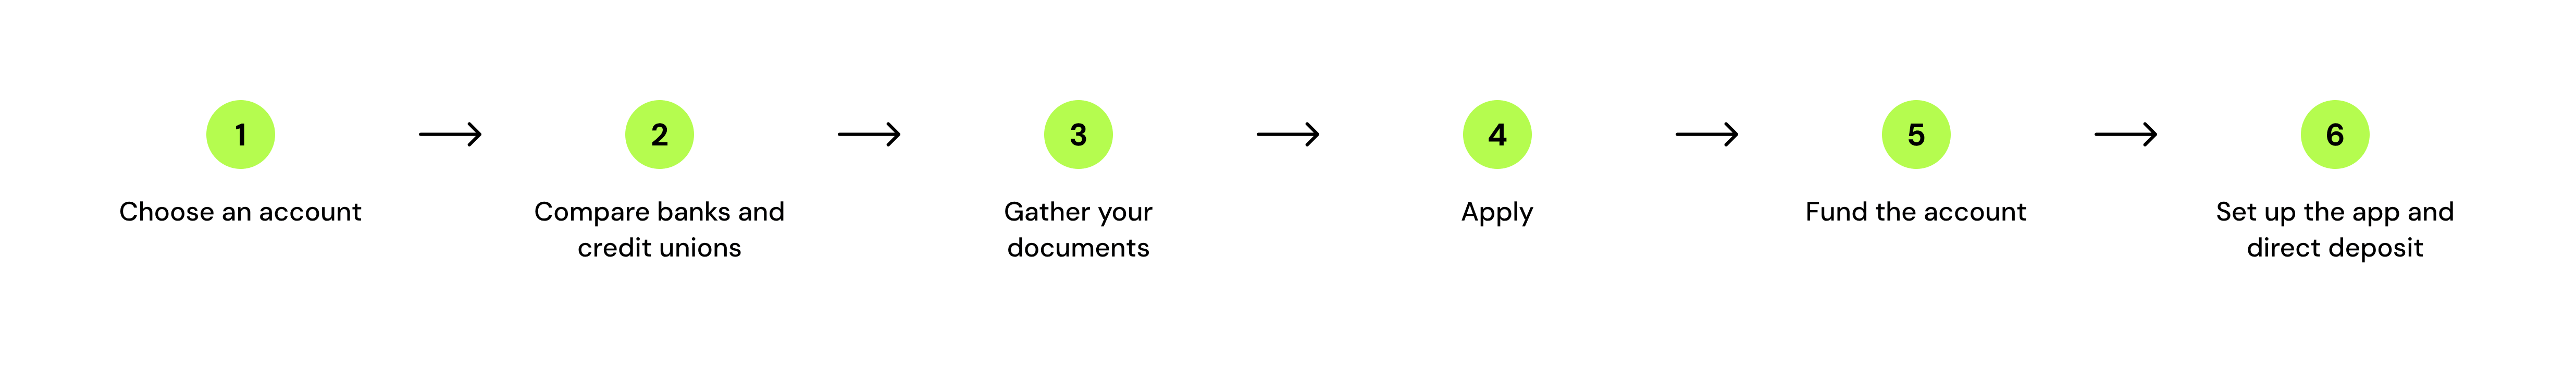
1. Choose the type of checking account
A standard checking account fits most people. Look for one with no monthly fee, often called free checking.
- If you've had trouble with a bank account before, some banks and credit unions offer lower-risk accounts called second-chance accounts, which are built to prevent overdrafts.
- If you're under 18, you'll usually need a parent or guardian to open a joint or custodial account with you.
2. Compare banks, credit unions, and online banks
- Big banks tend to have more branches and larger ATM networks for easy access to your money.
- Credit unions may charge lower fees for members, with membership based on where you live, work, or go to school.
- Online banks often have low or no monthly fees, but without local branches, many can’t take cash.
3. Gather your documents
Most banks and credit unions ask for:
- A government-issued photo ID, like a driver’s license, state ID or passport
- Your Social Security number or ITIN
- Your full name, date of birth, and address
- Your phone number and email
- Proof of address, if the bank can’t verify it electronically
4. Apply online or in person
You can often apply online in a few minutes. If this is your first account, applying at a branch is a good option, because you can ask questions as you go. Some banks also ask you to visit a branch to finish opening the account.
The bank may check your banking history, but it won’t check your credit score.
5. Fund your account
Make your first deposit with cash, a check, or a transfer from another account. Some accounts have no minimum opening deposit, and others ask for a small one. Check before you apply. Even if there's no minimum, a small deposit gives you a cushion against your first fee or overdraft.
6. Set up the app and direct deposit
Download the bank's app, set up your login, and turn on balance alerts. Then ask your employer about direct deposit. It's usually the fastest way to get paid, and some banks waive the monthly fee when your paycheck is deposited directly.
Read more >> Checking vs. Savings: What's the Difference?
What to look for in your first checking account
Monthly fees (and how to avoid them)
Many checking accounts have no monthly fee. If an account you like charges one, find out exactly how to waive it. Sometimes all it takes is setting up direct deposit or keeping a minimum balance. Just make sure you can realistically meet any requirement.
ATM access
Using an ATM outside your bank's network can cost you twice: once from the ATM owner and once from your bank. Before you choose, check whether there are in-network ATMs near where you live and work, and ask whether the bank reimburses out-of-network fees.
Minimum balance requirements
Some accounts charge a fee if your balance drops below a set amount. If your balance tends to run low near payday, choose an account with no minimum.
Overdraft policies
An overdraft happens when you spend more than you have in your account. How your bank handles it depends on the type of payment:
- ATM withdrawals and everyday debit purchases. Federal law prohibits banks from charging you an overdraft fee on these transactions unless you’ve opted in to overdraft protection. If you don't opt in, the bank won't charge an overdraft fee on these transactions, and it can decline them instead.
- Checks and automatic payments. These payments can still overdraw your account and trigger a fee, even if you didn't opt in.
- Linked accounts. Some banks let you link a savings account to cover a shortfall, but there may still be a smaller transfer fee.
Ask the bank which of these it offers and what each one costs before you open the account.
Check that your account is insured. For a bank, search its name in the FDIC's BankFind Suite. For a credit union, look it up in the NCUA's Credit Union Locator. For an app, look up the partner bank that holds your money, not the app's name.
Insured deposits are covered up to $250,000 per depositor, per FDIC-insured bank, for each account ownership category.
3 habits for your first account
- Read the fee schedule once. Know your monthly fee, ATM fees, and overdraft fees before you need to.
- Turn on low-balance alerts. An alert from the app is the simplest way to catch a shortfall before it becomes a fee.
- Fix a negative balance fast. If your account goes negative, deposit enough to cover it as soon as you can. A balance left unpaid can lead the bank to close the account and report it.
Read more >> 4 Ways to Get Money From Checking Without a Debit Card
Do you need good credit to open a checking account?
No. Banks don't check your credit score to open a checking account. Many check your banking history instead through a report like ChexSystems. That report tracks things like unpaid overdrafts or accounts closed with a negative balance. ChexSystems gives you a free copy of your report once every 12 months, and you can dispute anything that's wrong.
Your credit reports are a separate record. Check them free weekly at AnnualCreditReport.com, and use Kikoff Credit Monitoring to track changes between checks.
Read more >> Do You Need a Credit Score to Open a Bank Account?
How your checking account affects your credit
A checking account doesn't build credit. It isn't a loan, and banks don't report your balance or spending to the credit bureaus. The one exception works against you: if your account has a negative balance you don't repay and the bank sends it to a debt collector, the collection account can show up on your credit report.
Read more >> Does Opening a Checking Account Affect Your Credit Score?
Bottom line
Opening your first checking account takes six steps. Pick an account with no monthly fee, or one you can easily waive. Know how the bank handles overdrafts before you open it, and set up alerts so a low balance never surprises you.
Your first checking account starts your banking history, but not your credit history. A Kikoff Credit Account reports your on-time payments to all three credit bureaus, so you can start both at once. There's no credit check to sign up, and plans start at $5 a month.
Frequently Asked Questions
Article Sources
Disclaimer: The information provided in this blog post is meant for informational purposes only and does not constitute financial advice.