



With a physical debit card, a new number always comes with a new card, so you’ll need a replacement from your bank. If you think your number was exposed in a data breach, at a skimmer, or to a scammer, lock the card and call your bank today. With a debit card, the money at risk is already in your checking account, and how quickly you report it affects how much federal law protects.
Why a new number means a new card
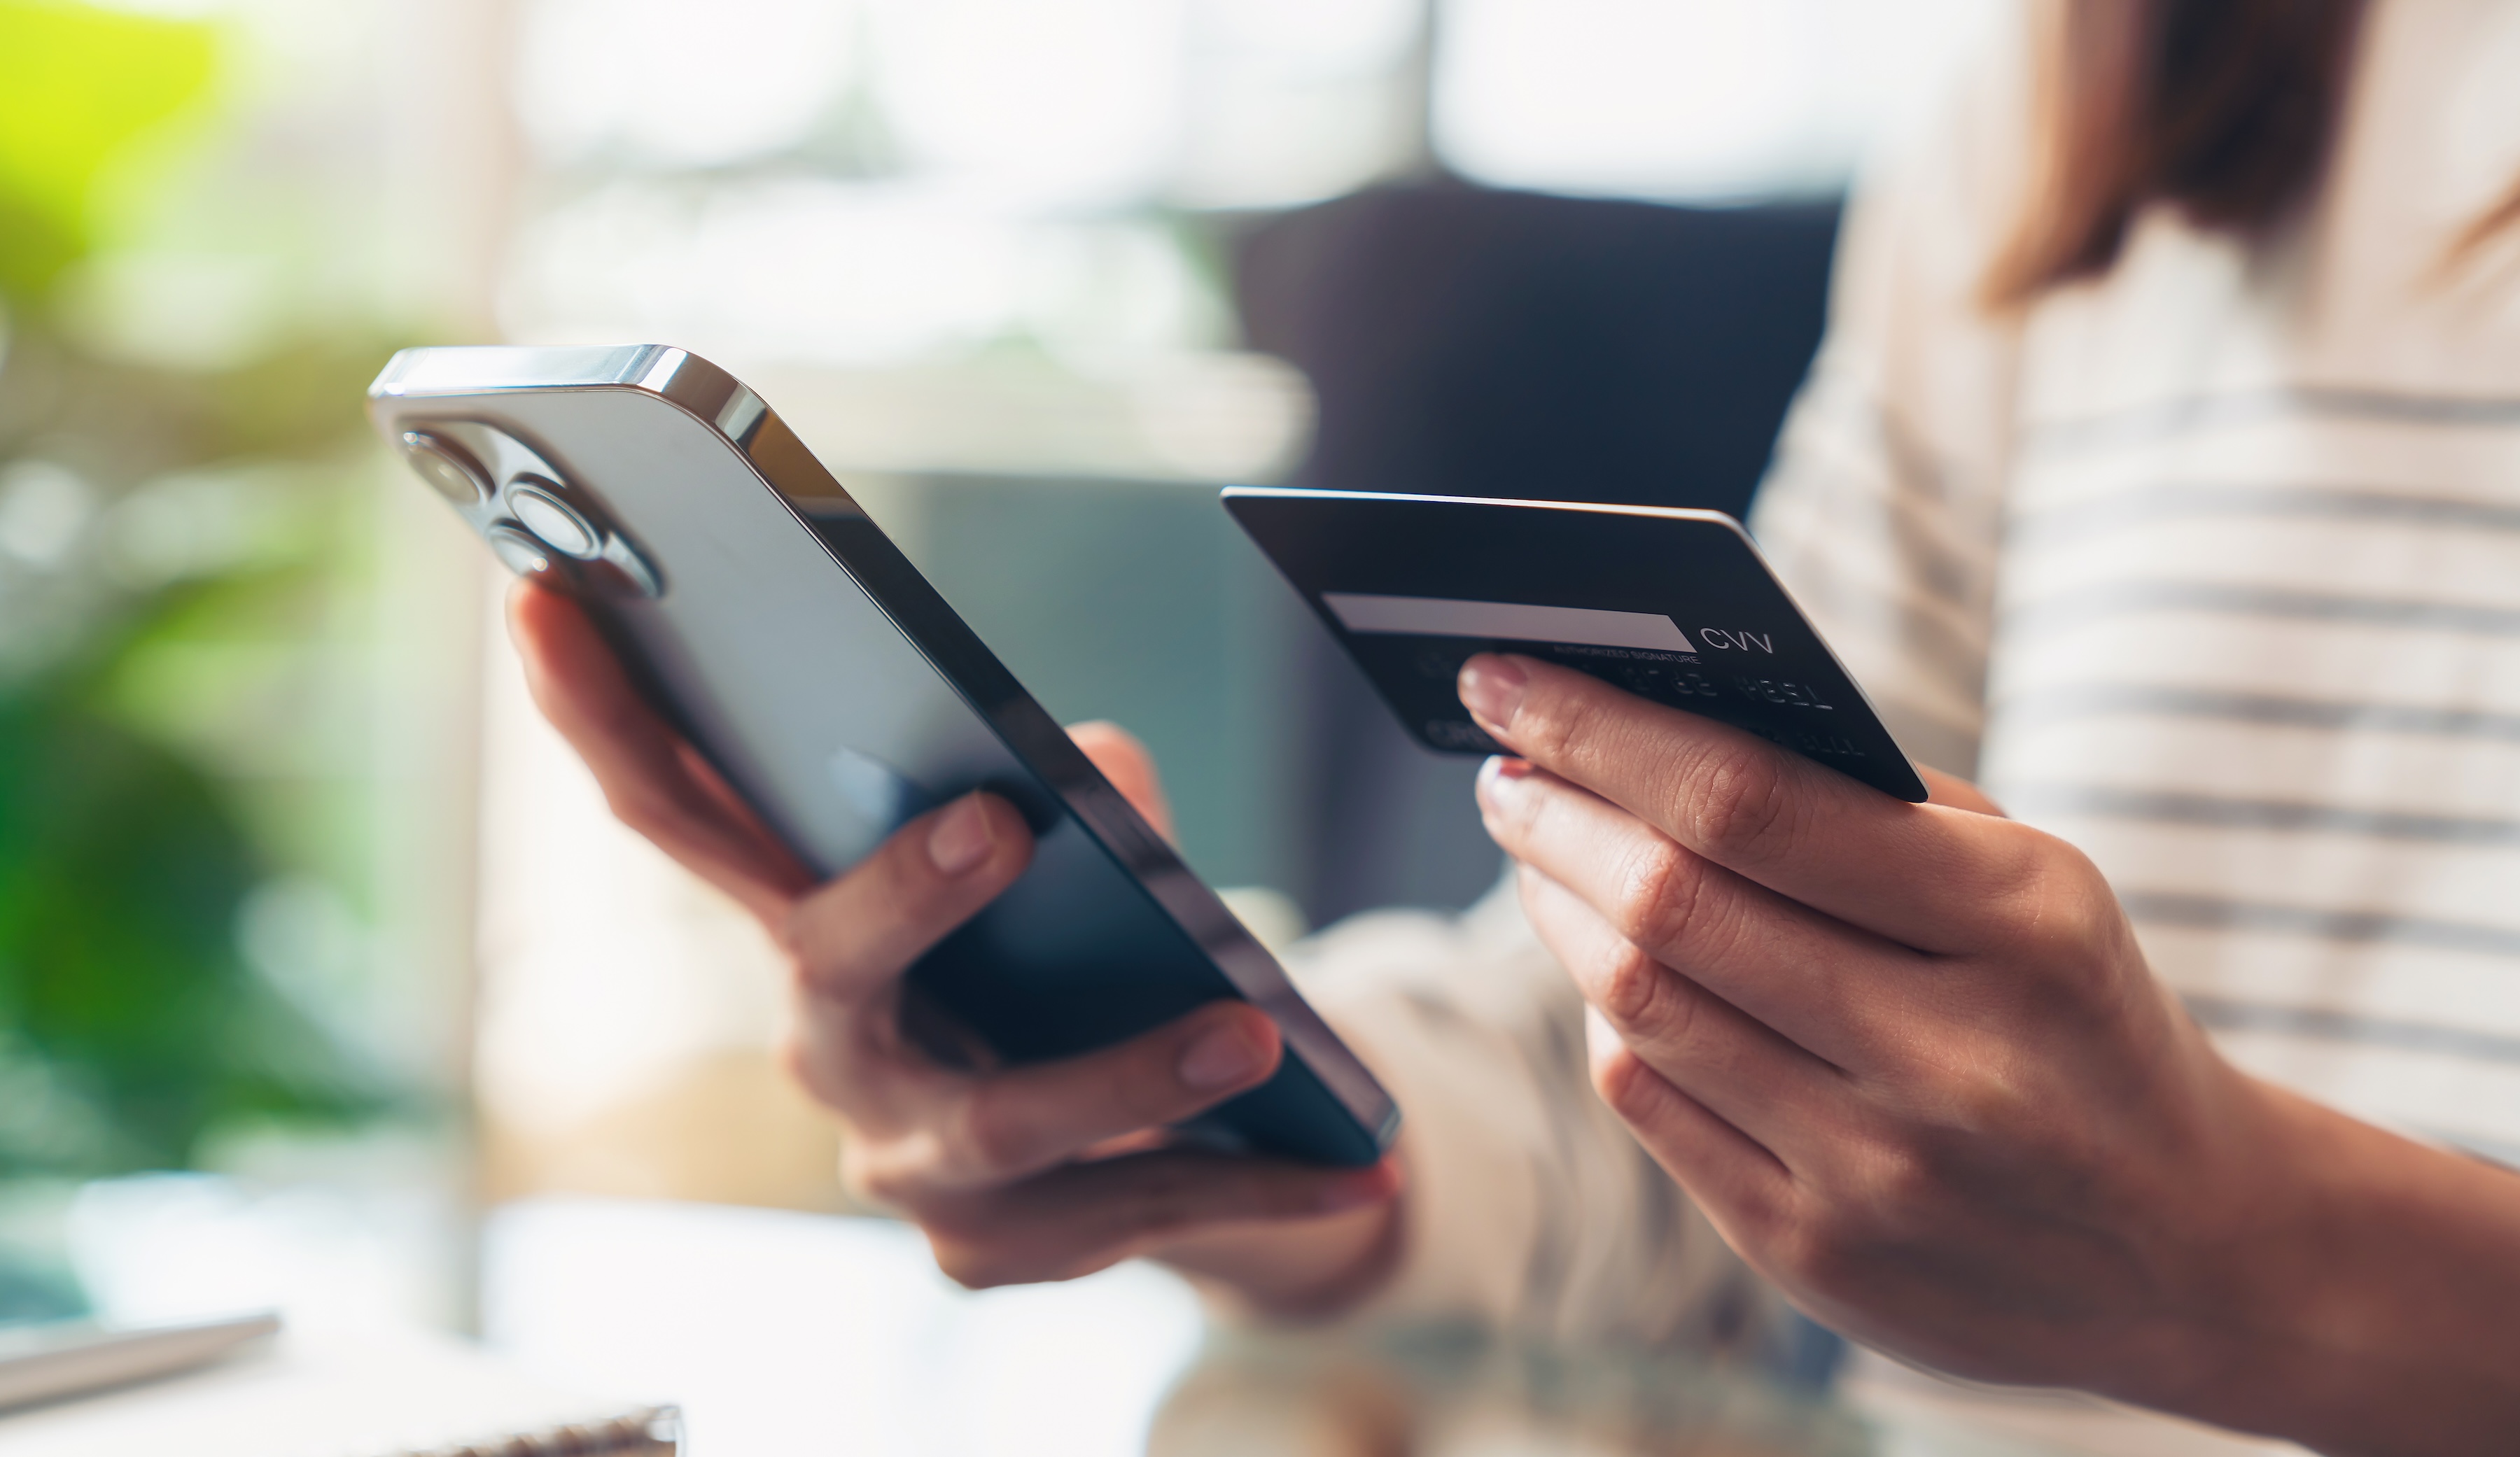
Your card number, expiration date, and security code (CVV) work as a set. They’re printed on the card and stored in its chip and magnetic stripe. When your bank cancels a compromised number, the whole set stops working, and so does the card in your wallet. That’s why the fix is a new card with a new number, expiration date, and CVV.
Some credit card issuers handle this differently. They let you generate virtual card numbers on demand that stand in for your real one when you shop online. Physical debit cards don’t work that way.
Some banks show your new card’s number, expiration date, and CVV in their app before the physical card arrives, so you can keep paying online and covering bills while you wait. Ask about it when you call.
Read more >> How to Handle Fraudulent Charges on Your Account
Why you might want to change your debit card number
You should get a new debit card number if any of the following occur:
- Your card is compromised in a data breach.
- You suspect your card was compromised by a skimming device.
- You gave your card number to someone who turned out to be a scammer, like a caller claiming to be your bank.
Getting the new card is usually the easy part. Updating everything the old card paid for takes longer.
Read more >> How to Protect Your Online Banking Information
How to request a new debit card number from your bank
- Lock the card. In your bank’s app or online banking, look for a lock or turn-off option. This stops new purchases right away.
- Call your bank. Use the number on the back of your card or in the app, never one from a text or email. Ask them to cancel the card and send a replacement.
- Go through recent transactions together. Report any charge you don’t recognize on that call. If the bank asks you to confirm in writing, do it within 10 business days and keep a copy.
- Ask three timing questions. How long will the new card take? Can you expedite it? Can I use a digital card number until it arrives?
- Pick a new PIN if you think the card was skimmed.
- Update your automatic payments. Once the new card arrives, add it to everything the old card paid for, like your phone, utilities, streaming, and subscriptions. Look back through your last few statements so you catch charges that bill every few months or once a year, which are easy to miss.
How fast you report fraud changes what you could lose
Federal law limits what you can lose to debit card fraud, but the limit depends on timing.
Once you report a charge, your bank generally has 10 business days to investigate. If it needs longer, up to 45 days, it has to put the money back in your account in the meantime. Your bank may also offer a zero-liability policy that covers more, so check your account agreement.
Read more >> How to Place a Fraud Alert
What to do while you wait for the new card
Lock your card if you’re not sure
If you can’t tell yet whether your card was compromised, lock it in your bank’s app. A locked card stops new purchases, and you can unlock it if nothing turns out to be wrong.
Use a virtual card number
If your bank shows your new card’s number, expiration date, and CVV in its app, you can use them for online payments and bills until the physical card arrives.
Secure the account that leaked your number
If you know which site or app exposed your card, change that password, turn on two-step verification, and delete the saved card. Don’t add your new card there until the account is secure.
Read more >> What It Means When Your Credit or Debit Card Is Compromised
Does a compromised debit card hurt your credit?
No. Debit cards don’t show up on your credit report. But a breach that exposed your card number may have exposed your name, address, or Social Security number too. Someone could use those to open accounts in your name. You can check your reports free every week at AnnualCreditReport.com, and freezing your credit is free at Equifax, Experian, and TransUnion.
Read more >> Does a Credit Freeze Hurt Your Credit Score?
Bottom line
You can’t keep your card and swap the number, but your bank can replace both, usually without touching your account number. Report it fast, then update everything the old card paid for.
The card itself won’t affect your credit. What leaked along with it might, and a new account opened in your name only shows up on your credit report. Kikoff Credit Monitoring gives you a weekly look at your report, so an account you didn’t open doesn’t go unnoticed. Plans start at $5 a month.
Frequently Asked Questions
Article Sources
Disclaimer: The information provided in this blog post is meant for informational purposes only and does not constitute financial advice.