

If your credit report marks a payment late when you paid on time or lists an account that isn’t yours, you can dispute the information for free. Start by checking which reports contain the error, then contact those credit bureaus and the company that reported it.
You do not need to hire a service to file a dispute. A clear explanation and documents supporting your request give the bureau the information it needs to investigate.
How to dispute credit errors
There are three major credit bureaus: TransUnion, Equifax, and Experian. An error might appear on one, two, or all three reports, so check each before getting started.
Follow these steps:
- Get your credit reports. You can access free weekly reports from all three bureaus at AnnualCreditReport.com.
- Identify what is wrong. Look for unfamiliar accounts, incorrect balances, duplicate debts, or payments incorrectly marked late.
- Gather supporting documents. Depending on the error, these might include account statements, payment confirmations, or a letter from the creditor.
- Submit your dispute. Explain what is wrong and what you want corrected. Include the account number, your contact information, and copies of supporting documents.
- Contact the company that supplied the information. Dispute the error with the lender, collector, or other business that reported it, as well as each bureau showing it.
- Keep records and review the response. Save your submission, confirmation numbers, and supporting documents so you can follow up.
You can file directly with Equifax, Experian, or TransUnion. Follow the bureau’s instructions for online, phone, or mailed disputes.
For mailed disputes, send copies rather than original documents. Consider certified mail with a return receipt so you have a record of delivery. The dispute instructions explain what to include.
Dispute the error, not just the negative information: A dispute is for information that is inaccurate or incomplete. Accurate negative information generally cannot be removed simply because you would prefer it off your report.
How long does a dispute take?
Credit bureaus generally have 30 days to investigate, although some investigations can take up to 45 days. They must notify you of the results within five business days after completing the investigation.
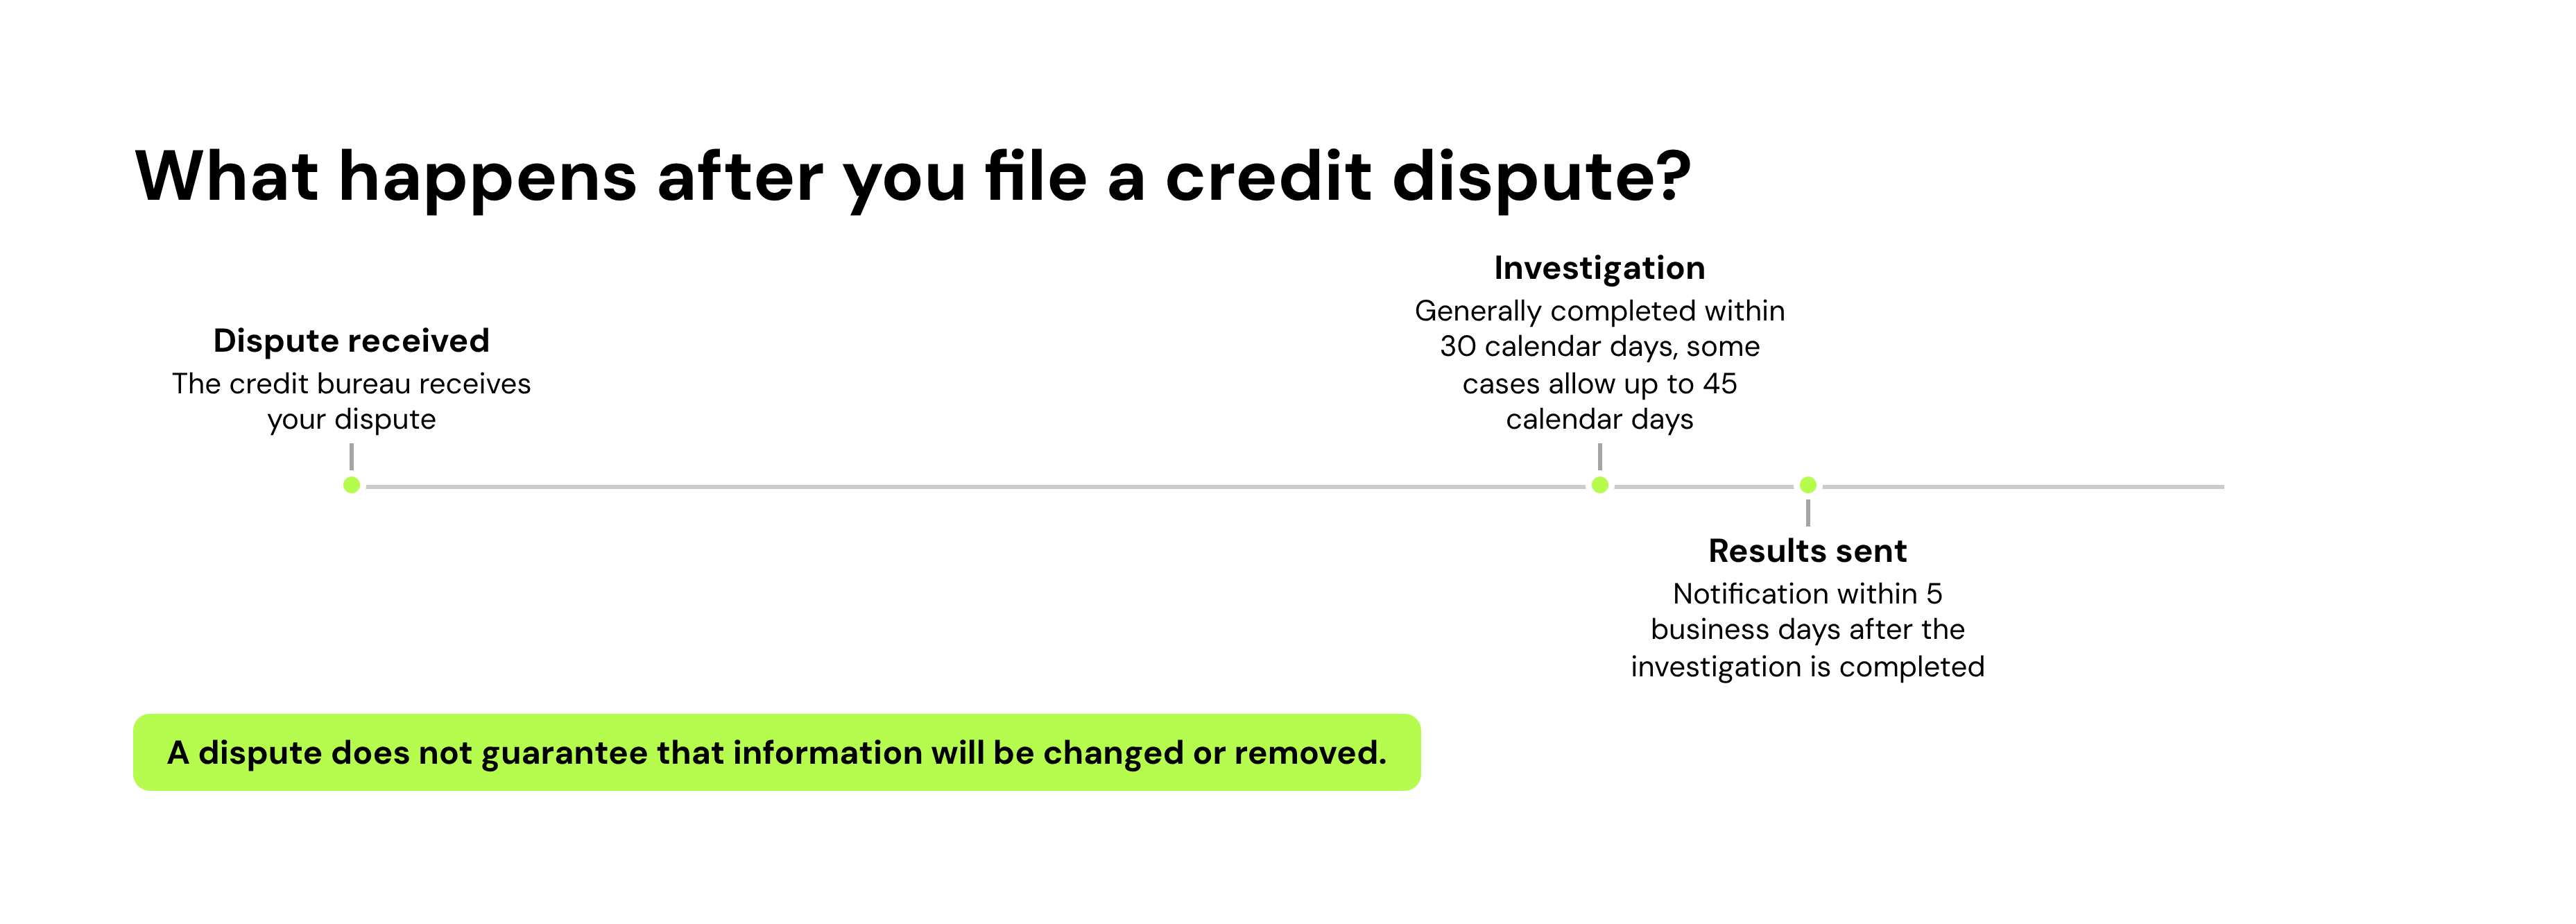
Information found to be inaccurate, incomplete, or unverifiable must be corrected or removed. A dispute does not guarantee a change to your report or credit score.
What if the error is still there?
Read the investigation results to see why the information was not changed. If you have additional evidence, submit it with a clear explanation of what the earlier investigation missed.
You can also ask the bureau to add a statement explaining your dispute to your file. If a persistent error is affecting a mortgage, housing application, or another important decision, consider contacting a consumer-law attorney or legal aid organization.
Read more >> How to Read a Credit Report
Tools for disputing credit errors
You can handle a dispute yourself, but a tool may help you organize the information or prepare a letter. Compare what it actually does before signing up, especially if it charges a fee.
Kikoff
Kikoff’s dispute tools can generate a personalized dispute letter based on the error you identify.
Review the letter before sending it to make sure the account details, explanation, and requested correction are accurate. Add the documents that support your dispute, and check the available delivery options and any plan requirements.
Using a tool does not guarantee that the bureau will change your report. The outcome depends on the information and the investigation.
Other tools
You can also use the bureaus’ own dispute systems or an FTC sample letter without paying a third-party service.
If you are comparing apps, check:
- Whether they prepare letters, submit disputes, or only monitor reports
- Which bureaus they support
- Whether you can review the information before it is sent
- What they charge and whether charges recur
- How they protect your personal information
Be cautious of services promising guaranteed removals or encouraging you to dispute information you know is accurate.
What happens if there are errors on your credit report?
Depending on the error, incorrect information can affect how lenders assess your application or what borrowing terms they offer. Credit reports may also be used in rental screening and certain employment decisions, where permitted by law.
Not every error affects a credit score, but unfamiliar information is still worth checking. An account you do not recognize could be a reporting mistake or a sign of identity theft.
If the account was opened through identity theft: Report it at IdentityTheft.gov and follow the recovery plan. Contact the affected company’s fraud department and consider freezing your credit with all three bureaus.
After a correction, review your reports to confirm it appears where needed. Keep making payments on your legitimate accounts while the dispute is being investigated.
Read more >> How to Report Identity Theft
Bottom line
Start with the specific error: what is wrong, where it appears, and which documents support your correction. Send that information to the relevant bureaus and the company that reported it, then keep track of the response.
You can dispute errors yourself without paying a service. If you would like help preparing a letter, explore Kikoff’s dispute tools and review the available features before getting started.
Frequently Asked Questions
Disclaimer: The information provided in this blog post is meant for informational purposes only and does not constitute financial advice.