



Travel credit cards offer a wide range of benefits, such as sign-up bonuses, travel credits, airport lounge access, and trip protections. But they also often charge annual fees, which can make it hard to know whether the perks are worth the cost.
Whether a travel card pays off depends on your spending habits, how often and how you travel, and whether you pay your balance in full each month.
Are travel credit cards worth it?
A travel credit card can be worth it if you spend and travel enough for the benefits to outweigh the costs.
When they’re worth it
- You travel more than a couple of times a year. The more often you travel, the better your chances of using the card's benefits.
- You pay your balance in full every month. If you carry a balance, interest charges can quickly outweigh any rewards or card perks.
- You'll use the perks. If a card offers benefits that you'd normally pay for, such as free checked bags on flights, the savings can help offset the cost of an annual fee.
When they’re not worth it
- You carry a balance. Cards that carry a balance charge an average 22.36%, according to the Federal Reserve. Even carrying a small balance from month to month can eat into any value.
- You rarely travel. If you travel once or twice a year, you may not use enough perks to cover an annual fee.
- You want simpler rewards. For straightforward rewards, you may be better off with a cashback card.
Read more >> How to Start Traveling with Credit Card Points
How travel credit cards work
Travel credit cards offer points or miles on your everyday spending, and many also offer other perks that can save you money or make trips more comfortable.
Points and miles earning structures
Travel credit cards typically offer a tiered rewards structure, giving you bonus rewards on certain spending categories and 1 point or mile on all other spending. In some cases, you may get a higher flat rewards rate on all of your spending.
Sign-up bonuses
Travel cards also often offer a sign-up bonus to new cardholders. For example, you may earn 50,000 points or miles after you spend $3,000 in the first three months with the card. A bonus like that can cover the first year’s fee, which gives you time to judge whether you'll get enough value from the card's ongoing benefits to cover the yearly cost going forward.
Benefits
Travel credit cards can offer a wide range of benefits. With a general travel card, for instance, you might get credits for general travel expenses, complimentary access to airport lounges, or the ability to transfer your points to other loyalty programs.
With an airline or hotel co-branded credit card, you may get extra perks, like free checked bags, priority boarding, and companion flight certificates, or hotel elite status and a free night's stay every year.
Annual fees vs. rewards value
Many travel cards charge an annual fee, and premium cards with lounge access and travel credits can cost several hundred dollars a year.
Add up the perks you’d actually use or otherwise pay for, add your expected rewards, and subtract the fee. Then compare that to what a no-fee card would earn on the same spending.
When does a $95 travel card beat a 2% cashback card?
Say you spend $1,000 a month on your card and pay it in full each month. A travel card earns 3 points per dollar on travel and dining and 1 point on everything else (1 cent per point), charges $95 a year, and gives you $100 in perks you’d use. A cashback card earns 2% on everything, with no fee.
Here’s what changes as more of your spending goes to travel and dining.
What credit score do you need for a travel credit card?
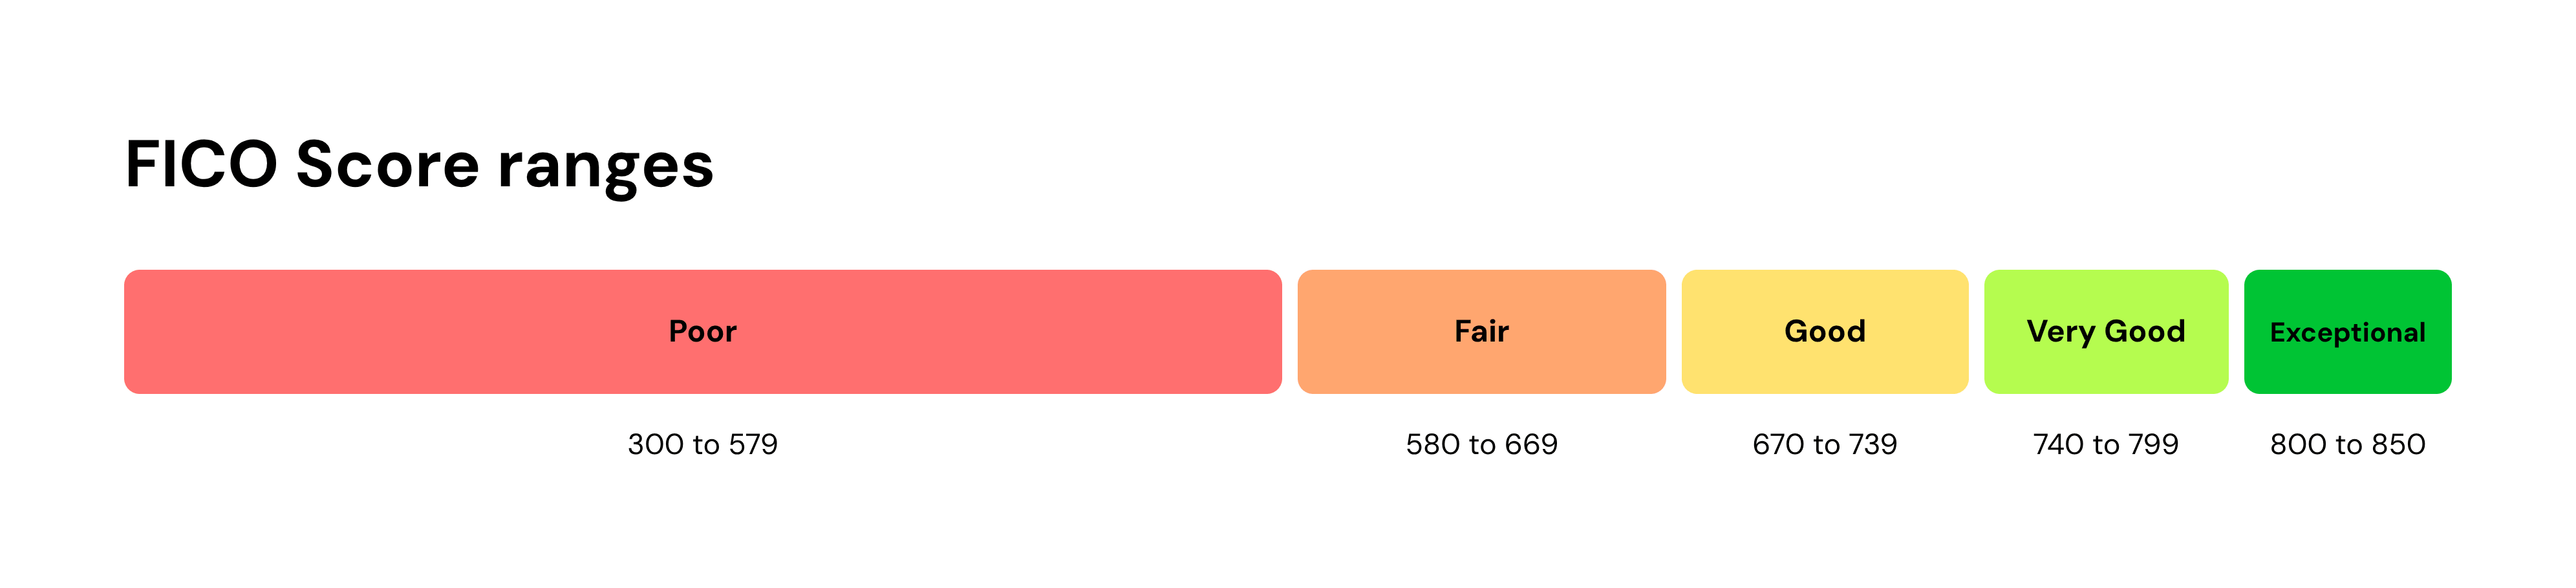
Issuers rarely publish a minimum credit score, but a card’s application page usually says what credit level it’s aimed at. For most travel cards, that’s good to excellent credit — or a FICO Score of 670 or higher.
That said, card issuers also consider your full credit history, income, other debts, and recent applications to determine your eligibility. Each application typically results in a hard inquiry, so get prequalified first. Though it doesn’t guarantee approval, it uses a soft inquiry that doesn’t affect your credit.
Alternatives to travel credit cards
Cashback credit cards
Cashback cards return a percentage of each purchase you make back as a statement credit, a deposit into your bank account, or a paper check. Some cashback cards allow you to buy gift cards, shop online with your rewards, or even book travel. They tend to charge no or low annual fees, making them best for simpler rewards.
No-annual-fee cards with travel perks
Some travel cards skip the annual fee in exchange for lower rewards rates and fewer perks. If you travel infrequently but want to dip your toes into the world of travel rewards, this option can be a good starting point.
Build credit first
If you have a poor credit history or a thin credit file, a secured credit card or a starter credit card can give you the chance to establish a positive payment history.
Read more >> 6 Ways to Build Credit Without a Credit Card
Approval takes more than a number. Issuers also weigh your income, your existing debt, and how many cards you’ve opened recently. A 690 with four new accounts can get declined where a 660 with steady income doesn’t. Check for prequalification before applying. It’s a soft pull, so it costs you nothing and tells you where you stand.
Bottom line
A travel credit card is worth it when the perks you’d actually use outweigh the annual fee, and you pay in full every month. If you’re not sure, a no-fee cashback card can be a simpler way to earn rewards on your spending.
The best rewards cards are a discount on your own spending, and issuers decide who gets that discount based on credit. If your credit is still getting established, Kikoff’s Credit Account reports your on-time payments to all three credit bureaus, with no credit check to sign up. Plans start at $5 a month.
Frequently Asked Questions
Article Sources
Disclaimer: The information provided in this blog post is meant for informational purposes only and does not constitute financial advice.