Paying credit accounts on time is one of the most important habits for building and maintaining credit. Payment history generally accounts for 35% of a FICO Score, making it the largest of FICO’s five scoring categories.
VantageScore also identifies payment history as highly influential, although it organizes and weights its categories differently. No single payment produces a particular score change, but a consistent record of paying as agreed gives scoring models positive information to evaluate.
Why do on-time payments matter so much?
Your credit reports may contain the payment status and history that lenders and other creditors report for your accounts. Not every company reports to every credit bureau, and payments for everyday expenses such as groceries do not become part of a credit report simply because you paid them on time.
When an account is reported, scoring models can evaluate whether you paid as agreed or became 30, 60, 90, or more days past due. FICO explains that the severity, recency, and frequency of late payments can all affect the payment-history category.
One isolated late payment is different from several recent delinquencies, but there is no universal number of points that every consumer will lose. The effect depends on the scoring model and the rest of the information in the person’s credit report.
What counts as an on-time payment?
For a credit card, paying at least the minimum amount by the due date generally keeps the account current. Paying the minimum is not the same as paying the statement balance in full. If you carry a balance, you may owe interest even though the payment was on time.
For loans, you generally must make the required scheduled payment by the due date. Check the loan agreement for the amount, acceptable payment methods, processing deadlines, and any grace period.
A payment must be received according to the creditor’s rules, not merely scheduled or mailed on the due date. The Consumer Financial Protection Bureau recommends allowing enough processing time, especially when paying by mail or through an online bill-pay service.
What happens when a payment is late?
A creditor may consider a payment late shortly after the due date and may charge a fee or impose other consequences permitted by the account agreement. However, creditors generally do not report a payment to the nationwide credit bureaus as delinquent until it is at least 30 days past due.
Once a late payment is reported, it can affect your credit scores. More serious or repeated delinquencies, such as payments that reach 60 or 90 days past due, may have a greater effect. Most negative payment-history information can generally remain on a credit report for up to seven years, although its influence on a score may diminish over time as it ages and the rest of the report changes. The CFPB explains the reporting time limits.
If you miss a due date, pay as soon as possible and contact the creditor. Bringing the account current before it reaches 30 days past due may prevent a delinquency from being reported, but it may not eliminate a late fee or other account consequences.
Read more >> What Happens if You Miss a Credit Card Payment?
How does payment history fit into a FICO Score?
FICO groups credit-report information into five general categories:
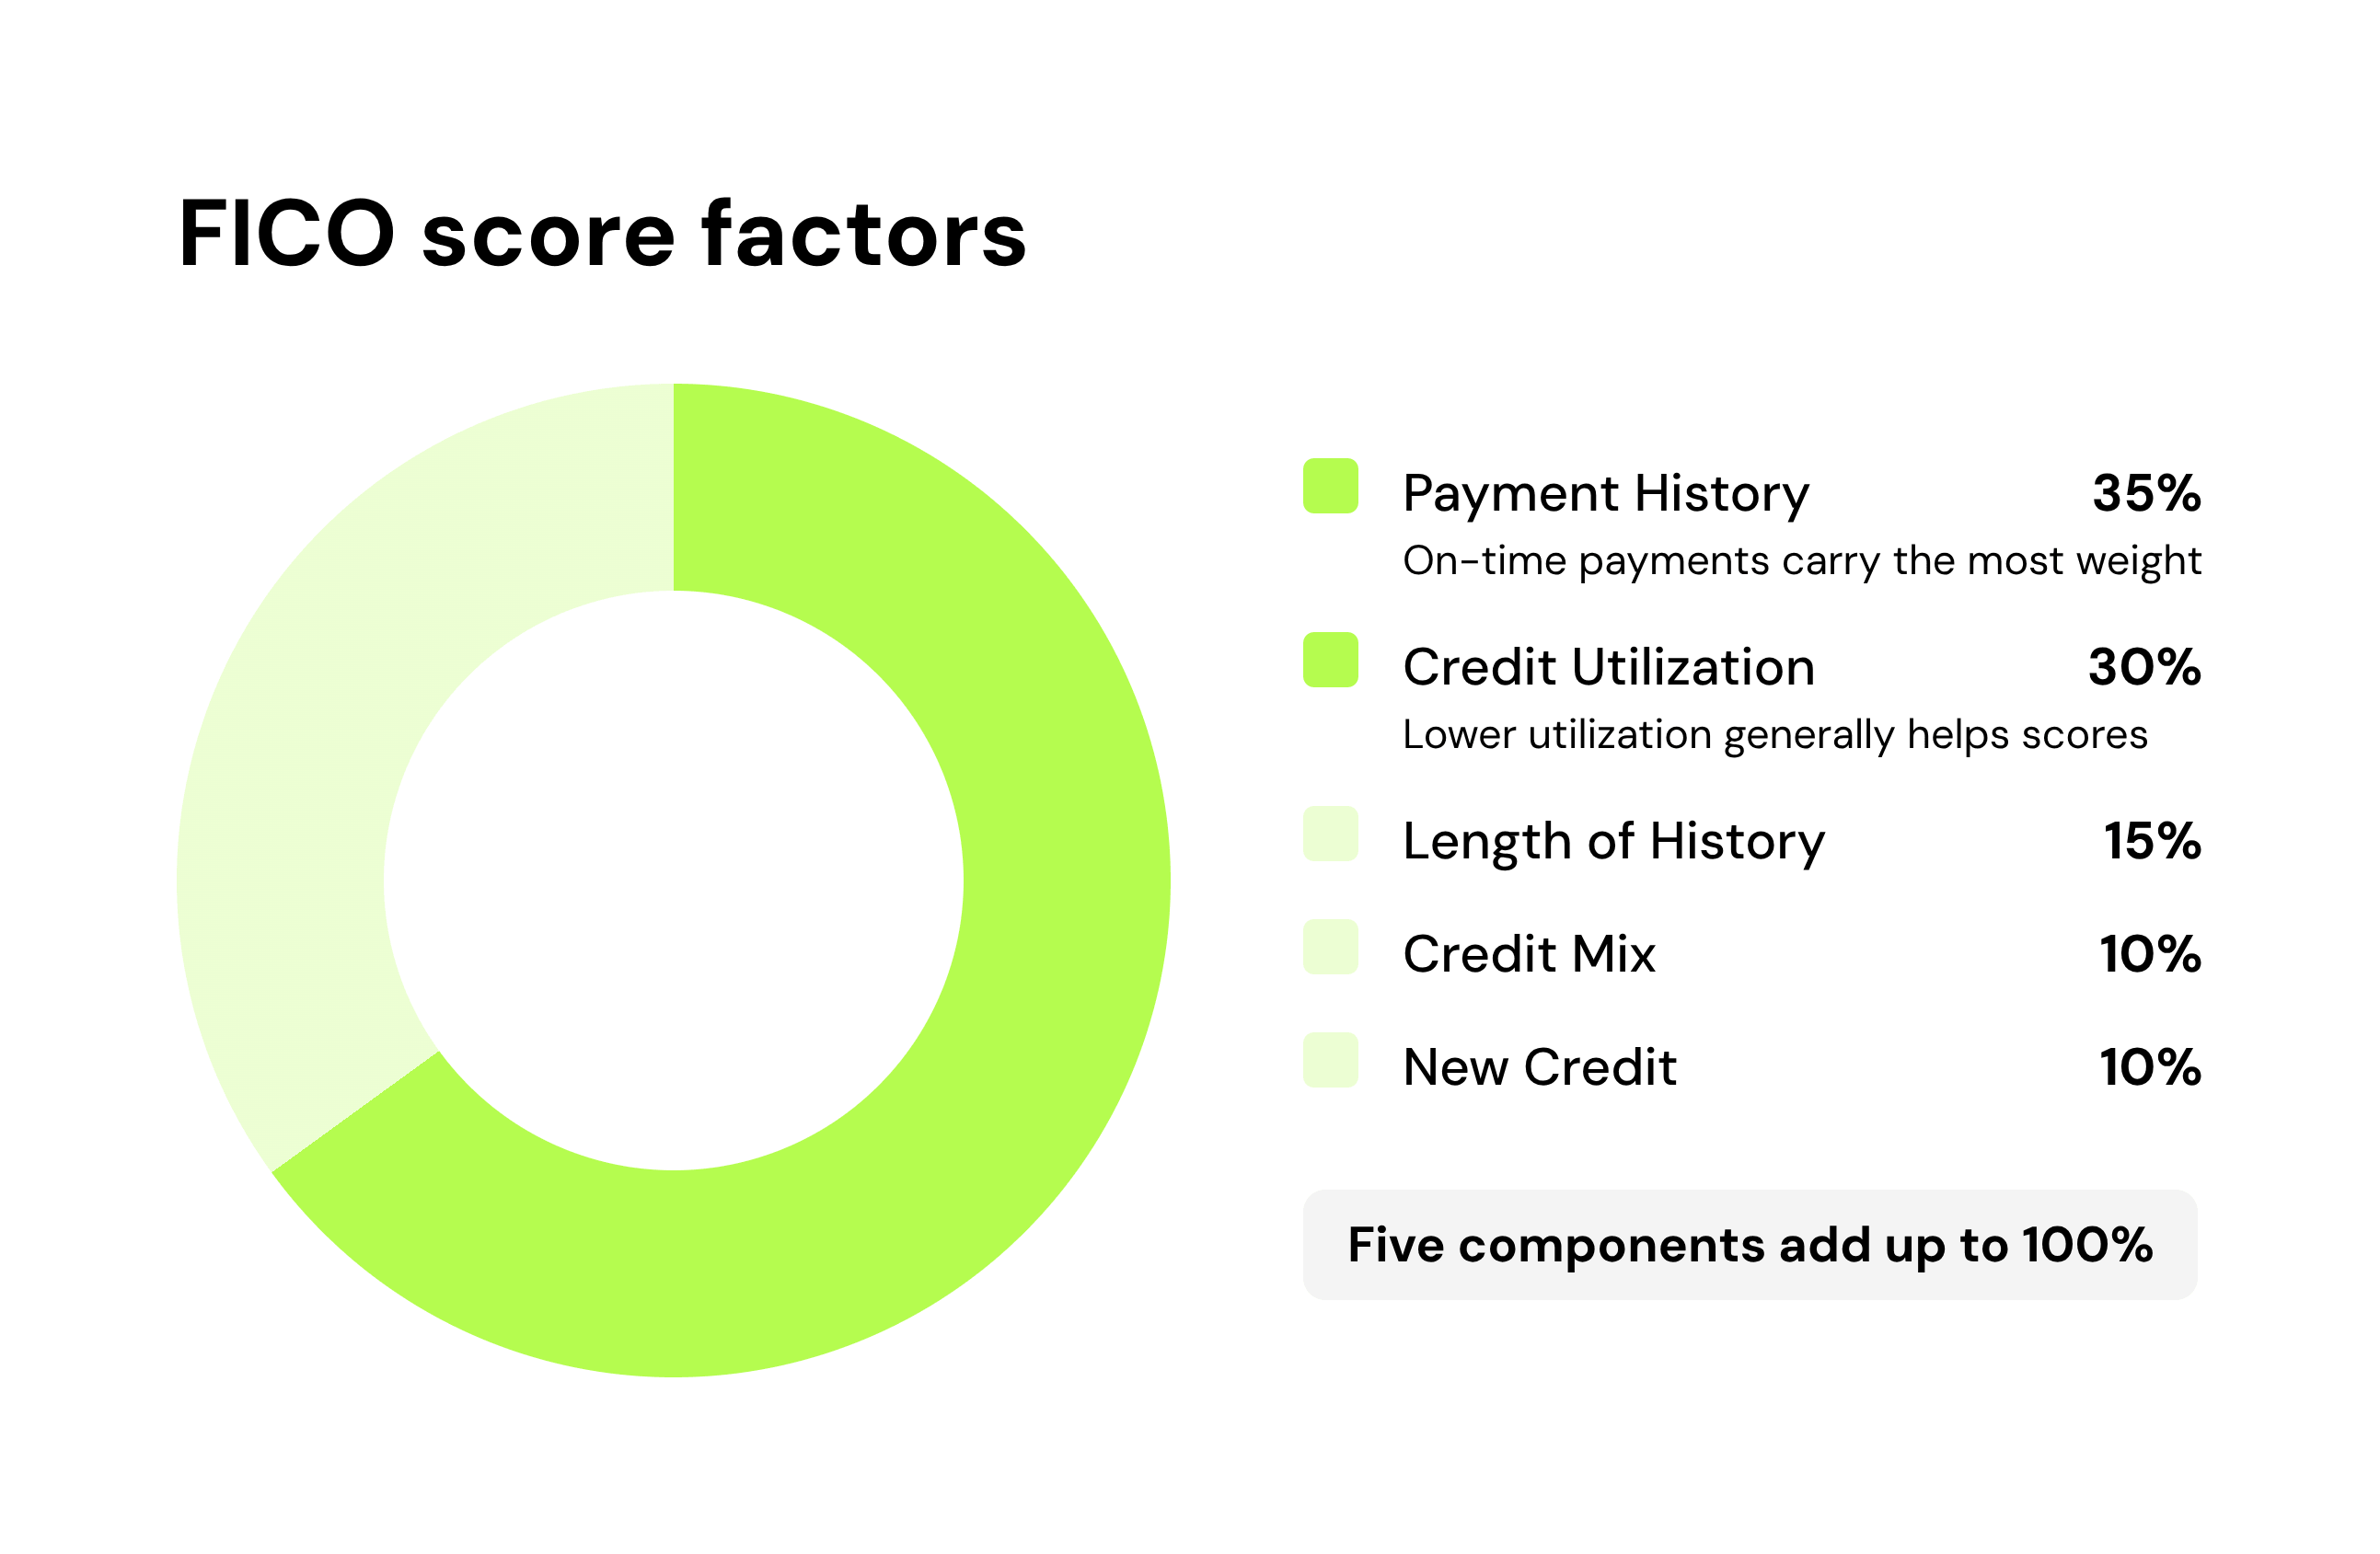
- Payment history: 35%
- Amounts owed: 30%
- Length of credit history: 15%
- New credit: 10%
- Credit mix: 10%
Amounts owed is the full name of the 30% category. Credit utilization is an important part of that category, but it is not the only debt information FICO may consider. Similarly, the new-credit category considers more than inquiries alone.
These percentages describe their general importance across the overall population. The effect of each category can vary with the information in an individual’s credit report. Making on-time payments is important, but no single payment produces a predictable or instant score change.
Read more >> What Is a FICO Score?
Practical ways to avoid missing a payment
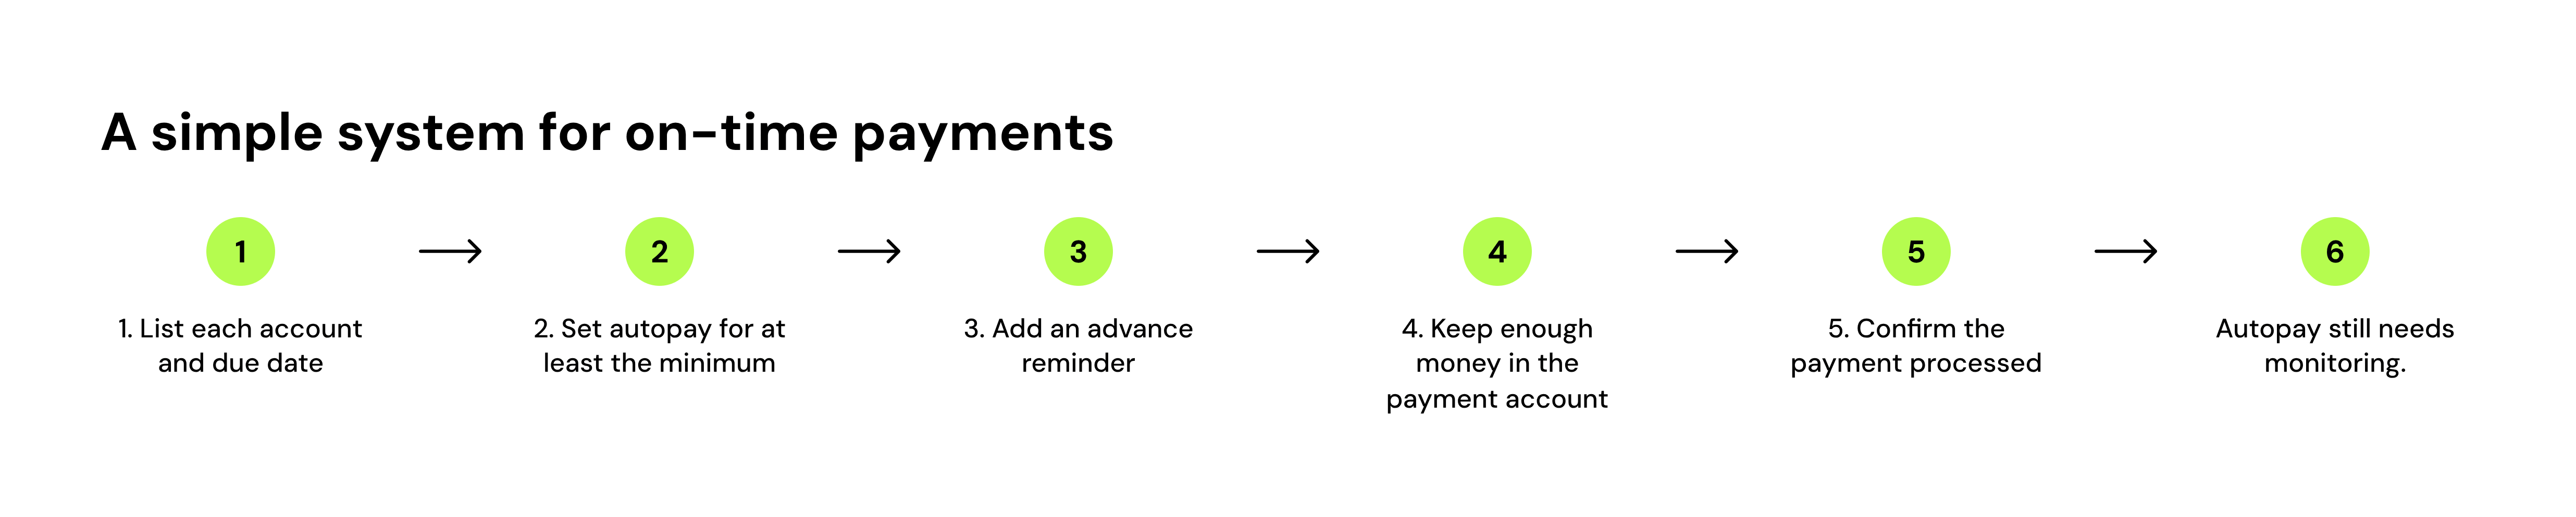
Set up autopay carefully
Set autopay for at least the required minimum, then confirm that the payment processed. Keep enough money in the connected account to avoid a returned payment, overdraft, or bank fee.
Create reminders before each due date
Calendar or account alerts can give you time to transfer money or address a problem before the deadline. A reminder is still useful when autopay is enabled because cards can expire and bank information can change.
Ask whether you can change your due date
Some creditors allow you to move a monthly due date closer to payday or group several bills within the same part of the month. Ask when the change will take effect and whether it will alter the next payment period.
Review statements and payment confirmations
Check that the required amount, due date, and payment account are correct. Save the confirmation until the payment appears on your account.
Contact the creditor before a payment becomes unmanageable
If you expect to miss a payment, ask whether the creditor offers a hardship program, temporary payment arrangement, or due-date change. The creditor may not offer assistance, but contacting it early may give you more options than waiting until the account is seriously past due.
How can on-time payments help you build credit from scratch?
To build payment history, you need an account that reports to at least one credit bureau. Before opening an account solely for credit-building purposes, confirm where it reports, what it costs, what payments are required, and what happens if you pay late.
As the account is reported over time, on-time payments can add positive information to your credit reports. Your scores may still change for other reasons, including balances, new accounts, inquiries, account age, and changes elsewhere in your reports.
Reviewing your credit reports can help you confirm that accounts and payment statuses are accurate. You can obtain reports from each nationwide credit bureau through AnnualCreditReport.com.
Bottom line
On-time payments are a central part of a healthy credit profile, but their effect cannot be reduced to a certain number of points or a fixed timeline. Focus on paying at least the required amount by each due date, confirming that payments process, and responding quickly when something goes wrong.
Kikoff’s Credit Account reports your on-time payments to all three credit bureaus, with no hard credit check to sign up.
Add positive payment history to your credit profile with Kikoff.
Frequently Asked Questions
Disclaimer: The information provided in this blog post is meant for informational purposes only and does not constitute financial advice.