Your landlord’s insurance covers the building, not your belongings. If your things are damaged or stolen, your own renters insurance is what pays to replace them. It can also cover your liability if someone’s hurt in your home, and sometimes a place to stay if you can’t live there.
To file a claim, document what happened, check it against your deductible, notify your insurer as soon as it’s safe, submit your claim with evidence, work with the adjuster, and review the offer before you accept it.
How to file a renters insurance claim step by step
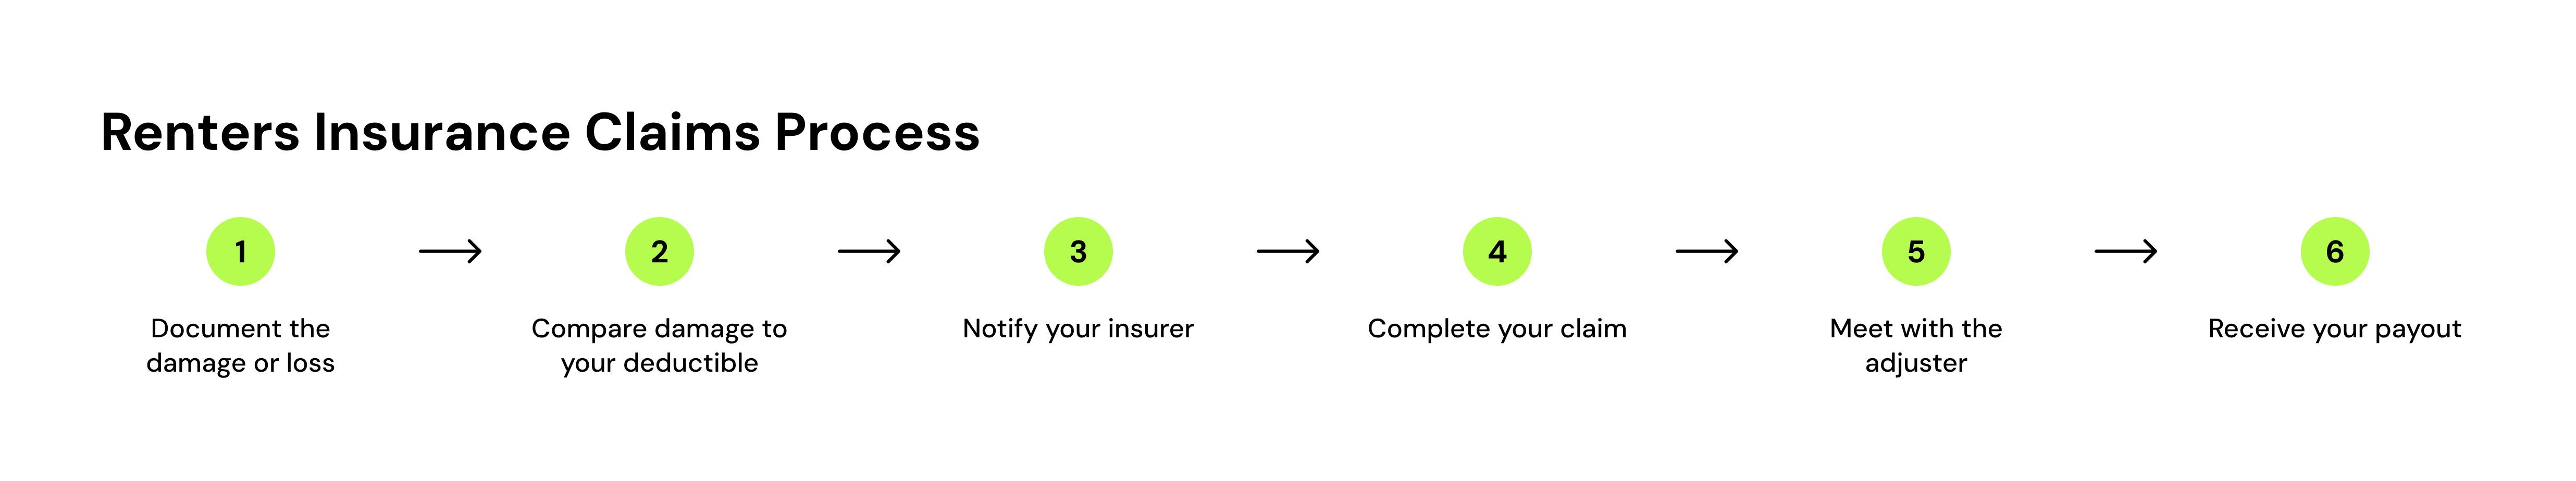
1. Document the damage or loss
First, make sure everyone is safe. If there’s smoke, a gas smell, or water near outlets, leave and call 911 or your utility. This step helps the insurer verify what was damaged, what it’s worth, and when the loss likely happened. If your belongings are damaged in a covered event, insurance companies won’t just take your word for it. Take photos and videos of everything that’s damaged, including close-ups.
It’s also helpful to create a list of all damaged property and its approximate value. If you have receipts showing what you paid for each item, that’s even better.
Tell your landlord in writing too, even if the damage seems minor. The landlord handles repairs to the building, and a written notice creates a record of when they found out. If a theft or break-in caused the loss, file a police report and get the report number.
Protect your name, not just your home. If a break-in took anything with your Social Security number or account numbers on it, freeze your credit with Equifax, Experian, and TransUnion. A freeze is free, doesn’t affect your credit score, and stops new accounts from being opened in your name. You can lift it anytime you need to apply for credit. Kikoff’s Credit Monitoring can alert you to changes on your report while things settle.
2. Compare the loss to your deductible
Your deductible is the amount you pay before your policy pays anything. Add up what it would cost to replace everything on your list. If the total is less than your deductible, insurance won’t pay for it, so filing may not be worth it.
For example, say a stolen bike and laptop would cost $1,400 to replace, and your deductible is $1,000. The most you’d get is $400. You could get less if your policy pays actual cash value, which subtracts wear and tear before the deductible comes out.
That matters because a claim you file, even a small one, may be recorded in your claims history and could affect your rate at renewal. If the loss is clearly bigger than your deductible, as with a fire or a major break-in, skip the math and notify your insurer right away.
3. Notify your insurance company
You should notify your insurer of the damaging event as soon as you can. Deadlines vary by policy, so check your policy for any notice or claim-filing time limits. Notification isn’t the same thing as filing a claim. You can call the insurance company, notify them through their website, or send a notification through the app. You can file the full claim once your documentation is ready.
4. Fill out the claim form
Next, you’ll need to fill out your claim form. Expect the form to ask for your personal information and policy number. It will also ask for details of the covered event, a detailed list of all property damage and reimbursable expenses, and additional documentation (like photographs of the damage).
5. Meet with the adjuster
Your insurance company might require you to meet with an adjuster in person or virtually. The adjuster verifies the details of the claim and determines how much the insurance company should pay under your policy.
Be polite and keep your answers short and direct. If you’re unsure about a question, ask what the insurer needs before you answer. Your state insurance department answers questions for free. Stick to claim-relevant facts about the damage or loss.
6. Receive your payout
Before you accept, check the offer against your list and receipts. If your policy pays replacement cost, the insurer may pay the depreciated value first and the rest after you replace the item and send the receipt. Read anything attached to a settlement check before you sign or cash it, because some say the payment is final. If you discover additional damage or expenses, you may be able to request more money for the same claim.
What does renters insurance cover?

Renters insurance policies vary in terms of what they cover. However, most policies protect personal belongings, shield you from personal liability if you accidentally injure someone or damage their property.
Personal property coverage
If your furniture, electronics, or other belongings are damaged or lost due to a “covered peril” (a type of loss listed in your policy, subject to exclusions and limits), your policy can pay to repair or replace them, up to your coverage limits and minus your deductible.
Common covered perils include:
- Fire or smoke damage
- Vandalism or theft
- Sudden water damage, such as a burst pipe
- Wind and hail damage
Flood isn’t covered. Standard renters policies exclude flooding, including flooding from storms. You can buy contents-only flood coverage through the National Flood Insurance Program at FloodSmart.gov.
Your policy may also cover your belongings away from home, such as a laptop stolen from your car, usually up to a lower limit. Check the off-premises limit in your policy.
Check the limits on valuables. Your policy may cap what it pays for certain kinds of items, such as jewelry, watches, collectibles, cash, or bikes, even if your overall coverage limit is much higher. Look for a section called “special limits of liability.” If something you own is worth more than its category limit, ask your insurer about adding it to your policy with a rider, sometimes called scheduled personal property. Riders usually require an appraisal or receipt.
Personal liability protection
What happens if someone visits your home, gets seriously injured after slipping and falling, and sues you? If you have renters insurance, your policy’s liability coverage can pay for their medical bills and your legal defense, up to your limit. Most policies will also pay if you accidentally damage another person’s property.
Loss of use or additional living expenses
If you have to leave your home while it’s repaired after a covered peril, your renters insurance might pay for additional living expenses. This is called loss of use coverage.
For example, if your apartment is badly damaged in a fire, your renters insurance might pay for you to stay in a hotel, cover a storage unit for your belongings, and pay for additional groceries.
What to do if you can’t live in your rental
If a fire, a burst pipe, or another covered loss makes your unit unlivable, your loss-of-use coverage can help pay for somewhere to stay. Here’s how to keep that process moving:
- Tell your insurer you’ve been displaced. Ask how loss-of-use payments work on your policy, what limit applies, and whether it can advance money for a hotel so you aren’t covering it all yourself while you wait.
- Keep every receipt. That includes hotels, meals beyond your usual grocery bill, laundry, extra mileage, and storage. Loss of use pays the difference between your normal costs and what you’re spending now, so your receipts are the evidence.
- Put your questions to your landlord in writing. Ask when repairs are expected to be finished and what happens with your rent while you’re out.
Whether you still owe rent on a unit you can’t live in depends on your lease and your state’s tenant laws. A local legal aid office or tenant rights group can tell you where you stand. A licensed attorney can review your lease if the landlord’s answer doesn’t sound right.
What to do if your claim is denied
Start with the denial letter, which should say which part of your policy the insurer relied on. If you think it’s wrong, ask the insurer in writing to reconsider, and include your photos, receipts, and anything else that supports the claim. You can also file a complaint with your state insurance department for free. If the claim still stalls, a licensed attorney who handles insurance disputes can tell you whether you have a case.
Does your credit affect what you pay for renters insurance?
In most states, it can. Insurers can use a credit-based insurance score, which is built from your credit report but isn’t the score a lender pulls, as one factor in your price. Payment history carries the most weight. The rules vary by state, and your state insurance department can tell you what applies where you live.
Bottom line
A claim backed by photos, receipts, and a written note to your landlord gives you the best footing for a fair payout. And since your credit report can factor into what you pay for coverage, it’s worth knowing that your largest monthly bill, your rent, usually isn’t on it unless a rent reporting service adds it.
Kikoff’s Rent Reporting reports your on-time rent payments to Equifax and TransUnion, and can add up to two years of past rent for a one-time $50 fee. Plans start at $5 a month.
Frequently Asked Questions
Article Sources
Disclaimer: The information provided in this blog post is meant for informational purposes only and does not constitute financial advice.