

If you’re a U.S. expat or are on your way to becoming one, you’re probably thinking about everything you need to do to ensure a smooth transition. But have you thought about your credit when you’re overseas?
You can continue building U.S. credit while living abroad if your providers allow you to keep and use your accounts. Before you move, check their residency requirements and make a plan for payments, account access, and monitoring from overseas.
How to build credit as a U.S. expat
Managing your credit from another country takes some preparation. These steps can help you stay on top of your U.S. accounts.
Check your providers’ address requirements
Before you move, ask each bank and card issuer whether you can keep your account while living in your destination country. Address and residency requirements vary, and a U.S. mailing address may not be enough.
A trusted friend, relative, or mail-forwarding service may be an option for receiving mail if your provider permits it. Give the provider accurate information about where you live, and ask whether it accepts a separate mailing address.
Also confirm how you will receive replacement cards and account verification codes overseas. Set up electronic statements and update your contact details before leaving.
Keep up with payments
Moving abroad does not change your obligation to repay U.S. debts. Keep making payments by their due dates, even if you no longer use the account.
A payment generally must be at least 30 days late before it is reported to the credit bureaus, but fees can apply sooner. Reported late payments can generally remain on your credit reports for up to seven years.
Set up payment reminders or autopay, and make sure the linked account has enough money. If you transfer funds from abroad, leave room for processing delays, transfer fees, and exchange-rate changes.
Keep your accounts active
If you go too long without using your American credit cards, lenders may ultimately close your accounts. Making occasional purchases can help keep them active.
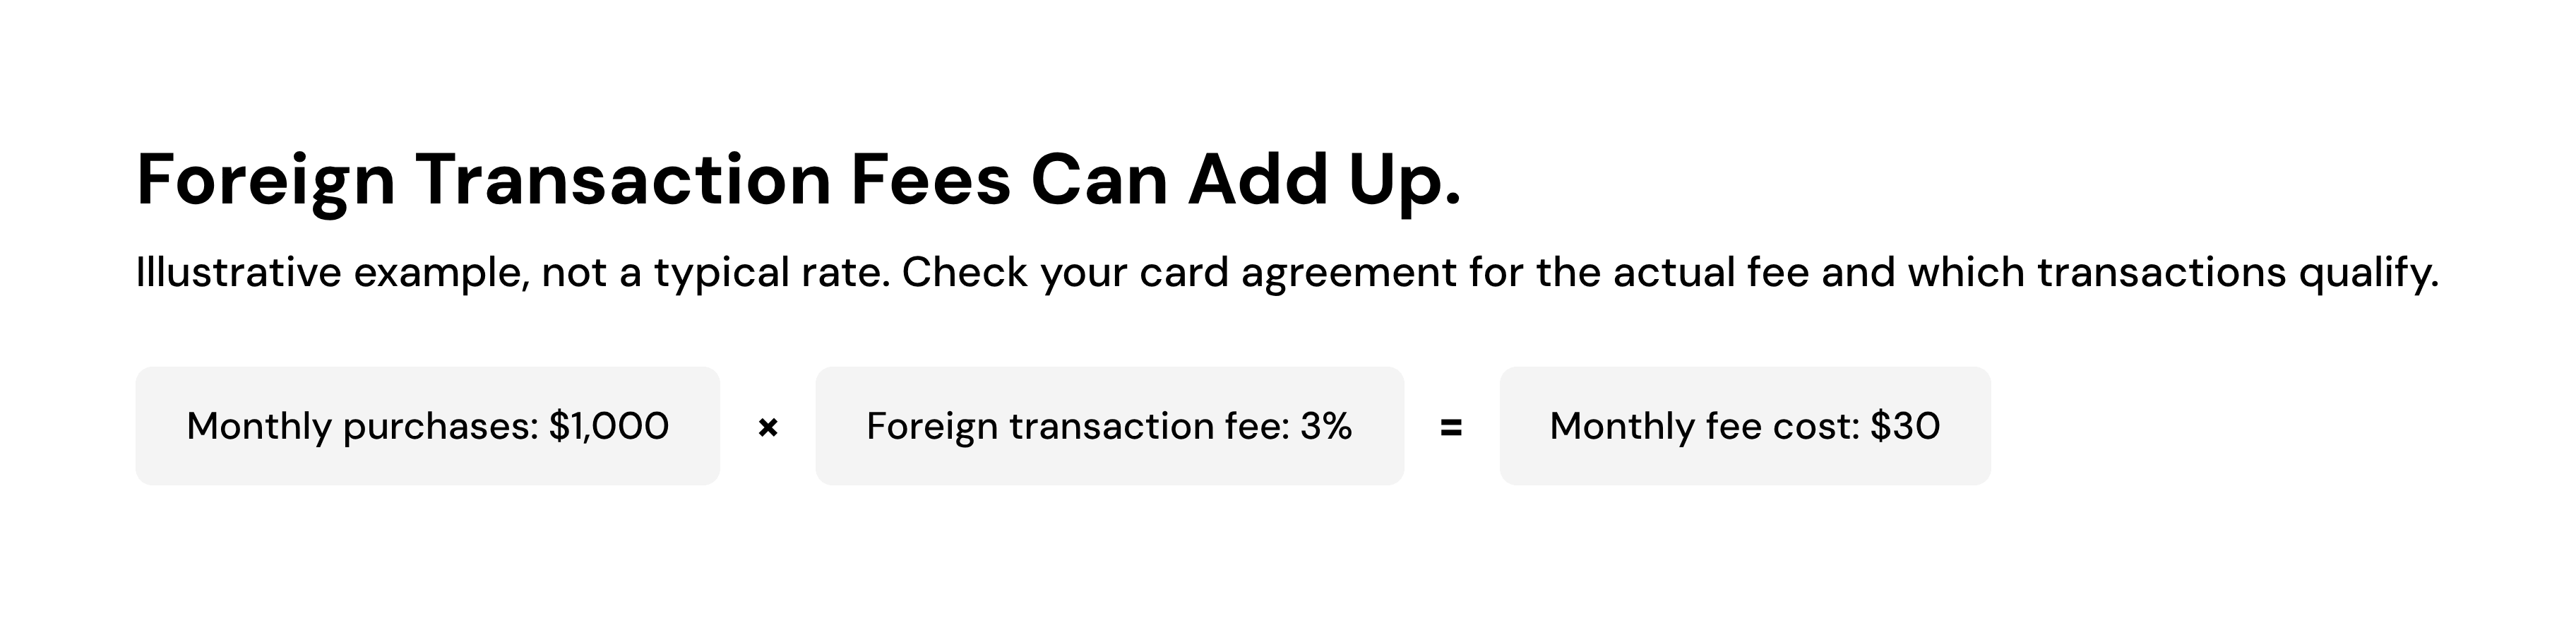
If your issuer allows you to use the account abroad, consider an occasional small purchase. Pay the statement balance in full when possible, and check for foreign transaction fees before using the card.
Ask the issuer about its inactivity policy, since occasional use does not guarantee that an account will stay open. If a card has an annual fee, ask whether you can switch to a no-fee version before deciding whether to keep it.
Check eligibility before using a credit-building app
An app being available online does not mean you can use it while living abroad. Before applying, check the provider’s residency rules, supported countries, fees, and credit-bureau reporting.
Kikoff’s current terms require users to be physically present in the United States when using its services. If you already have an account and are planning a move, contact Kikoff before leaving to discuss how to handle it.
Check whether a credit-builder loan fits your situation
Before considering a credit-builder loan, confirm that the lender accepts applicants living in your destination country. Do not assume an online lender serves U.S. citizens abroad.
With a typical credit-builder loan, the money is held in a savings account while you make payments. Check the interest, fees, payment schedule, reporting practices, and when the funds become available.
If you already have accounts that report your payments, you may not need another loan just to build credit.
Read more >> What Happens if You Miss a Credit Card Payment
How the U.S. credit system works for expats
Moving overseas does not erase your U.S. credit history. Your reports can continue to show information about your U.S. accounts, including balances and payment history.
Citizenship alone does not establish a credit history. Your file depends on the accounts and information reported about you, and not every creditor reports to every bureau.
Continuing to manage eligible U.S. accounts can help you maintain a credit record while abroad. If your accounts close or stop reporting for a long time, you may eventually have too little recent information for some scoring models to generate a score.
You may also need to establish credit in your new country. Do not assume your U.S. credit history will automatically transfer to its credit system.
Read more >> How to Read a Credit Report
How foreign income and residency affect credit
Moving abroad does not directly change your U.S. credit score, and income is not a credit-scoring factor. But both your residency and your income can affect a lender’s decision to approve an application.
Some U.S. lenders restrict accounts for people living overseas. Others may accept foreign income but require additional documentation, so ask about eligibility and income verification before applying.
If you earn money in another currency but owe payments in U.S. dollars, exchange-rate changes can also affect your budget. Plan for that difference so a more expensive transfer does not leave you short on a payment.
Common mistakes to avoid
Want to make managing your U.S. credit easier while abroad? Watch out for these common mistakes:
- Assuming a U.S. mailing address satisfies a provider’s residency requirements
- Closing every U.S. account without considering fees, usefulness, and eligibility
- Forgetting to update your bank or card issuer about the move
- Losing access to the phone number used for account verification
- Leaving too little time or money for international transfers
- Ignoring statements and U.S. credit reports while abroad
Before leaving, test your account access, confirm payment arrangements, and save your providers’ international contact numbers. If you are struggling to manage debt payments, a nonprofit credit counselor can help you review your options.
Bottom line
Keeping your U.S. credit active starts with accounts you’re allowed to use abroad and payments you can manage from overseas. Before moving, confirm your providers’ rules, test your account access, and make sure your payment arrangements are ready.
Whether you’re preparing to leave or returning home, building U.S. credit can be part of your plans. Kikoff’s Credit Account reports your on-time payments to all three credit bureaus, with no hard credit check to sign up. Kikoff requires you to be physically present in the U.S. when using its services, so if a move is coming up, contact support before opening an account.
Frequently Asked Questions
Disclaimer: The information provided in this blog post is meant for informational purposes only and does not constitute financial advice.