

Yes, a balance transfer can temporarily affect your credit score, especially if you apply for a new card. The application may add a hard inquiry, and the new account can lower the average age of your credit accounts. Your utilization can also change, for better or worse, depending on the new card’s limit and what you do with the old account.
A balance transfer can still be useful if it reduces your interest costs and helps you pay down debt. The key is to compare the fee, promotional period, regular APR, and monthly payment before applying.
How does a balance transfer affect your credit score?
A balance transfer moves debt from one credit card to another. It does not erase the debt. The transfer itself is not a separate credit-scoring factor, but opening and using the new account can affect several parts of your credit profile.
A new application can create a hard inquiry
When you apply for a balance transfer card, the issuer will usually review your credit through a hard inquiry. According to FICO, one additional inquiry lowers FICO Scores by fewer than five points for most people, although the effect varies by credit profile.
Applying for several credit cards in a short period can have a larger effect because each application may generate another inquiry.
A new account can lower your average account age
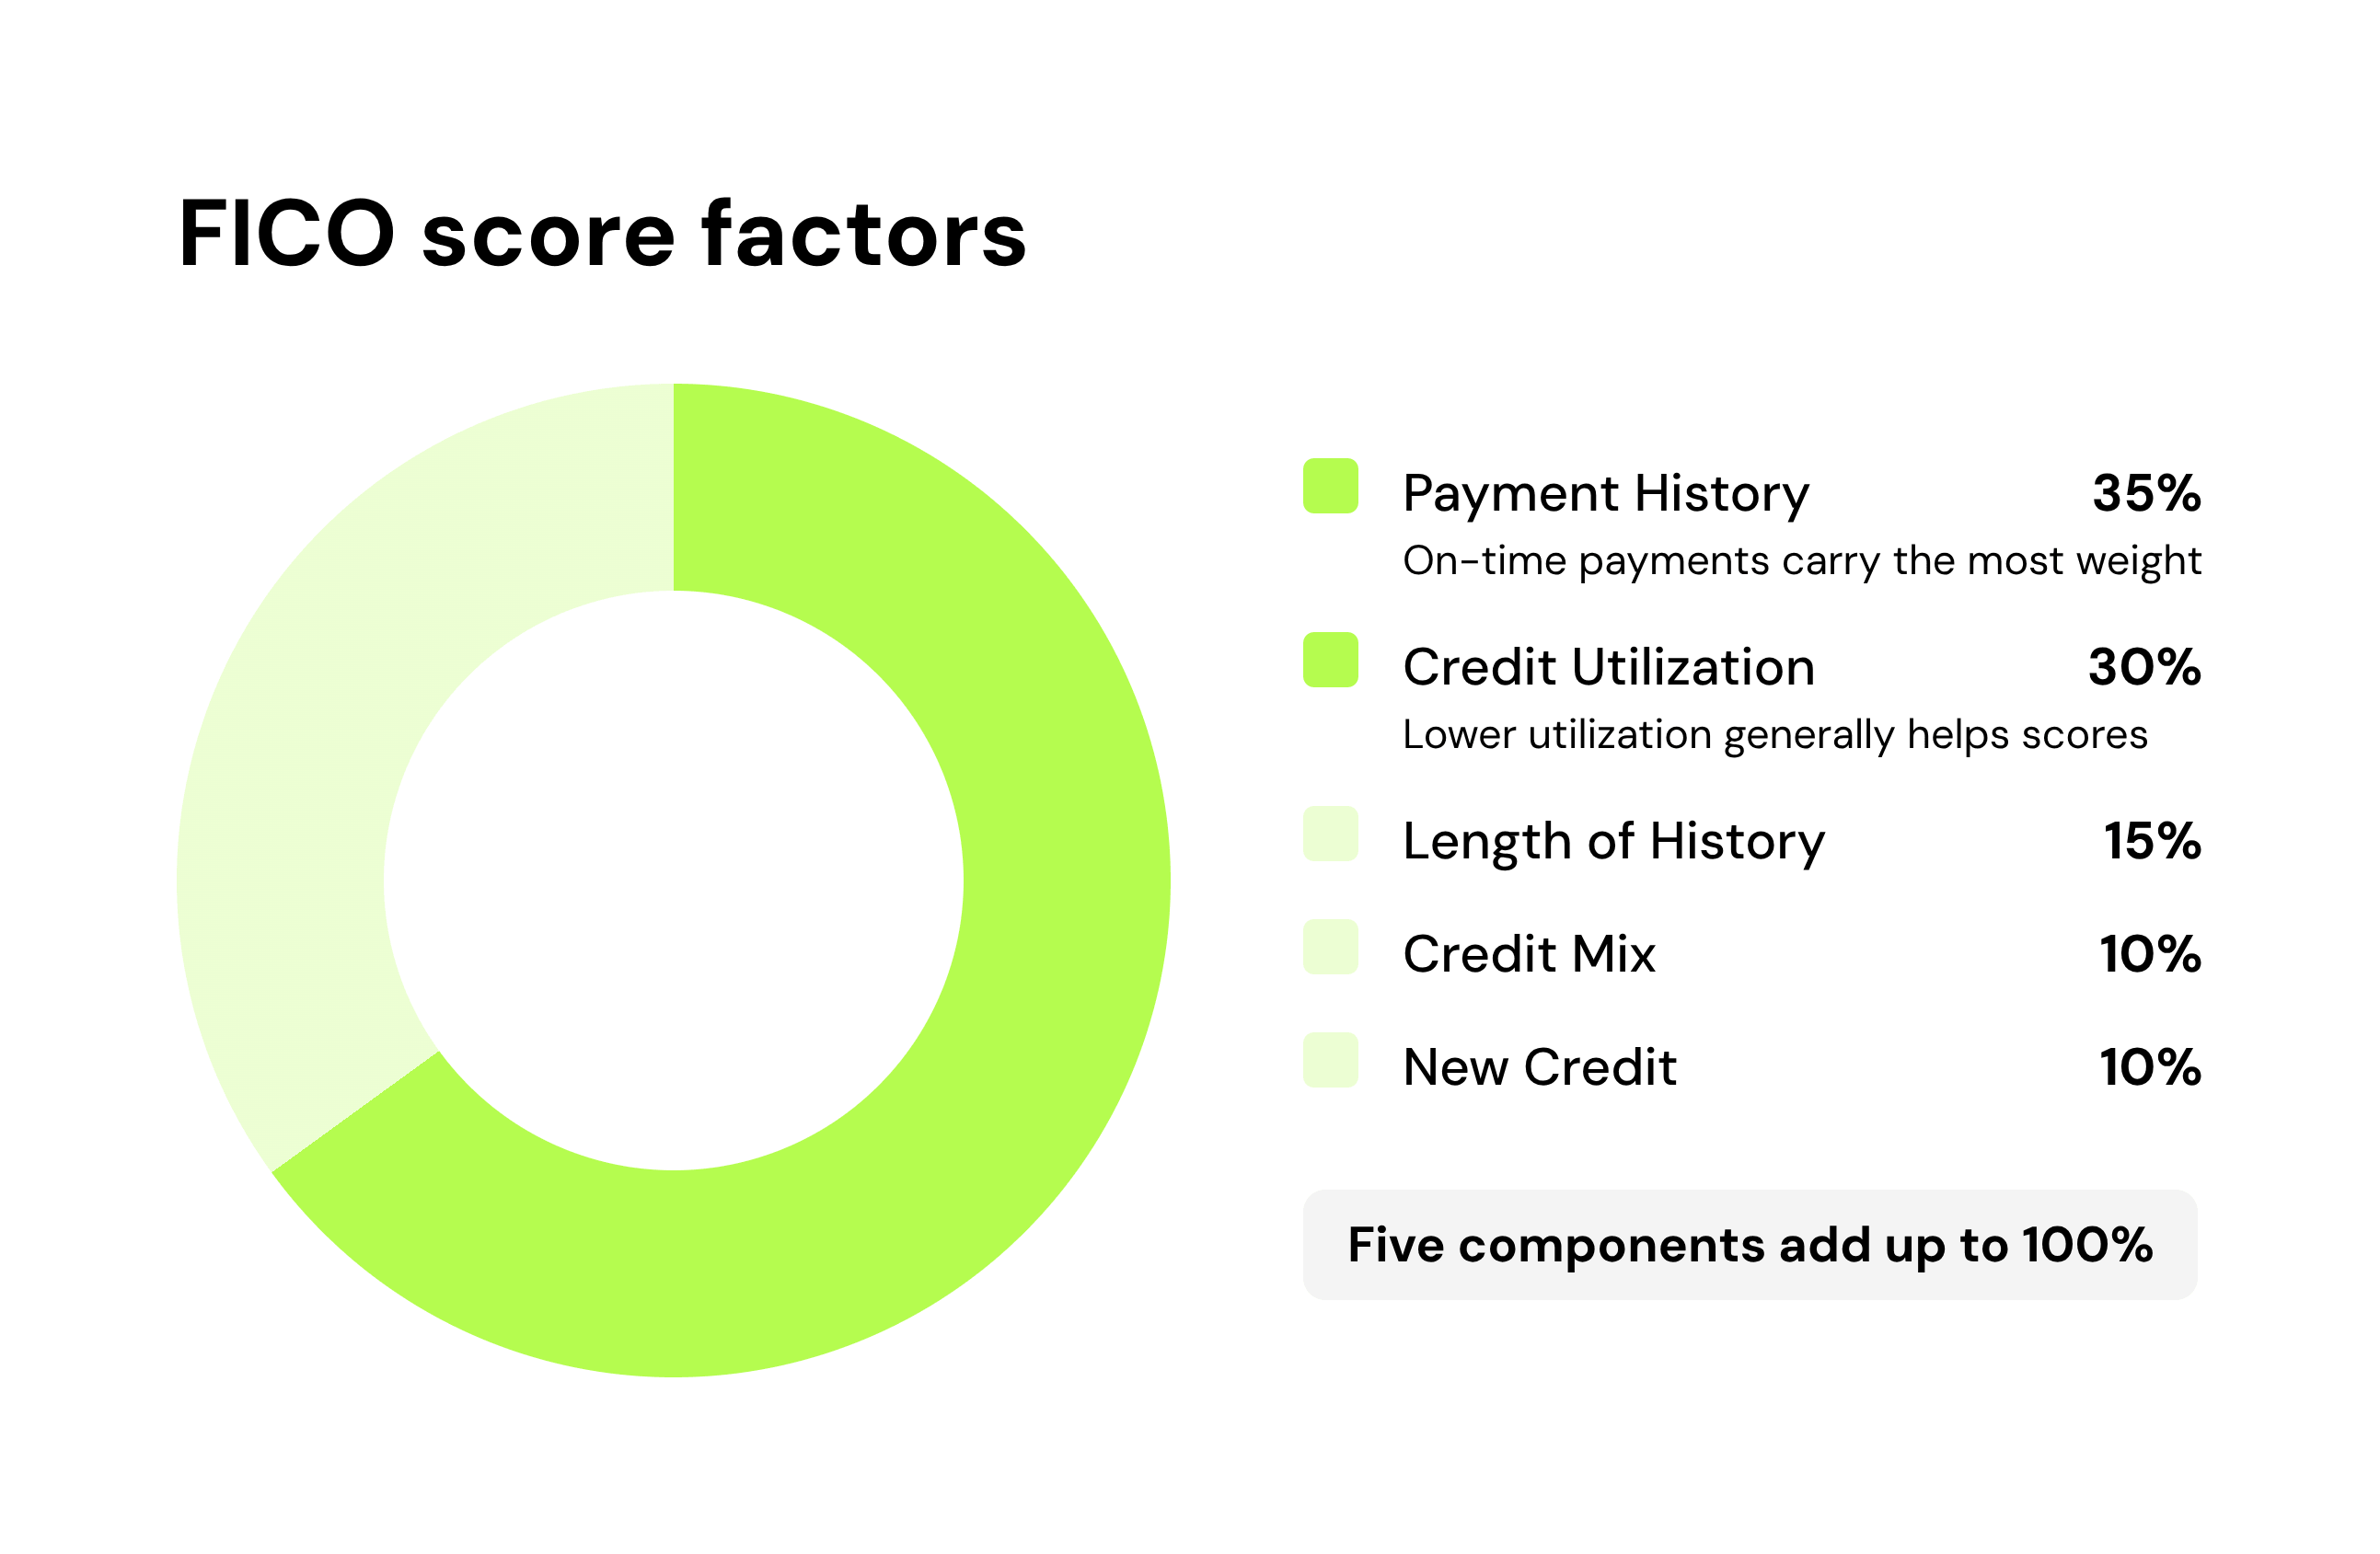
Opening a new card can reduce the average age of your accounts. Length of credit history makes up about 15% of a FICO Score, so the effect may be more noticeable if your credit history is short or you recently opened other accounts.
The impact generally becomes less significant as the account ages, assuming you manage it responsibly and avoid repeatedly opening new cards.
Your credit utilization can rise or fall
Credit utilization is the percentage of your available revolving credit that you are using. A new balance transfer card adds another credit limit, which may lower your overall utilization if you keep the old card open and do not add more debt.
However, the transferred balance could produce high utilization on the new card. For example, transferring $4,000 to a card with a $5,000 limit would make that card’s utilization 80%. Credit-scoring models may consider both overall utilization and utilization on individual cards.
Closing the old card can also reduce your total available credit and push overall utilization higher. Keeping it open may help preserve available credit, but only if the card’s costs and the temptation to spend do not outweigh that benefit.
A balance transfer changes where your debt sits. Paying down the balance is what reduces the debt itself.
Can a balance transfer help your credit over time?
It can, but results vary. The strongest potential benefit comes from using the promotional period to reduce your balance while making every required payment on time.
Lower balances can reduce utilization.
Paying down revolving debt reduces the amount of available credit you are using. Because amounts owed make up about 30% of a FICO Score, lower reported balances may help your score over time.
Simply moving the same debt between cards is less important than consistently reducing the total balance. Avoid charging new purchases to the old or new card unless they fit within your payoff plan.
On-time payments protect your payment history.
Payment history is the largest FICO scoring category. Set up autopay for at least the minimum amount due, then make additional payments according to your debt-payoff plan.
Paying the full transferred balance before the promotional period ends can help you avoid the card’s regular balance-transfer APR on any amount left over. Check the card agreement for the exact end date and post-promotional rate.
Read more >> What Happens If You Miss a Credit Card Payment?
When is a balance transfer worth it?
A balance transfer may make sense when the fee is lower than the interest you expect to avoid and the required payoff amount fits your monthly budget.
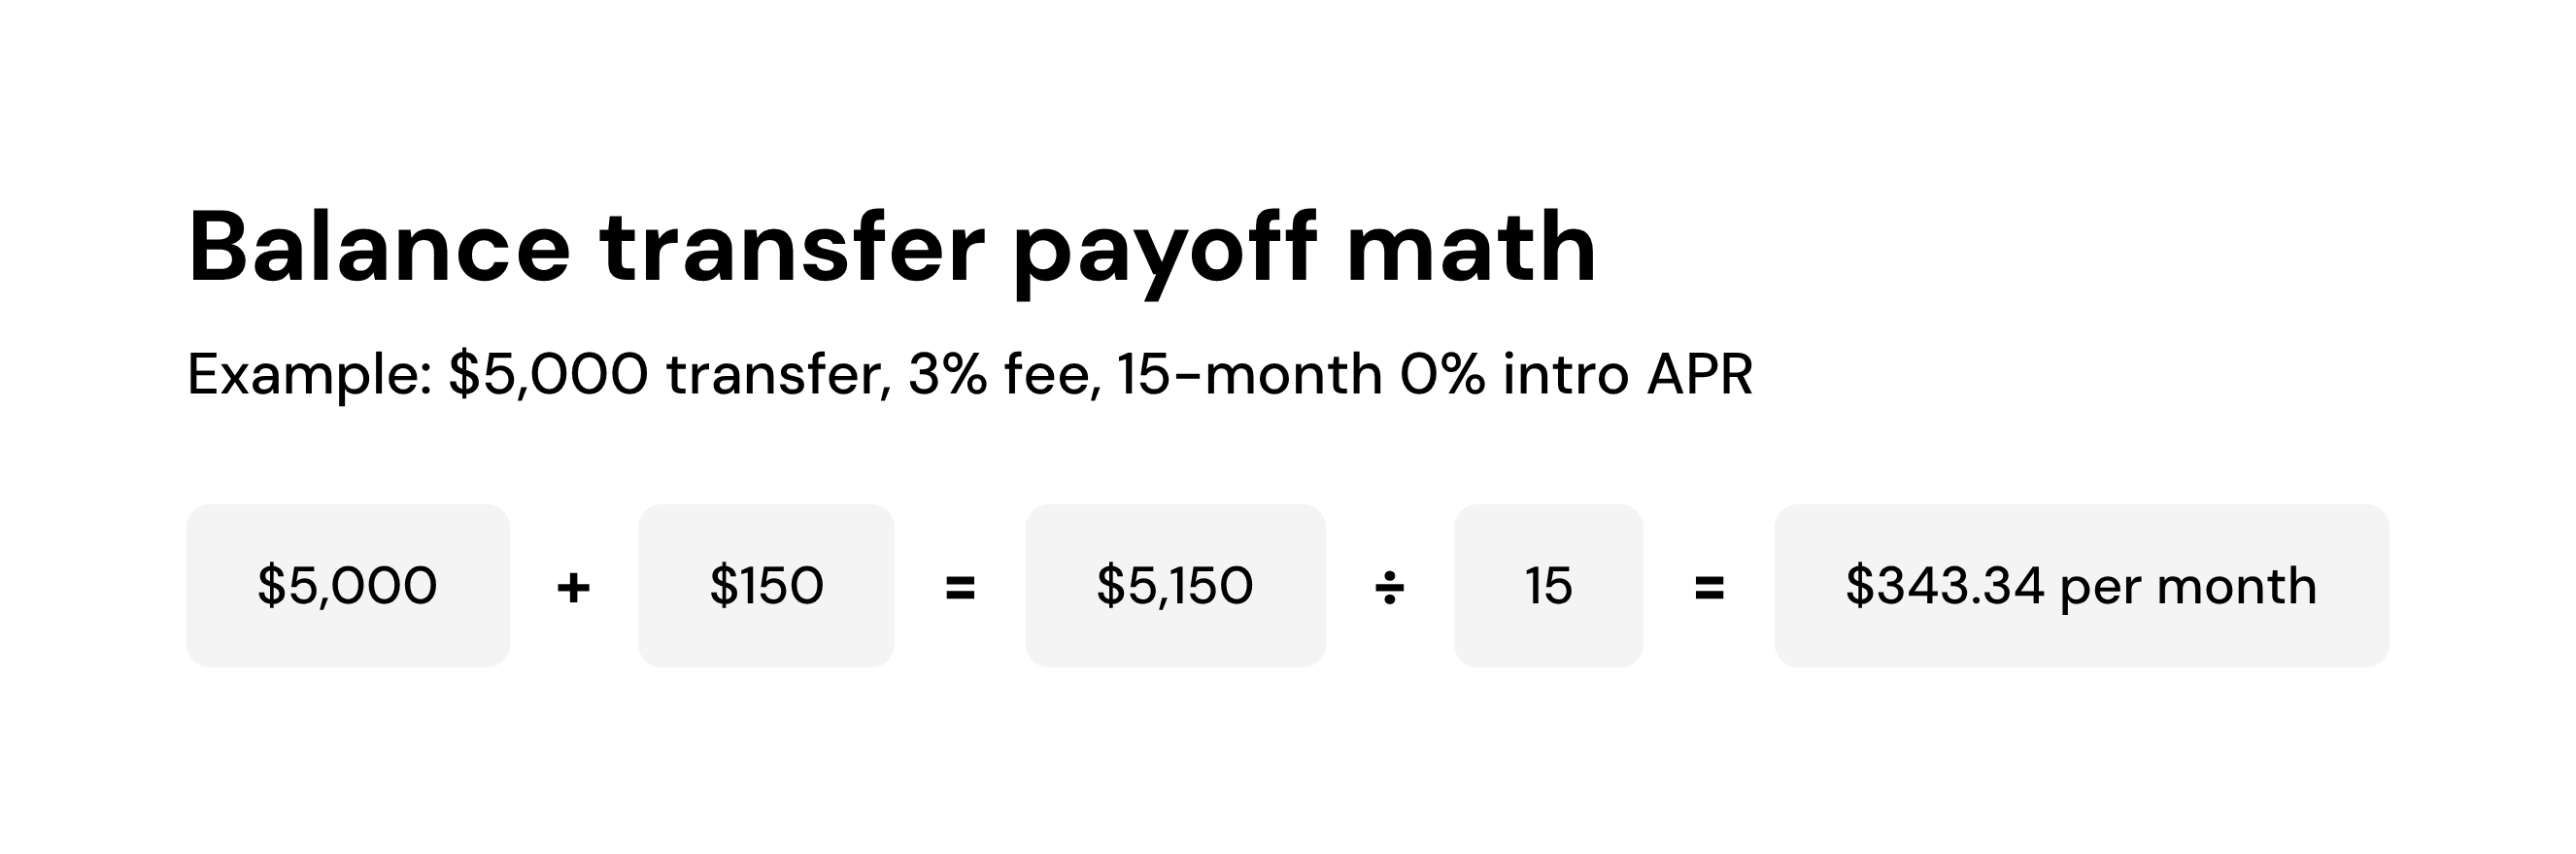
Suppose you transfer a $5,000 balance, pay a 3% transfer fee, and receive a 15-month 0% introductory APR. The fee would add $150, bringing the balance to $5,150. You would need to pay about $343.34 per month to clear it within 15 months, assuming you make no new charges and incur no other fees.
Before applying, confirm:
- The balance-transfer fee and any minimum fee
- The promotional APR and how long it lasts
- The regular APR after the promotion
- How soon the transfer must be completed
- The credit limit available for the transfer
- Whether you can make the monthly payment needed to finish on time
If you expect to apply for a mortgage or another major loan soon, consider asking the lender how opening a new card could affect your application.
Balance transfer risks to watch for
A 0% balance-transfer offer does not necessarily make the entire card interest-free. The Consumer Financial Protection Bureau warns that, on many cards, new purchases may begin accruing interest even while the transferred balance has a promotional APR.
Other risks include:
- Adding new debt after freeing up room on the old card
- Receiving a credit limit too low to transfer the full balance
- Missing a payment and facing a late fee or other consequences under the card agreement
- Carrying a balance after the promotional APR expires
- Paying a transfer fee that outweighs the expected interest savings
Read the card’s disclosures rather than assuming the promotional rate applies to purchases or lasts indefinitely.
Read more >> What Is the Credit CARD Act of 2009?
Alternatives to a balance transfer
If the numbers do not work or you do not qualify for a suitable offer, consider other options:
- Ask your current issuer whether it can reduce your APR
- Use the debt avalanche method to prioritize the highest-interest balance
- Use the debt snowball method to pay off the smallest balance first for momentum
- Speak with a nonprofit credit counselor about a debt management plan
- Compare a fixed-rate debt consolidation loan, including its APR, fees, and total repayment cost
Avoid applying for several products at once. Compare eligibility information and terms before submitting a full application whenever possible.
Bottom line
A balance transfer can cause a small, temporary credit-score change because of the hard inquiry and new account. Its longer-term effect depends more on utilization, payment history, and whether you actually pay down the debt.
If you use a transfer, calculate the monthly payment needed to finish before the promotional period ends, avoid new purchases, and pay on time. A balance transfer is most useful as a structured payoff tool, not as extra spending room.
Paying down debt and building positive payment history are separate goals. If you are also working on your credit, Kikoff offers plans that report your balance and on-time payments to Equifax, Experian, and TransUnion. You can sign up without a credit check.
Frequently Asked Questions
Article Sources
Disclaimer: The information provided in this blog post is meant for informational purposes only and does not constitute financial advice.