



The three types of credit are revolving credit, installment credit, and open credit.
Each type works differently, gets reported differently, and plays a different role in your credit profile. Understanding all three helps you make smarter decisions about which accounts to open, keep, and use.
The 3 types of credit
The three types of credit are defined by how you borrow and repay money. Understanding the differences can help you recognize how various credit accounts work and how lenders may evaluate your borrowing habits.
Revolving credit
Revolving credit is effectively a credit line that resets as you pay it down, letting you borrow, repay, and borrow again up to a set limit.
The most common examples are:
- Credit cards
- Store credit cards
- Gas cards
- Secured credit cards
- Home equity lines of credit (HELOCs)
Unlike a loan that you pay off over a fixed schedule, revolving credit gives you ongoing access to funds up to your limit.
This type of credit has the most direct impact on your credit score because it touches two of the biggest scoring factors simultaneously: payment history (35%) and amounts owed (30%).
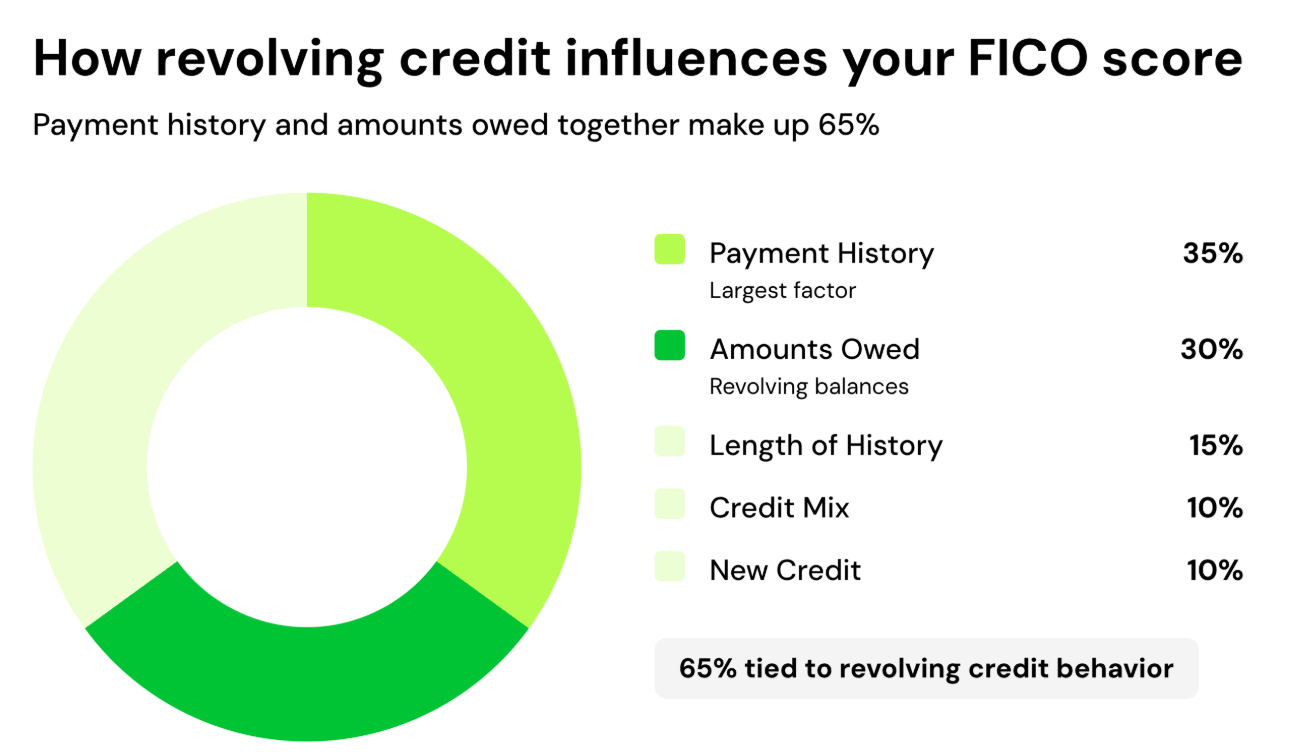
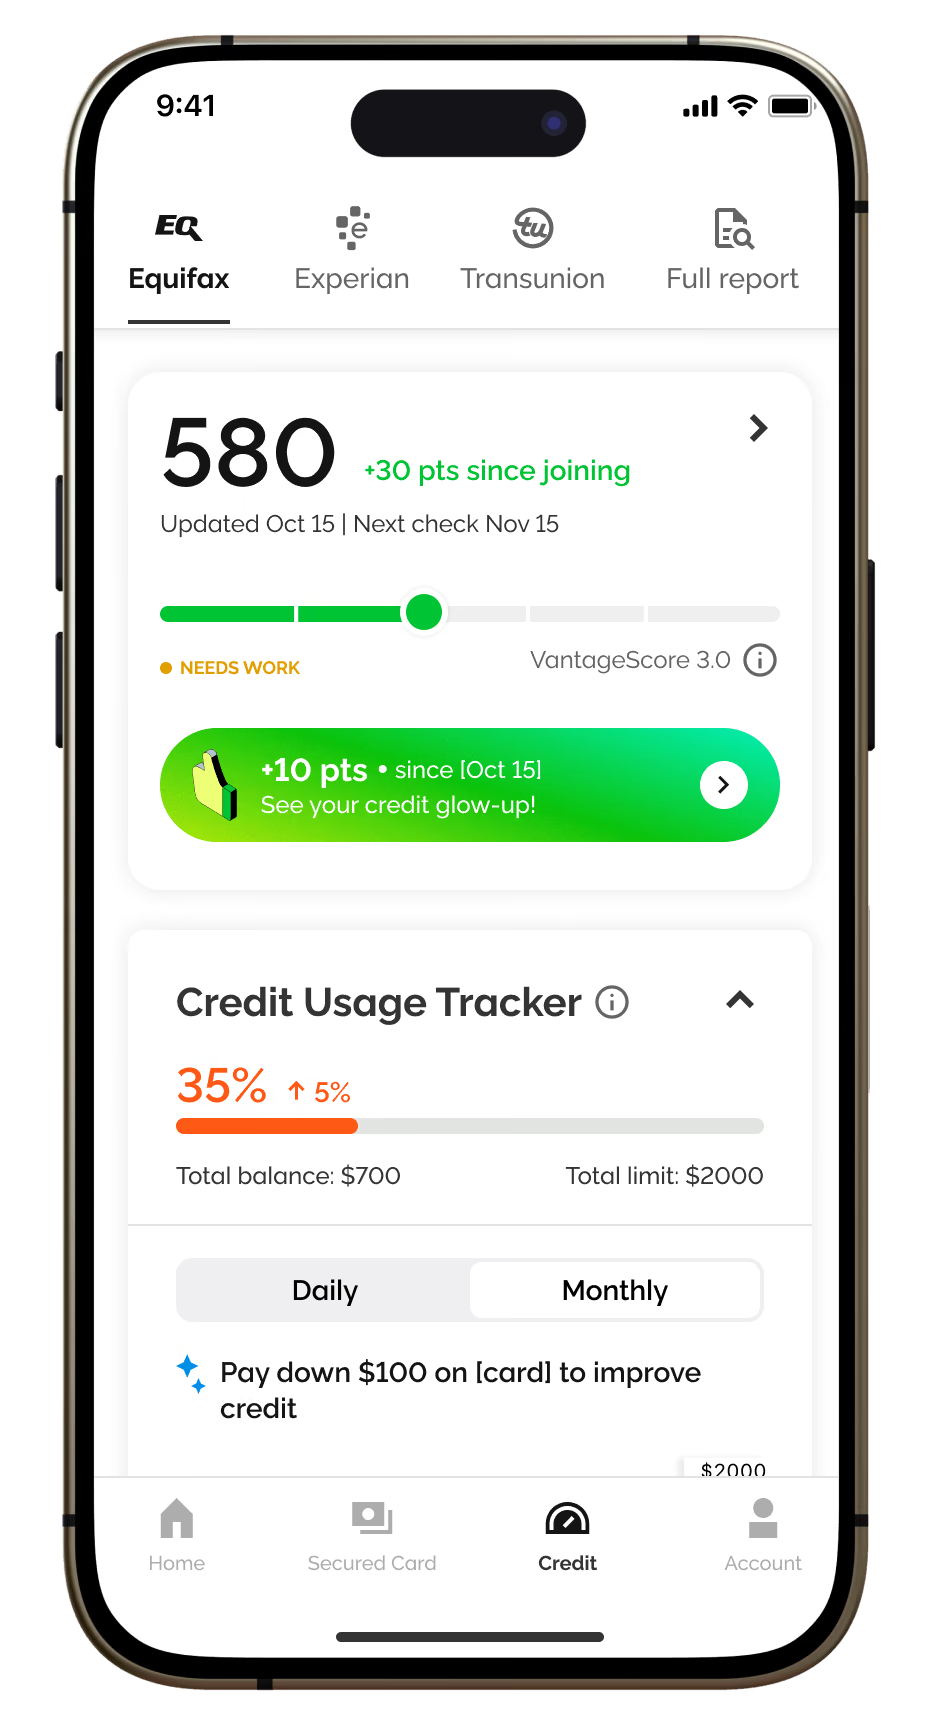
Because revolving credit affects so many scoring factors at once, it is the single most efficient credit type for building your score. Tools like the Kikoff Credit Account give you access to a revolving tradeline that reports to all three major credit bureaus, making it a super effective starting point for building credit, be it from scratch or after a setback.
Installment credit
Installment credit is effectively a loan you repay in fixed monthly payments over a set period until the balance reaches zero.
Common examples include:
- Auto loans
- Student loans
- Personal loans
- Mortgages
- Credit-builder loans (CBLs)
Installment credit mainly builds your payment history (35% of your score). They also contribute to your credit mix (10%), which is a measure of the variety of credit types you have managed. Lenders generally see a diverse credit mix as a positive signal, especially if you have managed both revolving and installment accounts responsibly.
One category of installment credit worth addressing is credit-builder loans (CBLs). CBLs are small loans specifically designed to help people build payment history, and they are marketed to people with thin or no credit. However, they have a few limitations worth knowing. CBLs only build payment history, they lock up your funds for the duration of the loan term, and they usually carry interest and fees.
Open credit
Open credit is effectively a credit arrangement where the full balance is due each billing cycle.
The most common examples are:
- Charge cards
- Utility accounts
- Some cell phone plans
Open credit does not carry over a balance from month to month the way revolving credit does, and it does not follow a fixed repayment schedule the way installment credit does.
Most utility and phone accounts are not reported to the credit bureaus by default, which means they do not automatically build your credit history even if you pay on time. Luckily, rent reporting services can help bridge a similar gap by adding verified on-time rent payments to your credit file, and Kikoff plans include rent reporting starting at $5 a month.
Charge cards, which are a form of open credit issued by some financial institutions, are generally reported to the bureaus and can positively affect your payment history if paid in full each cycle.
Why the mix of credit types matters
Your credit mix makes up 10% of your FICO score, which means the variety of credit types you have managed does factor into where your score lands.
Lenders generally look more favorably on borrowers who have successfully managed multiple types of credit, be it a credit card, an auto loan, or a mortgage. This shows that you can handle different kinds of financial commitments without falling behind.
That said, you should never open a new account just to diversify your credit mix. The impact is relatively small compared to payment history and amounts owed, and unnecessary hard inquiries can temporarily lower your score.
How to build credit across multiple types
Building credit across all three types does not happen overnight, but there is an order that makes the process efficient.

Start with revolving credit first, since it affects the most scoring factors simultaneously. A secured credit card or a revolving credit account like the one Kikoff offers is a great first step because there is no hard credit check to sign up, and every on-time payment gets reported directly to the three major bureaus.
From there, installment credit naturally enters the picture when you have a real need for it, such as financing a car or taking out a student loan. Just make sure you budget carefully before taking on any installment debt, since missed payments on loans can do lots of damage to your credit score.
Open credit, like utility accounts, is generally not something you need to seek out specifically. If you do want to get credit for your utility or phone payments, services that report those to the bureaus can help fill that gap.
The main principle to keep in mind is that consistent, on-time payments across whichever accounts you hold is what builds a healthy credit profile over time.
Read more >> How Long Does It Take to Build Credit?
Bottom line
The three types of credit are revolving, installment, and open. Each plays a different role in your credit profile, and understanding how they work helps you make more informed decisions about your financial life.
Revolving credit is generally the most impactful type for building your score because it affects both payment history and amounts owed. Installment credit adds depth through credit mix and a track record of managing fixed loan payments. Open credit is the least commonly reported, but can still contribute when used with the right accounts.
If you are looking to start building credit or add positive history to your file, Kikoff is a great place to start. Sign up without a hard credit check and start building a positive payment history reported to all three major credit bureaus.
Frequently Asked Questions
Disclaimer: The information provided in this blog post is meant for informational purposes only and does not constitute financial advice.