


A cash advance isn’t only cash from an ATM. Card companies also treat “cash equivalents” as cash advances, and that can include buying cryptocurrency, sending peer-to-peer transfers, or buying lottery tickets.
The tricky part is that the card itself doesn’t warn you. Checkout looks the same as any other purchase, and the cost shows up later on your statement. If you’ve ever been surprised by a fee you didn’t expect, that’s probably what happened. The CFPB found that some cardholders were caught off guard by cash advance fees on sports bets they assumed were regular purchases.
What is a cash advance?
A cash advance is when you use your credit card to get cash or something your card issuer treats like cash. You’re borrowing against your credit line, the same way you would with a purchase. But your issuer prices it differently.
Most cards set a separate cash advance limit, meaning the most you can take out this way. It’s often lower than your overall credit limit, and you’ll find it on your monthly statement.
A cash advance also isn’t the same as cash back. Cash back at a grocery store checkout with a debit card comes out of your own checking account. A cash advance is money you borrow on your credit card, and you pay it back with interest.
Read more >> What Is a Cash Advance and How Does It Work?
Transactions that count as cash advances
Any transaction that gets you cash, or something you can easily turn into cash, can count as a cash advance. Card companies call these “cash like” transactions or “cash equivalents.” Each issuer sets its own list, so check your cardholder agreement.
ATM withdrawals with your credit card
This is the classic cash advance. You put your credit card in an ATM, enter a cash advance PIN, and take out cash. Getting cash from a bank teller with your credit card works the same way.
Watch for a second fee too. The ATM’s owner may charge you on top of your issuer’s fee, so one withdrawal can cost you twice.
Convenience checks
Convenience checks are blank checks your card issuer mails you that draw on your credit line. They look like regular checks, but you’re borrowing every dollar you write. With these checks, you generally start paying interest from the date of the transaction, just like a cash advance.
Sometimes the checks come with a promotional rate. Read the offer’s fine print before you use one, because it may still carry a fee. If you don’t plan to use them, shred them so no one else can.
Money orders and wire transfers
Money orders and wire transfers move money that’s as good as cash, so card companies usually price them like cash. If you’re buying a money order at a store or sending a wire through a transfer service, ask whether you can pay with a debit card instead.
Cryptocurrency purchases
Buying crypto with a credit card can trigger a cash advance fee, and some card companies won’t allow these purchases at all. If you’re funding an exchange account, a transfer from your bank account usually gets around the issue.
Casino chips and gambling transactions
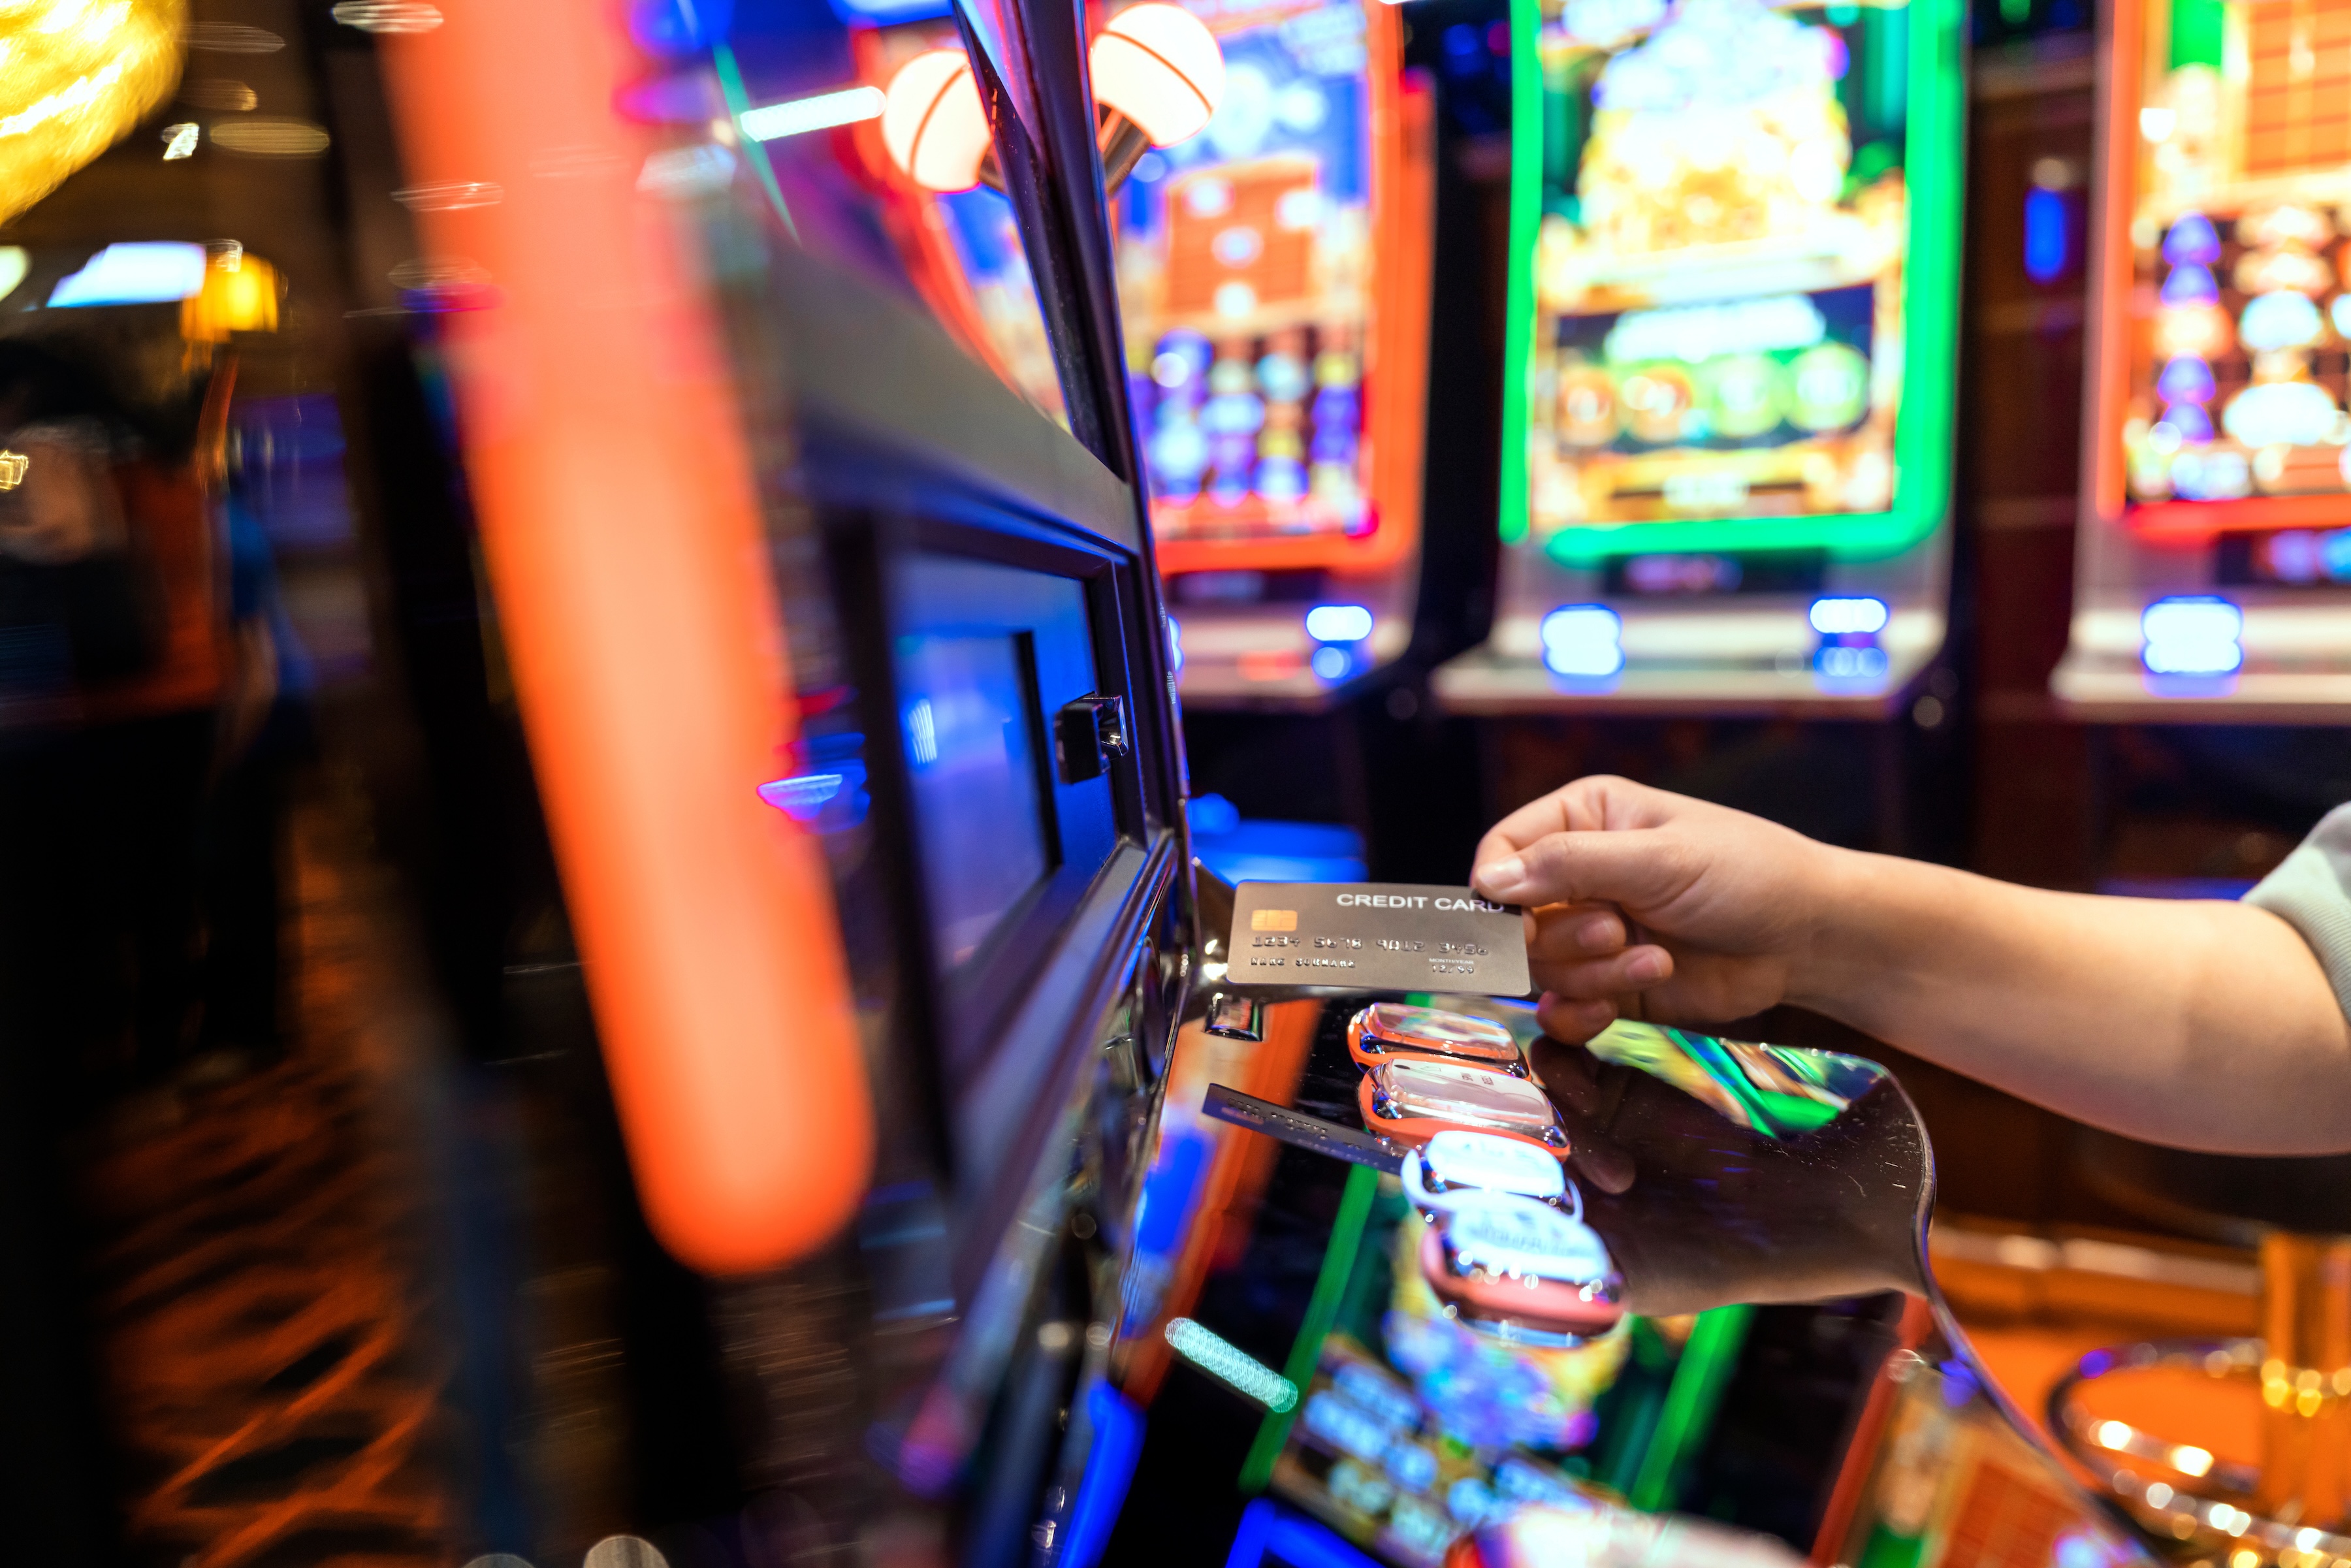
Casino chips, lottery tickets, and bets usually count as cash advances, including bets you place in a sports betting app. When the CFPB reviewed card agreements from seven top issuers, every one listed online gambling or legal wagers as cash advances.
Don’t count on the sportsbook app to warn you. The payment screen looks the same as any other card payment, so the fee isn’t obvious until it shows up later on your statement.
Peer-to-peer payment apps
Paying a friend back through an app like Venmo or PayPal with your credit card can count as a cash advance. Venmo’s help center says some card companies charge cash advance fees for these payments. Chase, for example, says it now treats money transfers and account funding as cash advances.
Then there’s the app’s own fee. Venmo’s standard fee for credit cards is 3%, which means you could end up paying twice for the same transfer. Linking your bank account or debit card avoids both.
Paying a business in the same app is often treated differently from paying a friend. If you’re not sure which one you’re doing, check before you tap send.
Foreign currency purchases
Buying foreign cash with your credit card, like at an airport currency exchange counter, usually counts as a cash advance. So does pulling local currency from an ATM abroad with your credit card.
Everyday purchases abroad are different. Paying for dinner or a hotel with your credit card in another country is a purchase, not a cash advance. You may pay a foreign transaction fee, but that’s a separate charge.
Loan payments made with a credit card
Many lenders don’t take credit cards for loan payments. If you use a third-party payment to get around that, your issuer may treat the payment as “cash like.” Some cardholder agreements list debt payments as cash advances.
Before you pay a loan this way, call your card issuer and ask whether the payment posts as a purchase or a cash advance.
Read more >> Can You Pay Your Car Loan With a Credit Card?

Why cash advances cost more than regular purchases
A cash advance usually hits you three ways: a fee up front, a higher interest rate, and interest that starts right away. Together, they add up quickly. Major card companies charged $717 million in cash advance fees on $3.6 billion in cash advances in 2022, according to the CFPB. That works out to about $1 in fees for every $19 advanced.
Higher interest rates
Your card has a separate annual percentage rate (APR) for cash advances, and it’s usually higher than the rate on everyday purchases. The most common cash advance APR in the card agreements the CFPB reviewed was 30%, several percentage points higher than the average 22% reported by the Federal Reserve.
No grace period
A grace period is the time between the end of your billing cycle and your payment due date. If you pay your full balance by the due date, you usually don’t pay interest on purchases.
Cash advances generally don’t get a grace period. Interest typically starts the day of the transaction, so even if you pay your card in full every month, a cash advance can still cost you interest.
Cash advance fees
Most of the card agreements the CFPB reviewed charge the greater of $10 or 5% of the transaction. That minimum hits small transactions hardest. A $20 bet and a $200 ATM withdrawal could both cost you a $10 fee.
Running the numbers: How costs add up on a $200 cash advance
One rule works in your favor: Federal rules require issuers to put any amount above your minimum payment toward the balance with the highest APR first, which is often the cash advance. So paying even a little more than the minimum goes after the priciest part of your balance first. Pay only the minimum, and that balance can hang around longer.
To keep an eye on that balance, Kikoff’s credit monitoring shows how much of your available credit you’re using as you pay it down.
What a cash advance does (and doesn’t do) to your credit. A cash advance doesn’t show up as a separate item on your credit report. It’s added to your card balance, so it raises how much of your available credit you’re using until you pay it down. Paying on time still counts.
How to check if a transaction will be treated as an advance
Your card issuer makes the call, and its rules are in writing. Check before a transaction you’re unsure about, not after it posts.
- Read your cardholder agreement. Look in the cash advance section for terms like “cash like transactions” or “cash equivalents.” You can usually find the agreement in your card’s app or online account, or search the CFPB’s database of credit card agreements.
- Find your cash advance APR, fee, and limit. They’re listed separately from your purchase terms on your statement or in your app.
- Call the number on the back of your card. Ask how a payment to that company posts, either as a purchase or a cash advance. Write down the date and the rep’s name, in case the charge comes out differently.
- Look for a warning at checkout. Some apps and sites mention possible issuer fees. If you see one, that’s your cue to switch payment methods.
Card companies often decide based on how the seller is categorized in the payment network, not on what you’re buying. That’s why the same app can be a purchase one time and a cash advance another, depending on who you’re paying.
What if you already got charged? Check your statement for a line labeled “cash advance fee.” If it was a one-time mistake, call your card issuer and ask whether it can waive the fee. If you think the transaction was coded wrong, dispute it with your issuer. Then pay down that balance first, since it’s collecting interest every day.
How to avoid accidental cash advances
The simplest fix is to keep your credit card for purchases and use your bank account for anything that moves money. A few habits make that easier.
- Move money with your debit card or bank account. That covers ATM cash, payment app transfers to friends, money orders, wire transfers, crypto exchanges, and betting accounts.
- Check which card your payment apps use by default. If it’s a credit card, switch it to your bank account or debit card. Check again any time you add a new card to the app.
- Ask your issuer to lower or turn off your cash advance limit. If it agrees, an accidental cash advance is more likely to get declined than charged.
- Shred convenience checks you won’t use. They can show up with your statement or in their own envelope.
- Skip the cash advance PIN unless you need one. Without it, you can’t pull cash from an ATM with the card by mistake.
If you only need a small amount to get to payday, compare a cash advance app before you use your credit card. Grant Cash Advance offers $25 to $500 to eligible customers with no interest, no credit check, and no late fees. Standard delivery is free and takes one to three business days, with same-day delivery from $2 to $21. Repayment comes out of your next paycheck automatically, so plan for that check to be smaller.
Call the company you owe first. If you’re reaching for a cash advance because a bill is due, that call costs nothing, and some companies offer hardship options. Ask whether you can get a few extra days or set up a payment plan.
For a bigger gap, work with a nonprofit credit counselor to take a broad look at your finances together. The National Foundation for Credit Counseling can connect you to free or low-cost debt counseling at 800-388-2227.
Bottom line
An ATM isn’t the only way to end up with a cash advance. Money orders, wire transfers, crypto, bets, some payment app transfers, and foreign cash can all come with a fee, a higher APR, and interest from day one. A quick look at your cardholder agreement, or a call to your card issuer, tells you before you pay.
When a cash advance feels like the only way to cover a gap, it’s often because lower-cost credit isn’t within reach yet. A stronger credit history can help you qualify for cheaper options, like a personal loan or a card with a lower APR, so the next emergency has more than one answer. Kikoff’s Credit Account reports your on-time payments to all three credit bureaus, with no credit check to sign up. Plans start at $5 a month.
Frequently Asked Questions
Article Sources
Disclaimer: The information provided in this blog post is meant for informational purposes only and does not constitute financial advice.