

Yes, FHA guidelines allow a borrower with a credit score of 500 to be considered for an FHA-insured mortgage. But 500 is an eligibility floor, not a promise of approval. You will generally need at least 10% down, and an FHA-approved lender may require a higher score or decide that other parts of your finances do not meet its underwriting standards.
If you are near 500, understanding the difference between FHA rules and lender approval standards can help you decide whether to apply now or spend more time strengthening your application.
Can you get an FHA loan with a 500 credit score?
You may qualify for an FHA loan with a 500 credit score if you meet the program's other requirements and find a lender willing to approve the application.
The Federal Housing Administration does not lend money directly. It insures mortgages issued by FHA-approved lenders, which reduces some of the lender's risk if a borrower defaults. The lender still reviews your income, debts, assets, credit history, and the property before making a decision.
A 500 credit score does not mean automatic approval. It means FHA rules may permit the loan, but the lender must still approve the full application.
Read more >> How to Get a Home Loan With Bad Credit
What FHA rules say about scores of 500 and 580
HUD's FHA Single Family Housing Policy Handbook connects the borrower's minimum decision credit score to the maximum loan-to-value ratio, or LTV. LTV compares the mortgage amount with the home's value.
Scores from 500 to 579
A borrower with a minimum decision credit score from 500 through 579 is limited to a 90% LTV. For a purchase, that generally means a down payment of at least 10%.
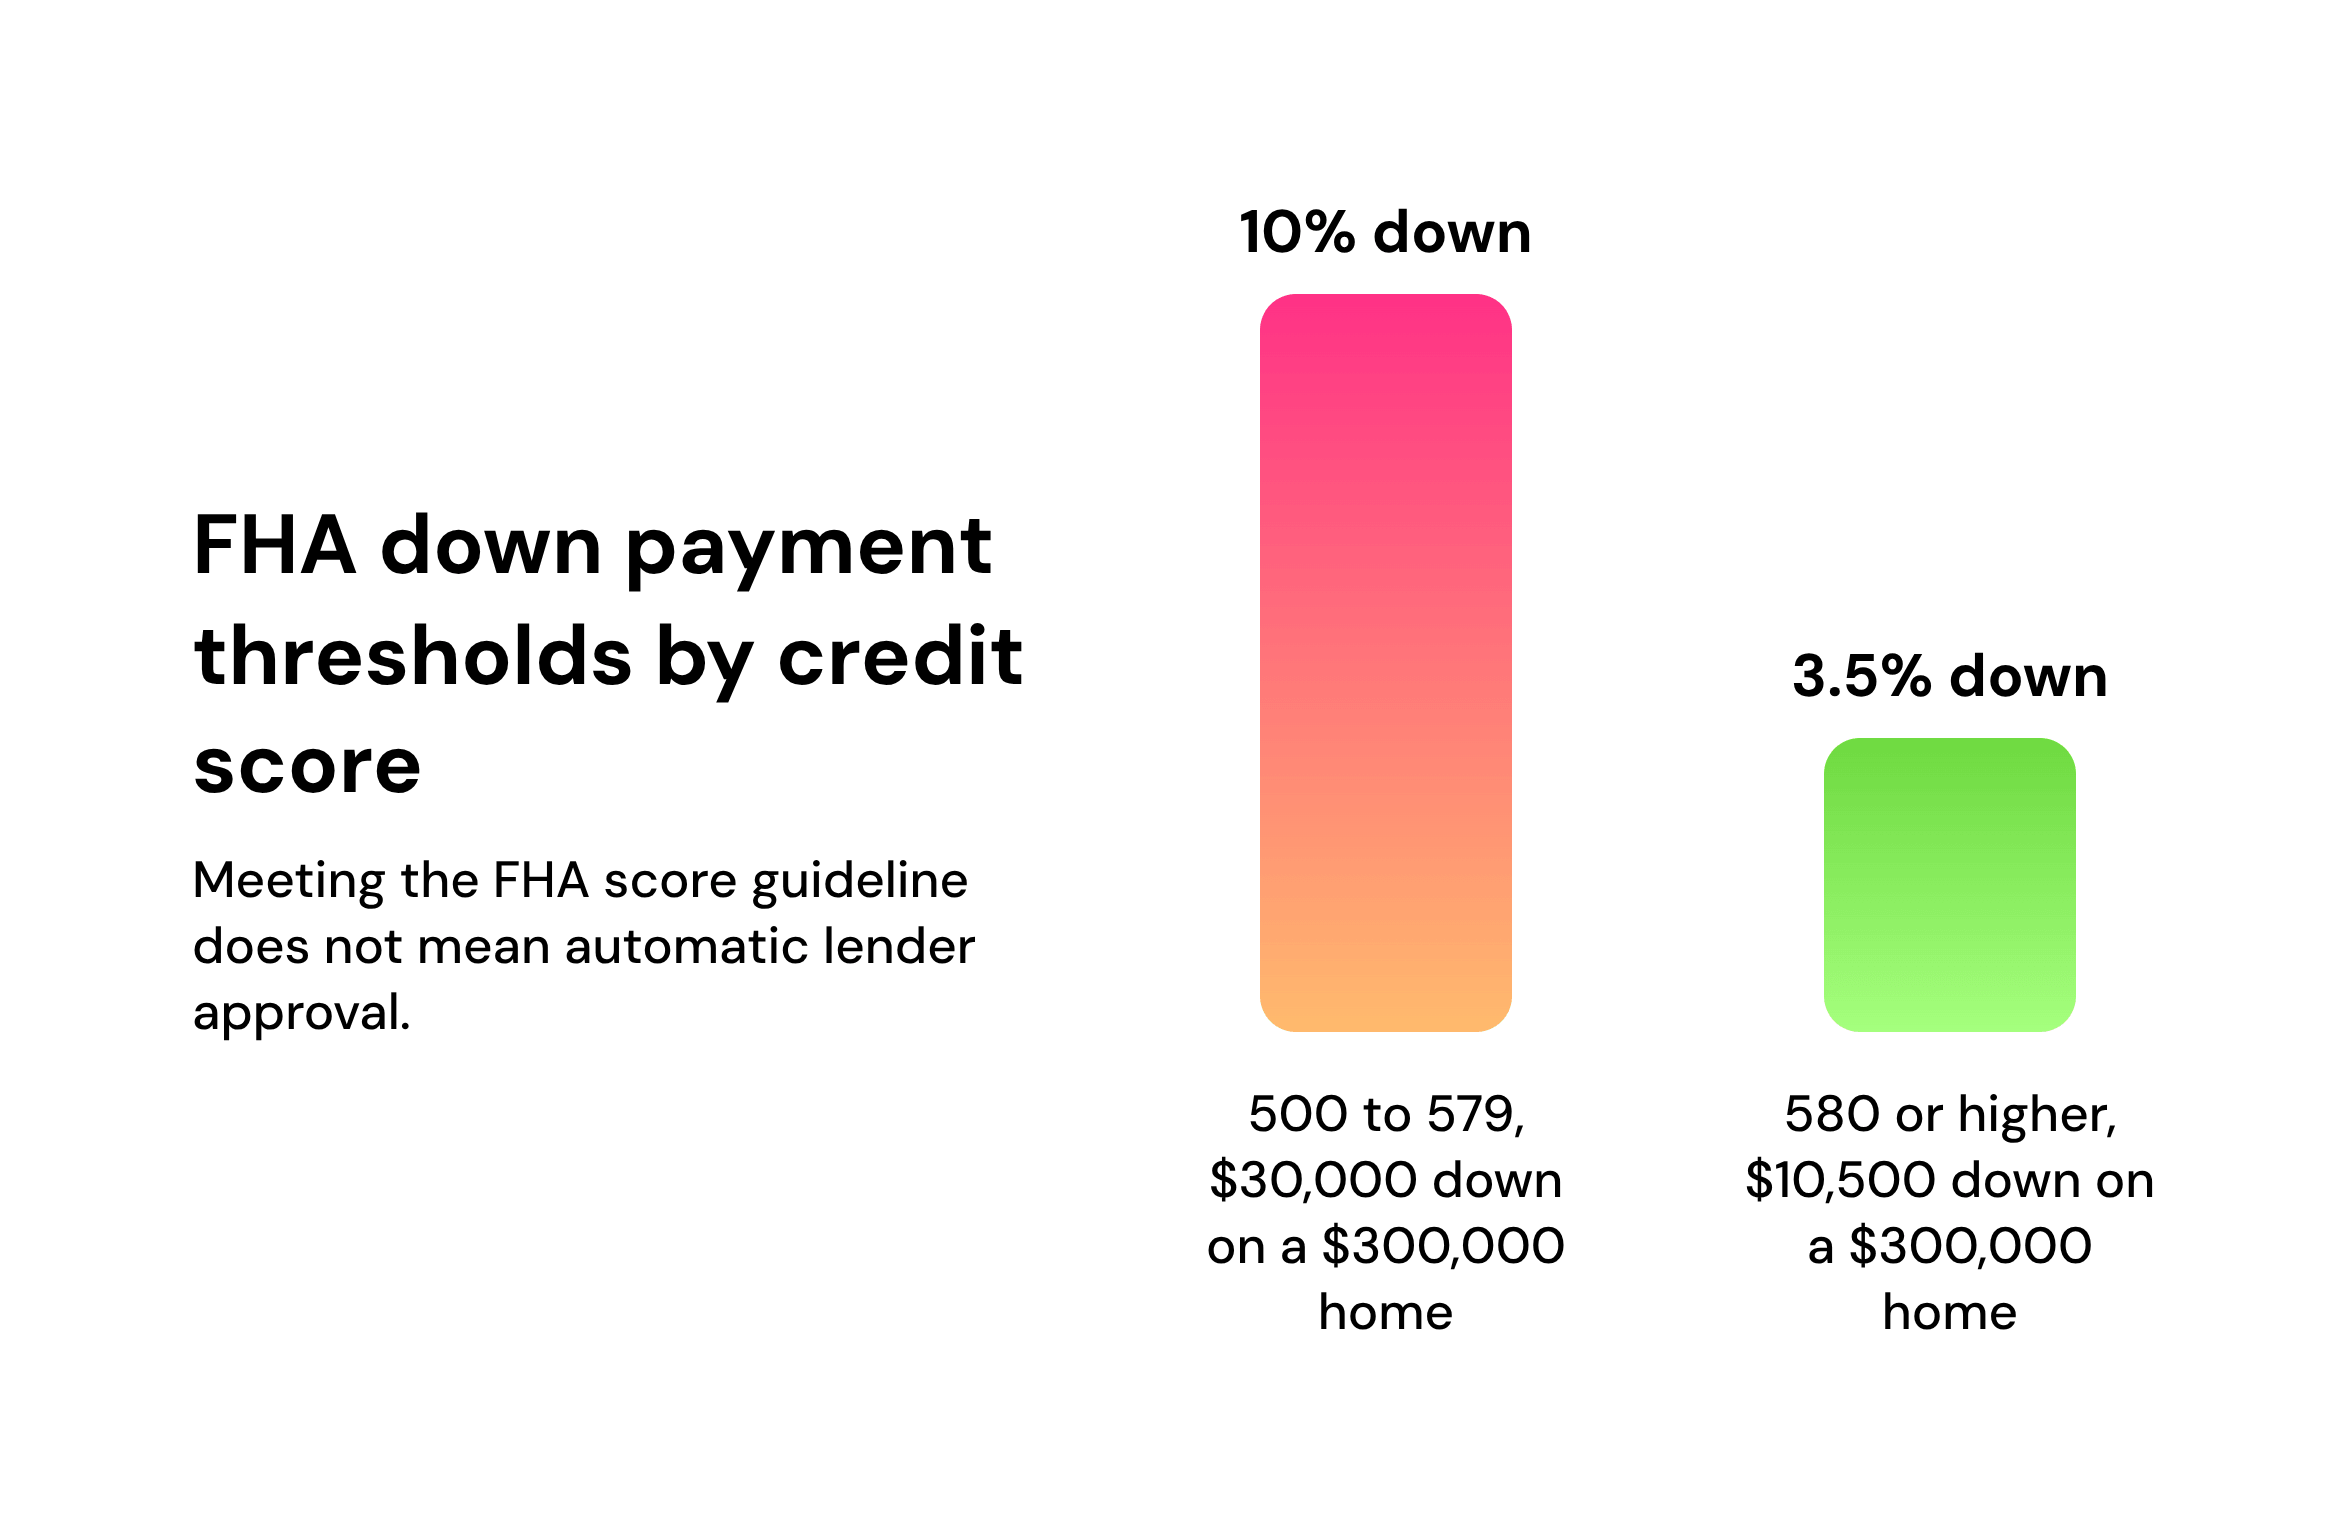
On a $300,000 home, a 10% down payment is $30,000. You would also need money for closing costs and other upfront expenses.
Scores of 580 or higher
A borrower with a minimum decision credit score of at least 580 may be eligible for FHA's maximum purchase financing, which is generally 96.5% of the adjusted property value. That corresponds to a down payment as low as 3.5%.
On the same $300,000 home, a 3.5% down payment is $10,500. That is $19,500 less than a 10% down payment, before closing costs and other expenses.
The score used by a mortgage lender may not match the score shown in a free app. Mortgage lenders commonly review scores and reports from all three nationwide credit bureaus, and your credit score is only one part of the decision, according to the Consumer Financial Protection Bureau.
Why approval can still be difficult with a 500 score
FHA program rules set the broad eligibility boundaries. Individual lenders may use additional underwriting standards to manage risk, including a higher minimum credit score.
Even when a lender accepts applications with scores in the 500s, it will consider more than your score. Important factors may include:
- Your income and employment history
- Your monthly debt payments relative to your income
- Your savings and other assets
- Recent late payments, collections, or other credit problems
- The amount of your down payment
- Whether the property meets FHA requirements
A stronger factor in one area may not offset a weakness somewhere else. Ask a lender what requirements apply before authorizing a full application.
What an FHA loan with a 500 score may cost
The down payment is only one part of the cash and long-term cost you need to consider.
Down payment
With a score from 500 through 579, FHA rules generally limit you to 90% LTV, so you should plan for at least 10% down. Down payment assistance may be available through state or local programs, but eligibility and permitted funding sources vary.
FHA mortgage insurance
FHA loans use mortgage insurance premiums, or MIP, rather than the private mortgage insurance commonly associated with conventional loans. In most FHA programs, HUD collects an upfront MIP and an annual MIP that is usually divided among your monthly payments.
For many FHA purchase loans, the upfront MIP is 1.75% of the base loan amount. For FHA cases assigned on or after June 3, 2013, annual MIP generally lasts 11 years when the original LTV is 90% or less and for the mortgage term when the original LTV is above 90%. Exceptions can apply.
Interest rate and closing costs
Your credit can affect both approval and the interest rate you are offered. A lower score may result in a higher rate, but pricing varies by lender and loan details. Comparing Loan Estimates from multiple lenders can help you evaluate the rate, monthly payment, lender fees, and total closing costs together.
Closing costs may include appraisal, title, government, prepaid tax, insurance, and interest charges. The CFPB explains that lender or seller credits may reduce what you pay at closing, but those credits can come with tradeoffs such as a higher loan amount, home price, or interest rate.
How to find a lender that accepts lower scores
Start with HUD's FHA-approved lender search instead of relying on advertisements that only mention FHA loans. Ask each lender:
- What is your minimum credit score for an FHA purchase loan?
- Do you accept applications with scores from 500 through 579?
- What down payment and cash-reserve requirements would apply?
- What recent late payments or collections could affect approval?
- Can you provide a written Loan Estimate if I apply?
Compare more than the advertised rate. Fees, mortgage insurance, discount points, and loan terms all affect the total cost.
If you want help assessing your options before applying, a HUD-approved housing counselor can offer guidance based on your situation. You can also call HUD at 800-569-4287 to find a counseling agency.
What to do if your score is 500 and you want to buy soon
There is no shortcut, but these steps can make your financial profile stronger over time:
- Check all three credit reports. Look for accounts, balances, or late payments that do not belong to you.
- Dispute inaccurate information. Correcting a legitimate reporting error can help ensure lenders assess accurate information. A dispute cannot remove accurate negative information simply because it hurts your credit.
- Pay every bill on time. Payment history reflects how consistently you have handled credit obligations.
- Reduce revolving balances. Lower credit card balances can reduce your credit utilization, which compares the balances you owe with your available revolving credit.
- Avoid unnecessary credit applications. Opening several accounts shortly before a mortgage application can add inquiries and new debt.
- Keep saving. In addition to the down payment, plan for closing costs, moving expenses, and an emergency cushion.
The CFPB recommends paying bills on time, staying well below credit limits, and checking credit reports for errors. Give yourself time to establish consistent habits before rechecking your mortgage options.
Read more >> How Long Does It Take to Build Credit?
Bottom line
FHA rules may allow a mortgage with a 500 credit score, but approval at that level can be difficult. Borrowers with scores from 500 through 579 generally need at least 10% down, and lenders may set higher standards or consider other parts of the application too.
If you are not ready to qualify, focus on accurate credit reports, on-time payments, lower revolving balances, and additional savings. When you are ready to compare options, speak with FHA-approved lenders and consider guidance from a HUD-approved housing counselor.
Take a step toward stronger credit habits with Kikoff.
Frequently Asked Questions
Disclaimer: The information provided in this blog post is meant for informational purposes only and does not constitute financial advice.