

You do not start with a credit score of zero, 300, or any other preset number. If your credit reports do not contain enough information for a scoring model to evaluate you, you are considered unscoreable under that model. Once enough information has been reported, your first score is calculated from the contents of your credit report.
The timing depends on the scoring model. A FICO Score generally requires at least one account that has been open for six months or longer. VantageScore 4.0 can score some consumers with a much shorter history.
What credit score do you start with?
There is no universal starting credit score. Turning 18 does not automatically create one, and opening your first account does not assign you a standard number.
FICO and current VantageScore models commonly use a range of 300 to 850, but 300 is the bottom of the range, not everyone’s starting point. Your first score could fall anywhere within the applicable model’s range based on the information available when the score is calculated.
Having no credit score is not the same as having a low credit score. No score generally means the model does not have enough eligible information to calculate one.
The three nationwide credit bureaus, Equifax, Experian, and TransUnion, maintain credit reports. Companies such as FICO and VantageScore apply scoring models to information in those reports. Because the bureaus may receive different information and lenders may use different scoring models or versions, you can have multiple credit scores rather than one permanent score.
Why your credit score does not start at zero
Credit scores measure the risk associated with information in a credit report. Without enough report data, a scoring model cannot make that assessment.
Activities that usually do not appear on traditional credit reports, such as using a debit card or paying cash, generally do not create a credit score. Rent, utility, and cellphone payments may contribute to some scores when they are reported and the scoring model considers them, but they do not automatically appear on every credit report.
Read more >> How to Buy a Car With No Credit History
How your first credit score is generated
The process begins when an account or other eligible information is added to one or more of your credit reports. Depending on the account, a lender or service provider may report details such as:
- Whether you paid on time
- The account’s age and status
- The balance and credit limit
- The type of account
- Recent applications that created hard inquiries
Not every creditor reports to all three bureaus. That means one report could become scoreable before another, or scores based on different reports could vary.
FICO minimum scoring requirements
According to FICO’s minimum requirements, a credit report generally needs:
- At least one account opened for six months or more
- At least one account reported to the bureau within the past six months
- No indication that the consumer is deceased
One account can satisfy both account requirements, or separate accounts can satisfy them. Meeting these conditions makes a report eligible for a FICO Score, but it does not determine what that score will be.
VantageScore may generate a score sooner
VantageScore uses different scoring requirements. VantageScore says it may generate a score after as little as one month of reported credit activity.
This is why an app may show you a VantageScore before you have enough history for a FICO Score. It does not mean either score is incorrect. They come from different models, and a lender may use a different score from the one you see in a consumer app.
How long does it take to get your first credit score?
If you are building a credit file from scratch with a newly opened account, expect a FICO Score to take about six months, assuming the account is reported and meets FICO’s other requirements. Reporting does not always begin on the day you open the account, so the score may not appear at exactly the six-month mark.
A VantageScore may become available sooner, potentially after one month of reported activity. The exact timing still depends on when information reaches the bureau and whether the model has enough usable data.
You do not need to carry a balance or pay interest while waiting. If you use a credit card, paying the statement balance in full by the due date can help you avoid interest while building payment history.
What affects your first credit score?
Your first score is based on the same types of report information used in later scores. For FICO Scores, the general categories are:
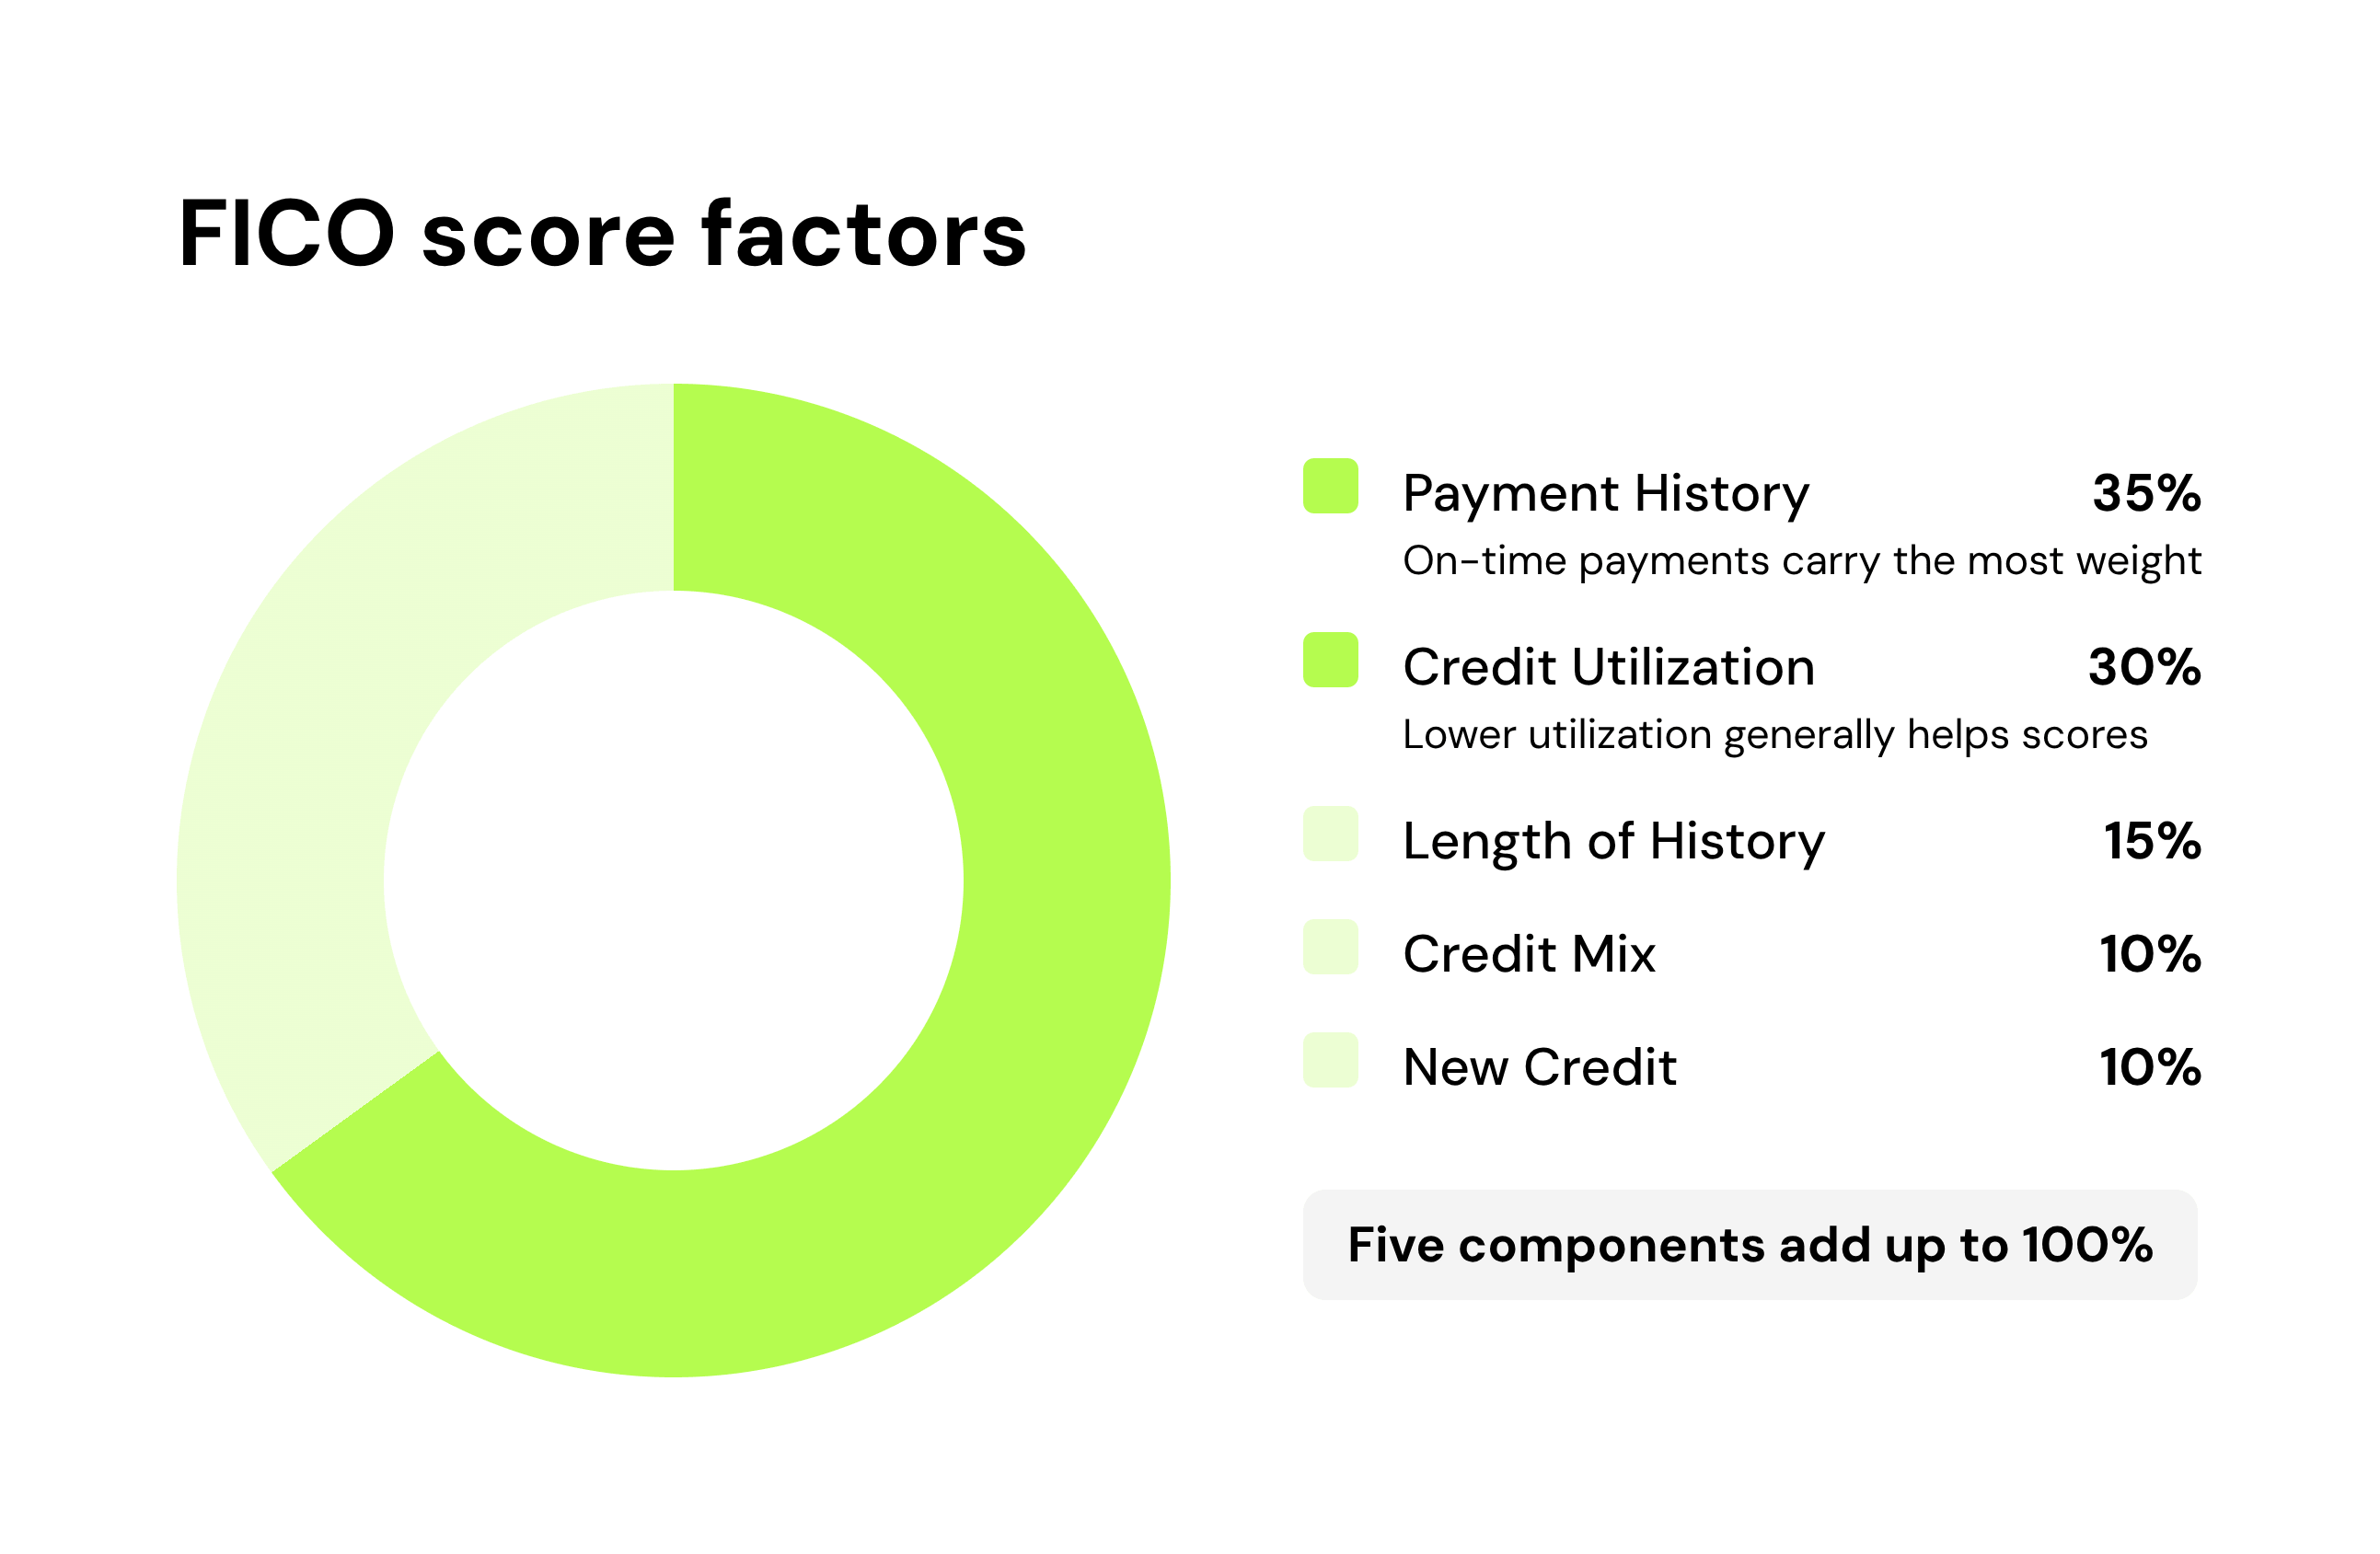
- Payment history: Whether reported payments were made on time
- Amounts owed: Balances, including credit card utilization
- Length of credit history: The ages of your accounts
- New credit: Recently opened accounts and hard inquiries
- Credit mix: The types of credit represented in your file
FICO explains that these categories do not affect every person in exactly the same way. A thin credit file has less information, so each reported account can carry more weight.
You do not need to open several types of accounts just to create a credit mix. Taking on unnecessary debt or submitting several applications can cost more than any potential scoring benefit.
How to start building credit responsibly
Focus on a small number of manageable habits rather than trying to reach a particular score immediately:
- Pay every account by its due date
- Keep credit card balances low relative to their limits
- Avoid opening accounts you do not need
- Review account statements and credit reports for errors
- Keep older accounts open when they remain useful and affordable
- Consider becoming an authorized user on a well-managed card if the issuer reports authorized-user activity
An authorized user is not the same as a joint account holder. The primary cardholder is generally responsible for the bill, but their activity could affect the authorized user’s credit if the account is reported.
You can request your reports from all three bureaus through AnnualCreditReport.com. A credit report does not necessarily include a free credit score, but reviewing it helps you confirm which accounts are being reported and whether the information is accurate.
Read more >> Does Checking Your Credit Score Lower It?
Bottom line
You do not begin at zero or receive a standard starting score. You begin without a score under a particular model until your credit report contains enough eligible information. Your first score then reflects the accounts and activity appearing in that report.
For a new credit file, a FICO Score generally takes about six months to become available, while a VantageScore may appear sooner. Pay on time, keep balances manageable, and avoid opening unnecessary accounts while your history develops.
If you want another way to establish reported payment history, Kikoff offers credit-building plans that report your balance and repayments to Equifax, Experian, and TransUnion. You can sign up without a credit check.
Frequently Asked Questions
Disclaimer: The information provided in this blog post is meant for informational purposes only and does not constitute financial advice.