

Yes. Student loans can affect your credit because they appear on your credit reports as installment accounts. Paying as agreed can contribute positive payment history, while reported late payments and default can cause serious credit damage.
Your loan balance, account age, and credit mix may also influence your scores. The effect is not identical for everyone because scoring models consider the rest of your credit profile, too.
How do student loans affect your credit score?
Student loans appear as installment accounts
An installment loan provides a set amount that you repay through scheduled payments. Student loans, auto loans, personal loans, and mortgages are common examples.
Your credit reports may show the lender or servicer, original balance, current balance, payment history, and account status. Federal student loan servicers generally report account information to the major credit bureaus each month.
Payment history can help or hurt
Payment history is generally the most influential category in a FICO Score. Making required payments on time can add positive information to your credit history. Missing payments can have the opposite effect once the delinquency is reported.
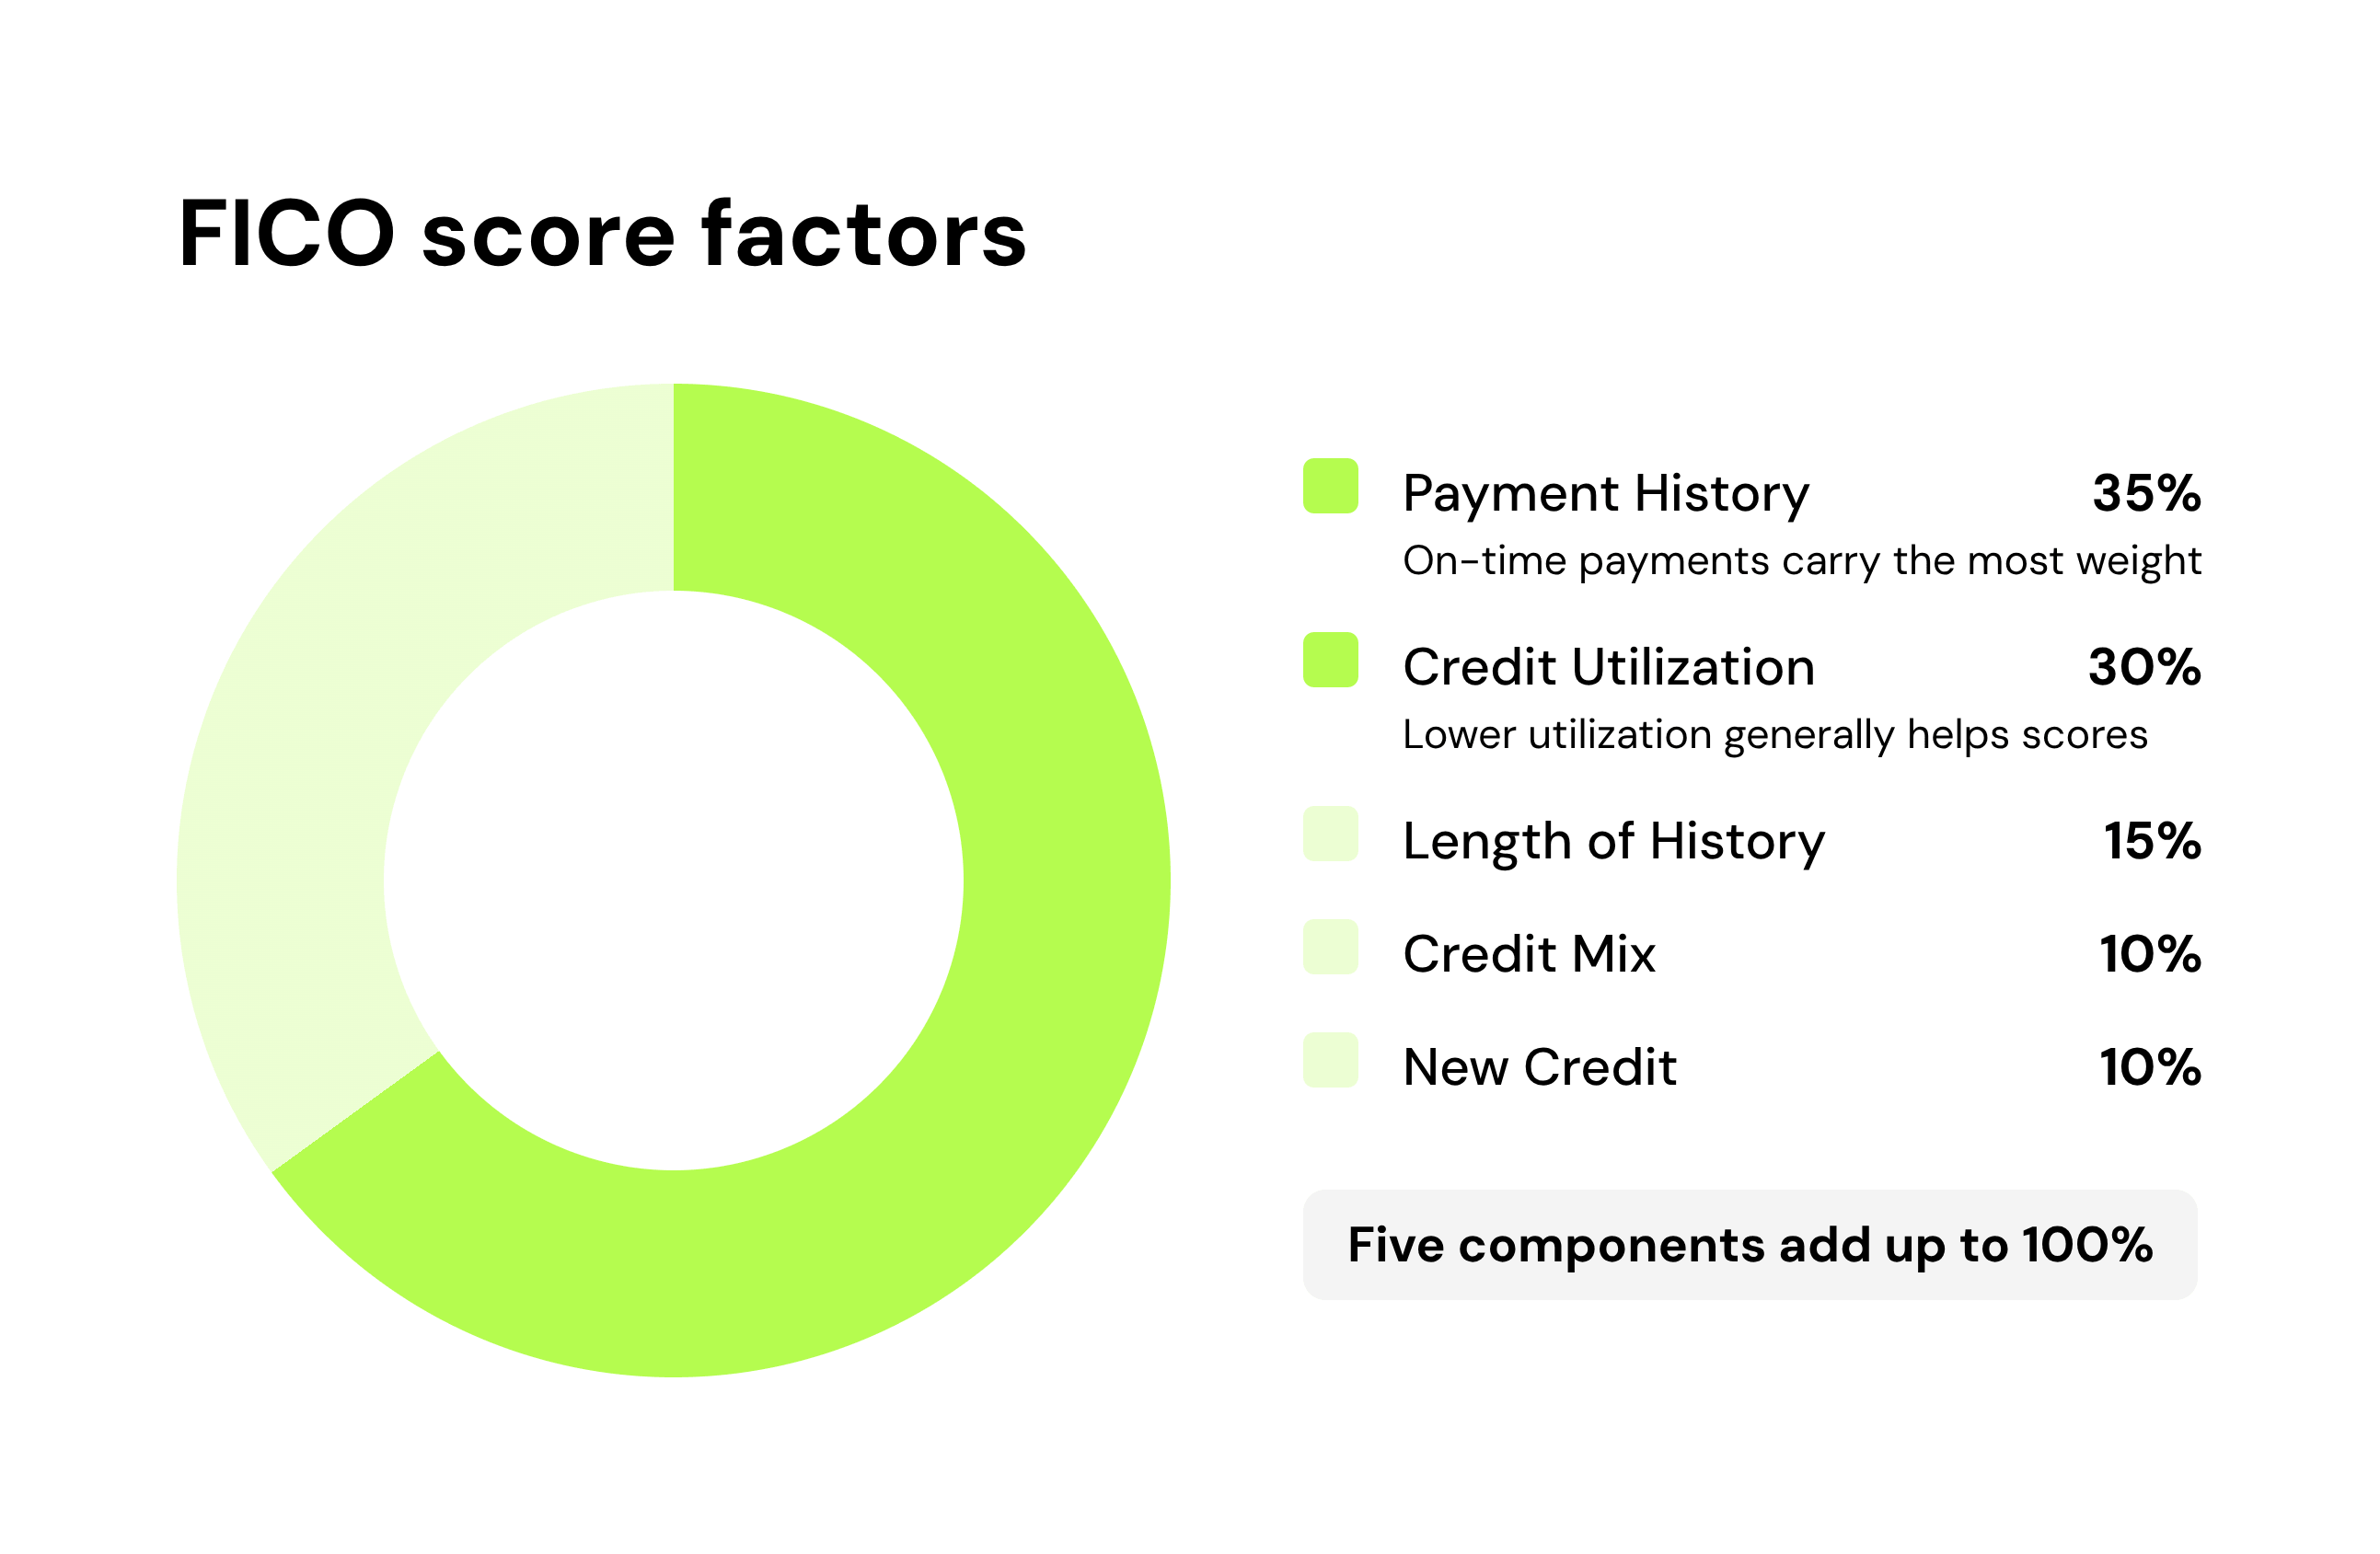
According to FICO, the five broad FICO Score categories are:
- Payment history: 35%
- Amounts owed: 30%
- Length of credit history: 15%
- New credit: 10%
- Credit mix: 10%
These percentages describe the general weighting for the overall population. The importance of an individual factor can vary based on the information in your credit file, and other scoring models may work differently.
Your balance contributes to amounts owed, not revolving utilization
Student loans can affect the amounts-owed category, but they do not create a revolving credit-utilization ratio like a credit card does. Scoring models can consider how much remains on an installment loan compared with its original amount.
A large balance does not automatically mean you will have a poor score. Your payment history and the rest of your credit profile still matter.
Student loans may add account age and credit mix
Keeping an installment account in good standing over time may contribute to the length and variety of your credit history. However, credit mix is only one part of a score.
Do not take out or keep a student loan solely to influence your credit mix. The interest and repayment obligation matter more than a possible scoring benefit.
How can student loans hurt your credit?
Missing federal student loan payments
A federal student loan becomes delinquent the first day after you miss a required payment. According to Federal Student Aid, the servicer reports the delinquency to the three major credit bureaus when it reaches 90 days.
Private student loan reporting policies can differ. Review your loan agreement and contact the lender or servicer before the due date if you cannot make a payment.
There is no universal number of points that every missed payment will cost. The effect depends on the scoring model, how late the payment becomes, and the rest of your credit history. Negative payment-history information can generally remain on a credit report for up to seven years, according to the Consumer Financial Protection Bureau.
Going into default
Most federal student loans enter default after at least 270 days without a scheduled payment. Default can damage your credit, make the full balance immediately due, and cause you to lose access to deferment, forbearance, and federal repayment plans until the default is resolved.
The government may also use collection tools such as Treasury offset or administrative wage garnishment after providing the required notices. Federal Student Aid explains the consequences and resolution options in its student loan default guidance.
Private student loans may enter default sooner, depending on the contract. Collection rights and procedures depend on the loan agreement and applicable law.
If you are struggling, contact your servicer before missing a payment. Waiting until the account is delinquent limits your options and may leave accurate negative reporting in place even after you arrange relief.
Letting interest increase the balance
Interest can continue to accrue during school, deferment, forbearance, or repayment, depending on the loan type and status. Unpaid interest may capitalize in certain situations, which means it is added to the principal balance.
A growing balance is not the same as a reported late payment, but it increases the amount you owe and may make future payments harder to manage.
Does deferment or forbearance hurt your credit?
An approved deferment or forbearance should not be reported as a missed payment. However, any late payments reported before the relief became effective may remain on your credit reports.
Interest treatment also differs. The government may pay interest on certain subsidized loans during eligible deferment periods, while interest generally accrues on unsubsidized and PLUS loans. During forbearance, interest generally accrues on all federal student loan types.
Submitting a request does not necessarily pause your current obligation. Keep making required payments until your servicer confirms that the deferment or forbearance is active, unless the servicer gives you different instructions.
Read more >> Does Deferring Student Loans Hurt Your Credit?
Does applying for a student loan affect your credit?
It depends on the type of loan.
- Direct Subsidized and Direct Unsubsidized Loans: These federal loans generally do not require a credit check.
- Direct PLUS Loans: The Department of Education checks for adverse credit history. The inquiry may appear on your credit reports.
- Private student loans: Private lenders generally review credit and may perform a hard inquiry when you submit a full application.
If you are comparing private loans, ask whether you can check potential terms through a soft-inquiry prequalification before completing a full application.
A co-signer can also affect approval and pricing for a private loan. The co-signer becomes legally responsible for the debt, and missed payments can affect both people’s credit.
What happens to your credit when you pay off a student loan?
Paying off a student loan closes the account with a paid status. You might see a temporary score change because the account is no longer active or because your account mix changed, but the result varies by credit profile.
Positive payment history may remain on your reports after the loan is closed. More importantly, paying off the loan eliminates the required payment and prevents additional interest from accruing.
Do not keep paying interest solely to keep an installment account open for credit-scoring purposes.
How to protect your credit while repaying student loans
Confirm your loan details
Log in to StudentAid.gov for federal loans or your private lender’s portal. Verify the balance, servicer, payment amount, due date, and repayment status. Keep your contact information current so you receive billing and account notices.
Use reminders or automatic payments carefully
Payment reminders or automatic payments can reduce the risk of an accidental missed payment. If you use automatic payments, check the account before each withdrawal and after any servicer transfer or repayment-plan change.
Compare current federal repayment plans
Federal repayment-plan eligibility now depends partly on loan type and disbursement date.
For eligible federal student loans disbursed on or after July 1, 2026, the Repayment Assistance Plan is the only income-driven repayment option currently available. Parent PLUS loans and consolidation loans that repaid Parent PLUS debt are not eligible for RAP. Borrowers with older loans may have additional choices.
Use the Federal Student Aid Repayment Calculator to compare estimated payments and total costs. If your income or family size changes, contact your servicer before missing a payment.
Review your credit reports
You can request free weekly reports from Equifax, Experian, and TransUnion at AnnualCreditReport.com. Check that balances, payment histories, and account statuses are accurate.
If you find an error, dispute it with the credit bureau displaying it and the company that supplied the information. Accurate negative information generally cannot be removed simply because it is harmful.
Address default directly
If your federal student loans are already in default, review the current options through Federal Student Aid’s Default Resolution Group. Depending on your loans and history, the available paths may include rehabilitation, consolidation, or repayment in full.
Bottom line
Student loans affect your credit through payment history, amounts owed, account age, and credit mix. Paying as agreed can add positive history, while a federal delinquency reported after 90 days or a later default can cause substantial harm.
If you cannot afford the payment, contact your servicer before the due date and compare current repayment or temporary-relief options. Do not wait for the account to become delinquent.
If you want to add positive payment history beyond your student loans, Kikoff’s free Credit Account reports your on-time payments to all three major credit bureaus, with no hard credit check to sign up. It can help you build credit, but it does not change your student loan balance, repayment plan, or eligibility for federal relief.
Frequently Asked Questions
Article Sources
Disclaimer: The information provided in this blog post is meant for informational purposes only and does not constitute financial advice.