Payday loans can provide money quickly, but their high fees and short repayment windows may turn one cash shortage into another. If you need money before your next paycheck, start with options that do not create new debt. Then compare lower-cost borrowing choices by total cost, repayment timing, and risk.
The best alternative depends on what the money is for, how quickly you need it, and whether your next paycheck can cover repayment without leaving you short again.
Best alternatives to payday loans
Try payment arrangements and assistance programs before borrowing. If you still need a loan or advance, compare several options rather than choosing the first one that promises fast cash.
Read more >> Need Money but Cannot Get a Loan? Here Are Some Alternatives
Ask for more time or a payment plan
Contact your landlord, utility company, medical provider, lender, or other biller before the due date. Explain how much you can pay now and when you expect to pay the rest.
Depending on the provider and your account, you may be able to:
- Move the due date
- Split the amount into smaller payments
- Enter a short-term hardship plan
- Pause or reduce a payment temporarily
- Have a late fee waived
Ask how the arrangement affects interest, fees, service, and credit reporting. Get the terms in writing and do not agree to a payment you are unlikely to make.
Check for a credit union payday alternative loan
Some federal credit unions offer payday alternative loans, or PALs. These small-dollar loans have federal limits on loan size, term, fees, and repeat borrowing.
The National Credit Union Administration says PALs II loans may be as large as $2,000, with terms from one to 12 months. They must be fully amortized, meaning the scheduled payments reduce the balance to zero, and rollovers are prohibited.
You must qualify for credit union membership and loan approval, and not every credit union offers PALs. Ask about the APR, application fee, payment amount, and total repayment cost.
Ask whether your employer offers early wage access
Your employer may let you receive part of your earned wages before payday, either directly or through an earned-wage access service. This may cost less than a payday loan, especially if a free standard-transfer option is available.
It is not automatically free. Expedited-transfer fees, subscriptions, or other charges may apply, and accessing wages early means your regular payday deposit will be smaller. Confirm the full cost and repayment method before using it.
Compare a small personal loan
A bank, credit union, or reputable online lender may offer a small installment loan with more time to repay. Approval and pricing depend on the lender and your financial profile.
Compare the APR, origination fee, monthly payment, late fees, and total repayment amount. If a lender offers prequalification, confirm whether checking your estimated terms requires a soft or hard credit inquiry.
Avoid focusing only on the monthly payment. A longer term can make each payment smaller while increasing the total interest paid.
Apply for community assistance
Assistance may solve the immediate problem without adding another payment to your budget. Depending on your needs and eligibility, you may find help through:
- State and local rental-assistance programs
- LIHEAP and other energy-assistance resources
- SNAP and other food-assistance programs
- Community action agencies, food banks, housing nonprofits, and faith-based organizations
You can also call 211 to look for services in your area. Availability, eligibility, and processing times vary, so apply as early as possible.
Borrow from family or friends with clear terms
If someone you trust can help, agree on the amount, repayment dates, and what happens if you need more time. Put the agreement in writing even when the arrangement is informal.
Do not promise repayment from money already needed for next month’s rent, food, utilities, or transportation. A realistic plan protects both your budget and the relationship.
Evaluate cash advance apps carefully
Some cash advance apps offer a free standard transfer, but others charge subscription fees, expedited-transfer fees, optional tips, or other costs. Direct-to-consumer apps may also debit repayment from your bank account, which can contribute to overdraft or nonsufficient-funds fees if the money is not available.
Before accepting an advance, add up every cost, check when repayment will be taken, and calculate what will remain from your next paycheck. Avoid treating advances as part of your regular monthly income.
Talk with a nonprofit credit counselor
If you are repeatedly short or managing several debts, a nonprofit credit counselor can help you review your budget and repayment options. The National Foundation for Credit Counseling can connect you with nonprofit counseling organizations.
Ask about fees and services before enrolling. A counselor cannot erase legitimate debt or promise that a creditor will accept a proposal.
What makes payday loans risky?
A payday loan is generally a small, short-term loan due in one payment on or near your next payday. The speed may be appealing, but the cost and repayment structure can put additional pressure on an already tight budget.
Read more >> How to Pay Bills With No Money
A small fee can represent a very high APR
Payday lenders generally charge a dollar amount for every $100 borrowed. According to the Consumer Financial Protection Bureau, fees may range from $10 to $30 per $100, depending on state law. A common $15 fee per $100 equals an APR of nearly 400% for a two-week loan.
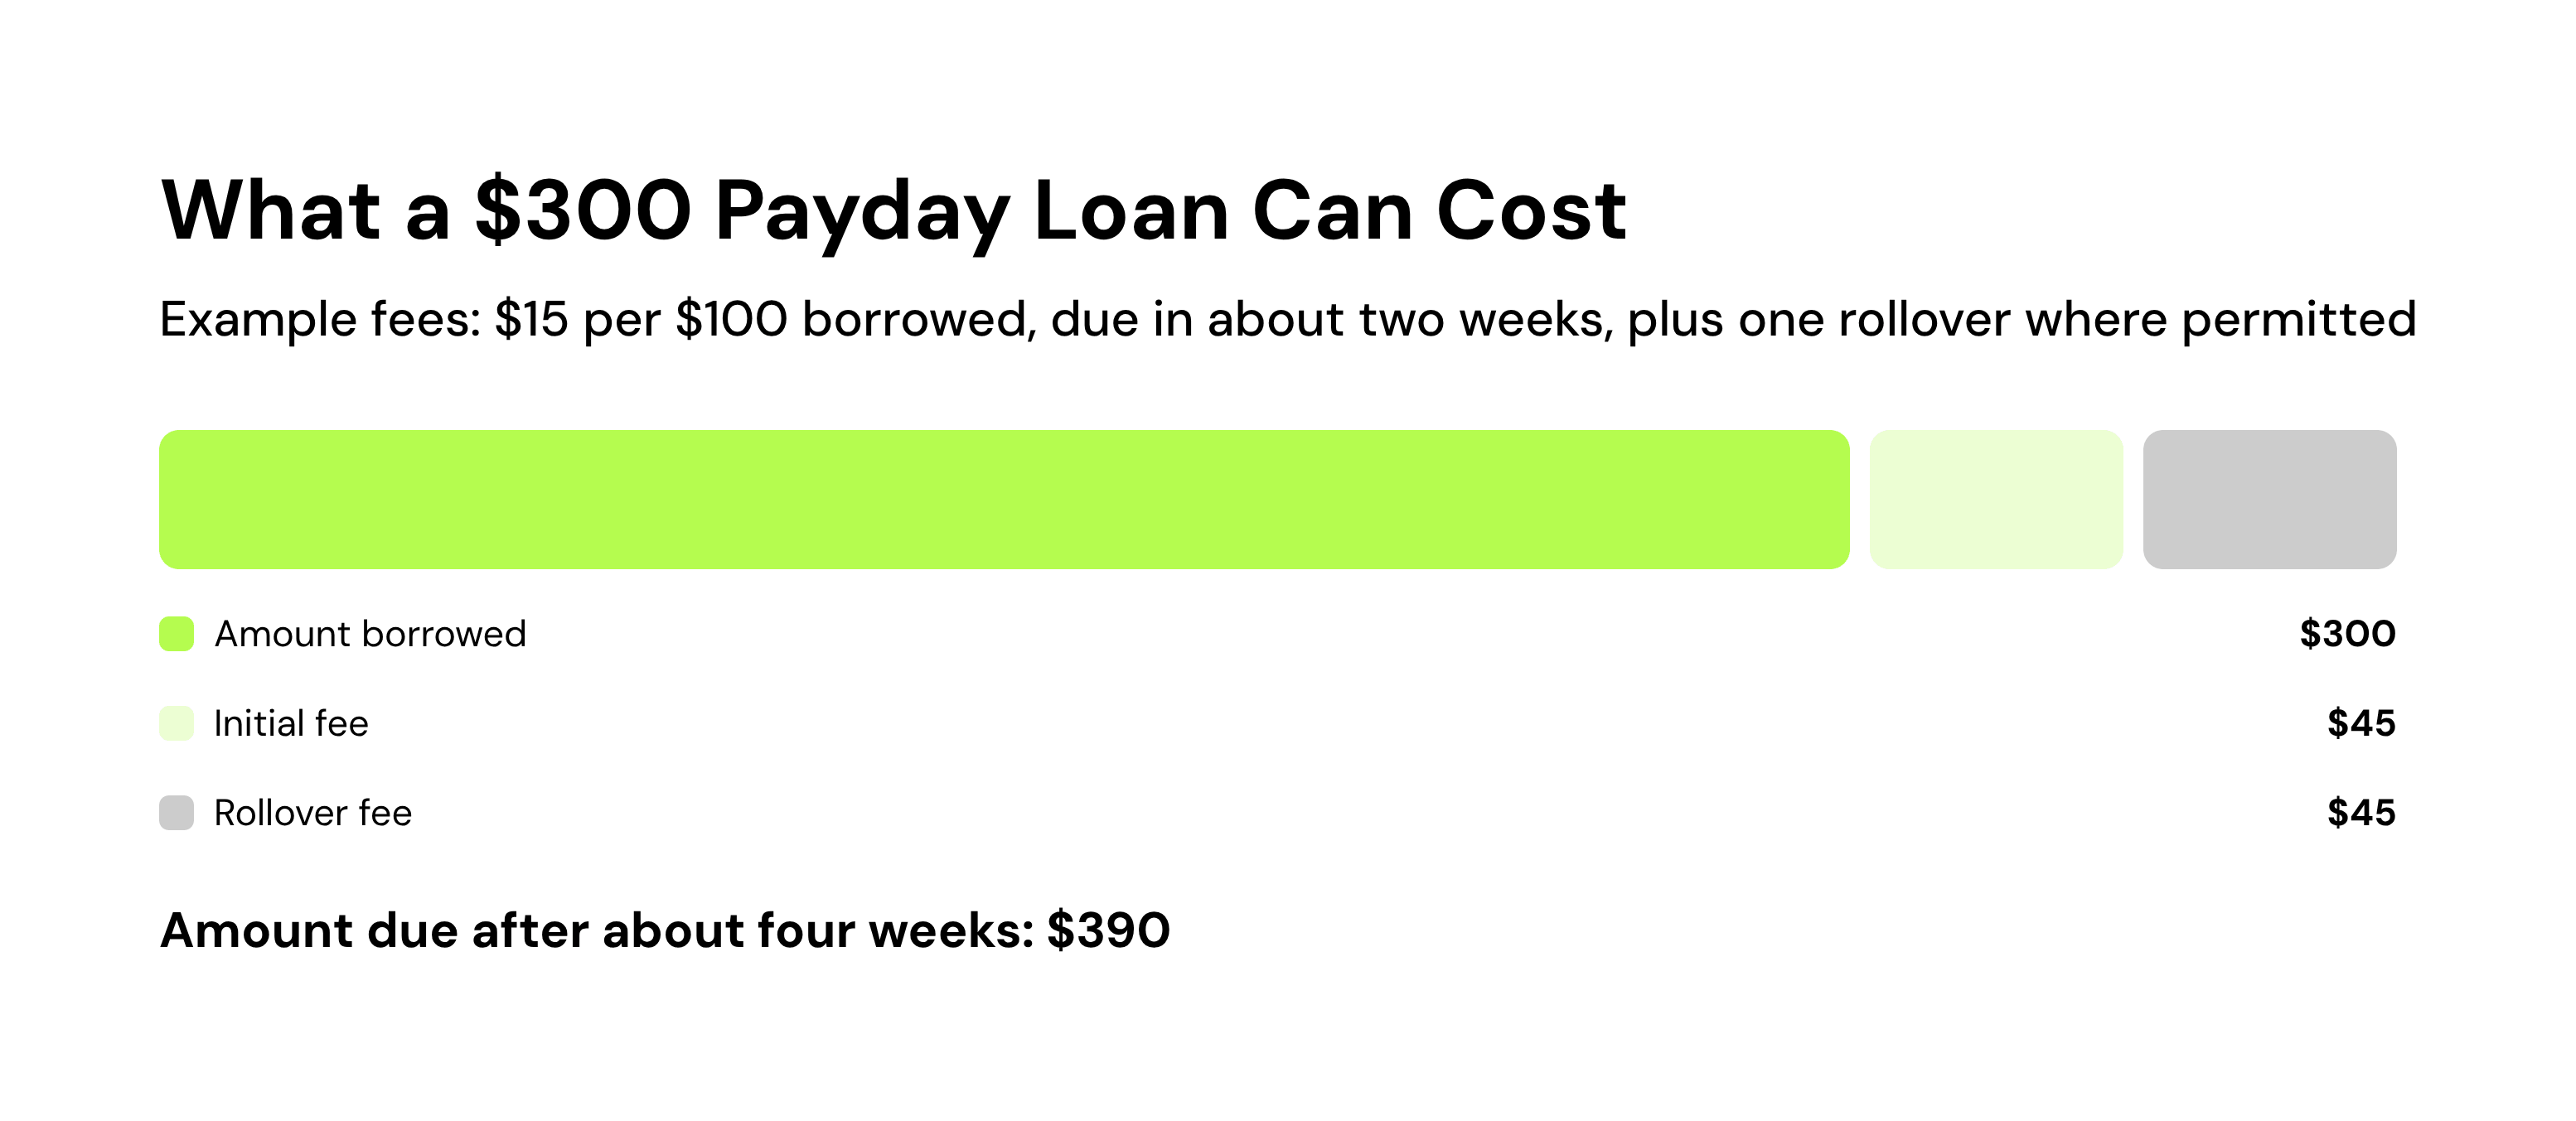
For example, a $300 loan with a $15 fee per $100 would require a $345 payment in about two weeks.
Repayment can create another cash shortage
Payday loans are commonly repaid in one lump sum. If your next paycheck must cover the loan, its fee, and all your regular expenses, you may be forced to delay another bill or borrow again.
A loan is not affordable merely because you can receive it today. Check whether you can repay the full amount and still cover your next round of essential expenses.
Rollovers can add fees without reducing the balance
If state law permits rollovers and the lender offers one, you may be able to pay another fee to extend the due date. You still owe the original balance.
In the $300 example, a $45 rollover fee would bring total fees to $90 after about four weeks while leaving the original $300 principal due. Some states prohibit or restrict payday lending and rollovers.
Automatic repayment can trigger additional costs
Payday lenders may require a postdated check or authorization to debit your account. If the money is not available when repayment is attempted, the lender, your financial institution, or both may charge returned-payment or nonsufficient-funds fees, depending on the agreement and applicable law.
How to choose the right payday-loan alternative
The lowest-cost option that arrives in time and fits your budget is generally better than the fastest option with an unaffordable repayment date.
Compare these factors:
- Total amount received
- APR and every required or optional fee
- Payment amount and repayment schedule
- Whether repayment is automatic
- Consequences of a missed payment
- Whether an application requires a hard credit inquiry
- Whether payment activity is reported to credit bureaus
- Lender or provider licensing and complaint history
Check whether the lender is licensed where required by contacting your state regulator or attorney general. Be cautious if a lender promises approval, demands an upfront payment before providing a loan, or pressures you to act without reviewing the agreement.
Read more >> How to Get a Personal Loan With Bad Credit
What to do if you already have a payday loan
If you cannot repay the loan on time, contact the lender before the due date. Ask whether an extended payment plan is available, what it costs, and how it changes the payment schedule. State requirements vary.
Avoid taking out another payday loan solely to repay the first one if possible. Contact other billers about temporary arrangements, apply for local assistance, and consider speaking with a nonprofit credit counselor.
If you believe a lender charged unauthorized fees, made unauthorized withdrawals, or violated your agreement, contact your state regulator or attorney general. You can also submit a complaint to the CFPB.
Bottom line
The best payday-loan alternative is one that addresses the emergency without creating an unaffordable payment on your next payday. Start with payment arrangements, community assistance, and help from people you trust. If borrowing is necessary, compare credit union PALs, small personal loans, employer-based wage access, and carefully evaluated advance apps.
Building credit will not solve an emergency today, but it may give you more borrowing options over time. Kikoff’s free Credit Account reports on-time payments to Equifax, Experian, and TransUnion with no hard credit check to sign up. Get started when the payment fits comfortably in your budget.
Frequently Asked Questions
Disclaimer: The information provided in this blog post is meant for informational purposes only and does not constitute financial advice.