

Credit cards are effectively the most influential financial tool most people carry in their wallet.
They shape your credit score more than almost any other product, driving two of the five major scoring factors simultaneously. But to understand why credit cards are so powerful, it helps to understand where they came from and how the system around them was built.
The evolution and impact of credit cards on credit scores
Credit cards didn't start as a credit-building tool. They started as a convenience product, and the credit scoring infrastructure we know today was built around them over several decades.
Every individual who uses a credit card today is participating in a system that took nearly a century to develop. Understanding that history paints a picture of why the rules work the way they do.
The origins of credit: before the plastic card
The concept of "buy now, pay later" is far older than the credit card itself.
In the early 1900s, department stores and oil companies issued paper "charge plates" to trusted customers, allowing them to make purchases and settle the balance at the end of the month. These weren't credit in the modern sense, they were basically loyalty tools extended to customers the merchant already knew personally.
The first true general-purpose charge card arrived in 1950 when Diners Club launched a cardboard card that could be used at multiple restaurants in New York City. This shift was meaningful because the card worked across businesses that had no prior relationship with the cardholder.

American Express entered the market in 1958 with a charge card of its own, followed shortly by BankAmericard, which would eventually become Visa. Unlike charge cards, which required full payment each month, BankAmericard introduced the "revolving credit" model, allowing users to carry a balance and pay interest on it over time.
This revolving structure is what laid the foundation for how credit utilization works in scoring models today.
The rise of credit bureaus and standardized reporting
As credit cards spread, lenders faced a serious problem: they had no reliable way to evaluate the millions of new applicants they were receiving.
Local merchants had always relied on personal reputation and community knowledge to extend credit. That model couldn't scale to a national card network. The solution was the credit bureau, an independent organization that would collect and centralize payment data across lenders.
Equifax was founded in 1899 as a local grocery credit reporting service in Atlanta, making it the oldest of the three major bureaus. Experian and TransUnion followed in the mid-20th century as the need for standardized credit data grew nationally.
By the 1970s, all three bureaus were collecting data from credit card issuers and reporting it in a standardized format. The Fair Credit Reporting Act of 1970 was passed to regulate how that data could be collected, used, and disputed, and it remains the primary consumer protection law governing credit reports today.
This infrastructure is the reason your Visa payment in California shows up on a report pulled by a lender in New York.
The invention of the credit score
Having centralized data was useful, but lenders still had to manually interpret credit files, which was slow, inconsistent, and often biased.
In 1989, Fair Isaac Corporation released the first FICO score, a single three-digit number designed to summarize a consumer's credit risk in a way that any lender could instantly evaluate. The score was built primarily around patterns observed in credit card behavior, specifically whether payments were made on time and how much of the available credit limit was being used.
Those two behaviors, payment history and credit utilization, remain the single most important factors in FICO scoring today, making up 65% of the score combined. This reflects just how central credit card behavior was to the original model.
VantageScore launched in 2006 as a joint venture between all three bureaus, introducing a competing model with slightly different weightings. Both scores range from 300 to 850 and are still the two primary scoring algorithms in use today.
Read more >> What's the Difference Between FICO and VantageScore?
How credit card usage impacts your credit score today
Today, credit cards are one of the most common ways to build and maintain a credit history. How you use them, from making payments on time to managing your balances, can directly influence your credit score and how lenders assess your creditworthiness.
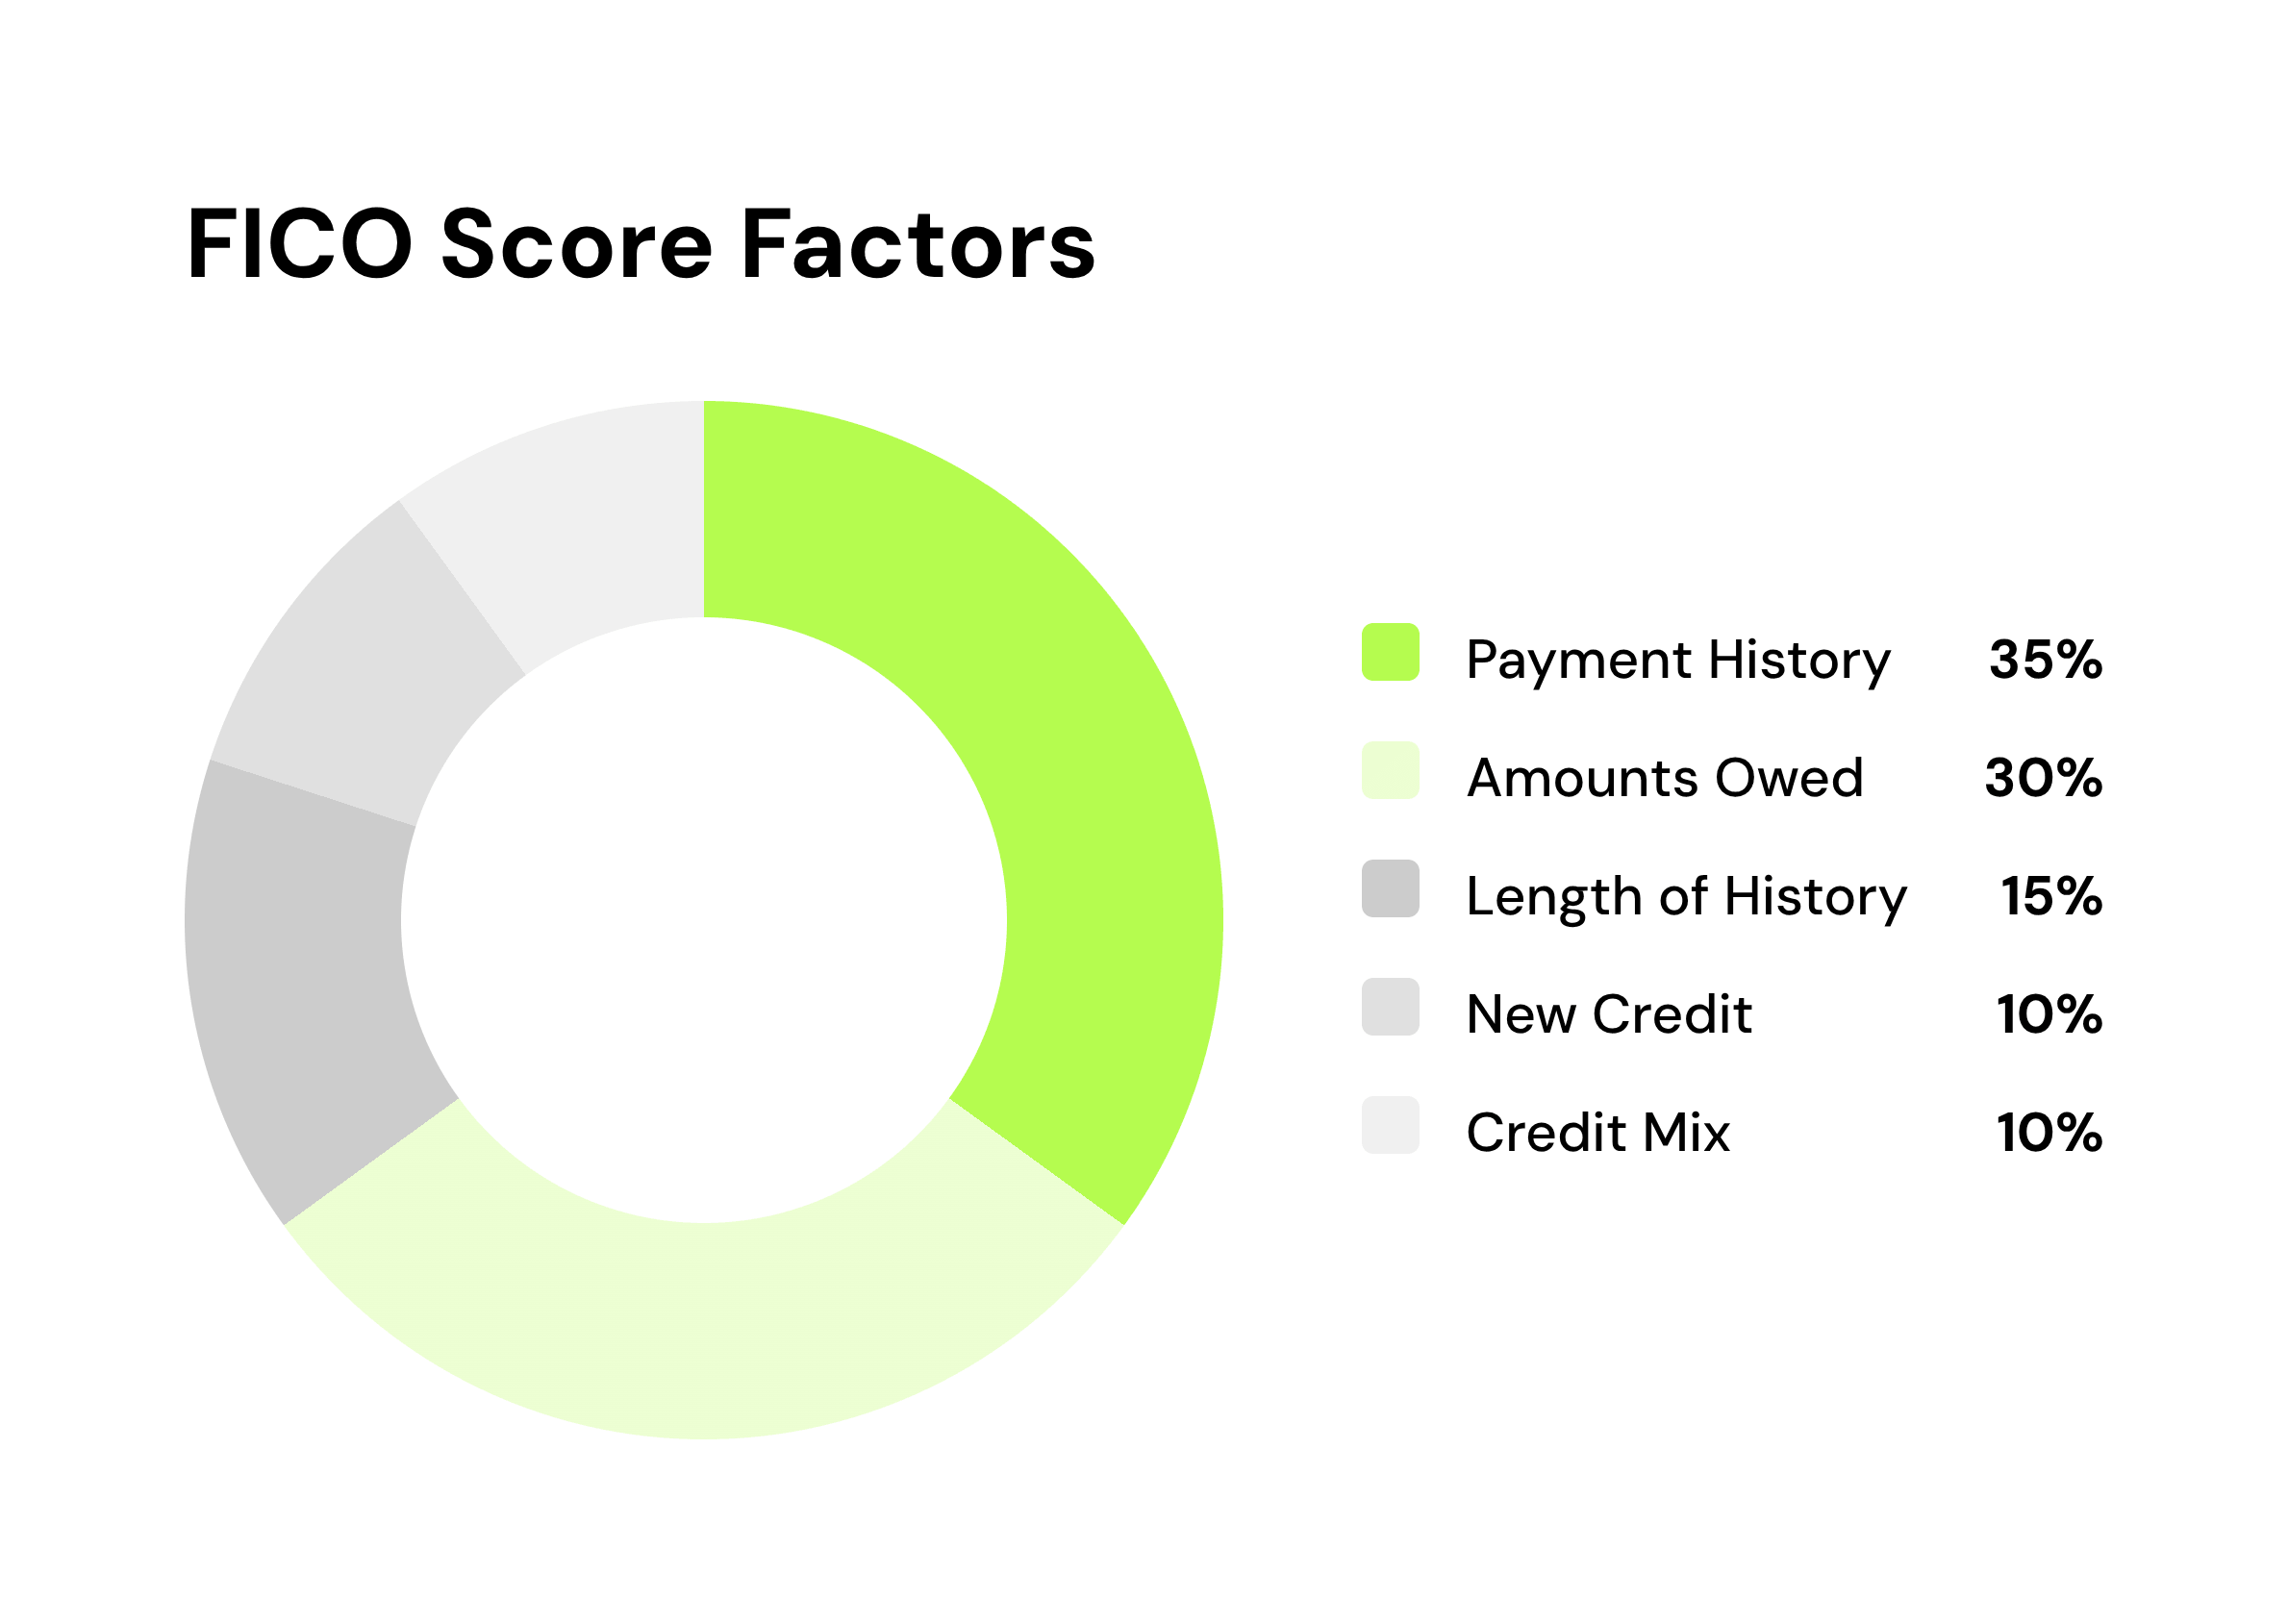
The FICO scoring model uses five weighted categories to calculate your credit score:
- Payment history (35%): The single most important factor, and on-time card payments build it while one missed payment can stay on your report for up to seven years. Autopay the minimum, and pay the full statement balance when you can.
- Amounts owed (30%): This looks at how much debt you carry overall, including card balances, loan balances, and how many accounts have balances. Credit utilization, your card balances as a share of your limits, is a big piece: (balance / limit) x 100, so $250 on a $1,000 limit is 25%. Stay under 30%, since maxing out a card can drop your score right away.
- Length of credit history (15%): Older accounts signal reliability, and cards count through your oldest account’s age and the average age of all accounts. Keep old cards open, since closing one shortens your history and can raise your utilization.
- Credit mix (10%): Lenders like to see you handle both revolving credit (cards) and installment credit (loans). It’s only 10% of your score, so don’t take on debt you don’t need just for variety.
- New credit (10%): Each card application triggers a hard inquiry that stays on your report for two years but affects your score for about one. A single inquiry has a small impact, but many in a short window can signal financial stress, so space applications three to six months apart.
Small, consistent habits with your credit cards add up to a stronger score over time. By paying on time, keeping balances low, and applying for new cards only when you need them, you can use your credit cards to build a stronger credit profile.
Read more >> Best Credit Cards for Lowering Utilization: High Limit, Balance Transfer, or Secured?
Credit cards vs. credit-builder loans: which builds credit faster?
Credit cards are generally the more efficient option for most people because they affect two major scoring factors simultaneously: payment history (35%) and credit utilization (30%). That means every month you use a credit card responsibly, you're building in two directions at once.
Credit-builder loans, by contrast, only affect payment history. They also lock up your funds for the loan term and typically charge interest and fees, meaning you're paying to build credit rather than simply using credit you already need.
CBLs do serve one specific purpose: adding an installment account to your credit mix if you have none. That can be useful for someone who only has revolving credit and wants to diversify. But as a primary credit-building tool, a credit card, or a credit account like the one Kikoff offers, is a more flexible and cost-effective path.
Kikoff's Credit Account is a revolving tradeline that reports to all three bureaus, building both payment history and credit utilization simultaneously with no hard credit check to sign up.
The modern credit card landscape
Today, there are more credit card products available than at any point in history, ranging from secured cards designed for first-time users to premium travel cards with annual fees in the hundreds of dollars.
The core credit-building mechanics haven't changed since FICO launched in 1989: pay on time, keep your balances low, and don't open too many accounts too quickly. What has changed is access. Secured cards, student cards, and credit-building platforms have made it possible for people with thin or no credit history to enter the system in a way that wasn't available to previous generations.
Digital tools also make it significantly easier to monitor your credit in real time, set up automatic payments, and catch fraud early. Every individual who banks or uses credit today has more visibility into their financial profile than any generation before them.
Bottom line
Credit cards have evolved from paper charge plates to the primary engine behind how credit scores are built and measured.
The history of credit cards is basically the history of modern credit scoring itself, and understanding that connection helps explain why on-time payments and low utilization carry so much weight. Those behaviors were baked into the scoring model from the beginning because they were the behaviors that credit cards made visible at scale.
If you're looking to put those principles to work, Kikoff makes it easy to start building positive payment history with a revolving credit account that reports to all three major bureaus. Build credit responsibly with Kikoff's plans, starting at $5 a month.
Frequently Asked Questions
Disclaimer: The information provided in this blog post is meant for informational purposes only and does not constitute financial advice.